Knowing your name does not make someone trustworthy.
Being rushed to pay? Stop first.If you transferred money, contact your bank immediately and call 165; if someone comes to collect money, threatens you or poses immediate danger, call 110。Steps for your situation。
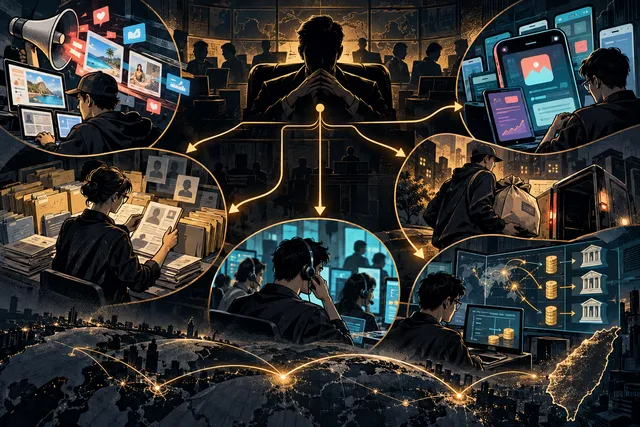
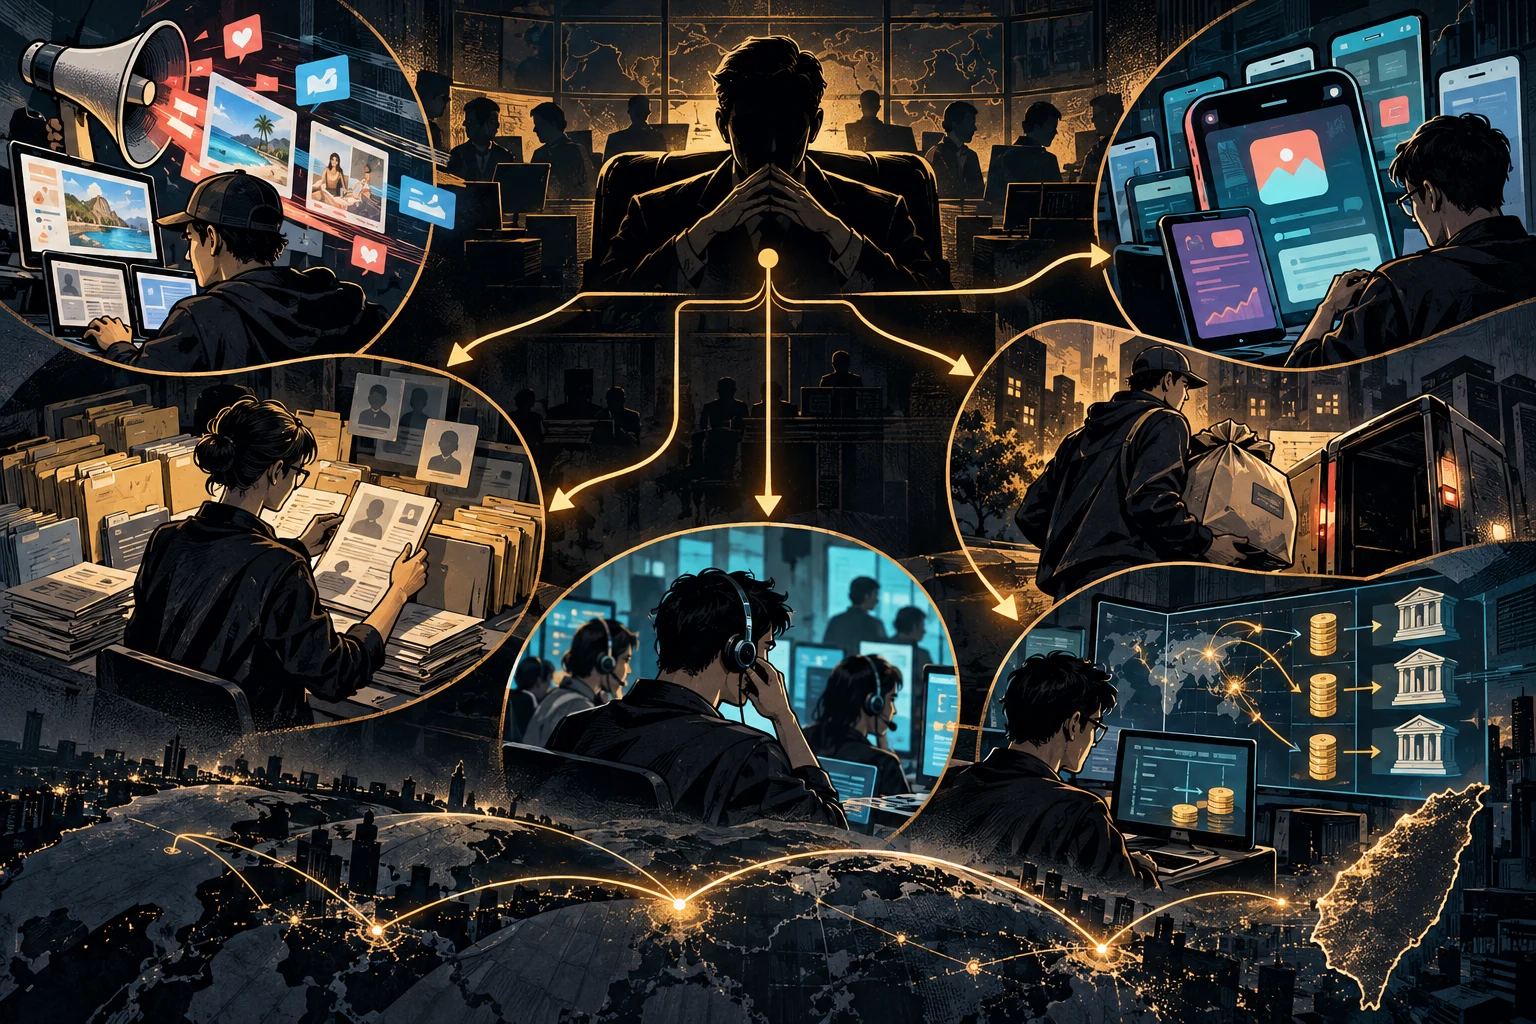
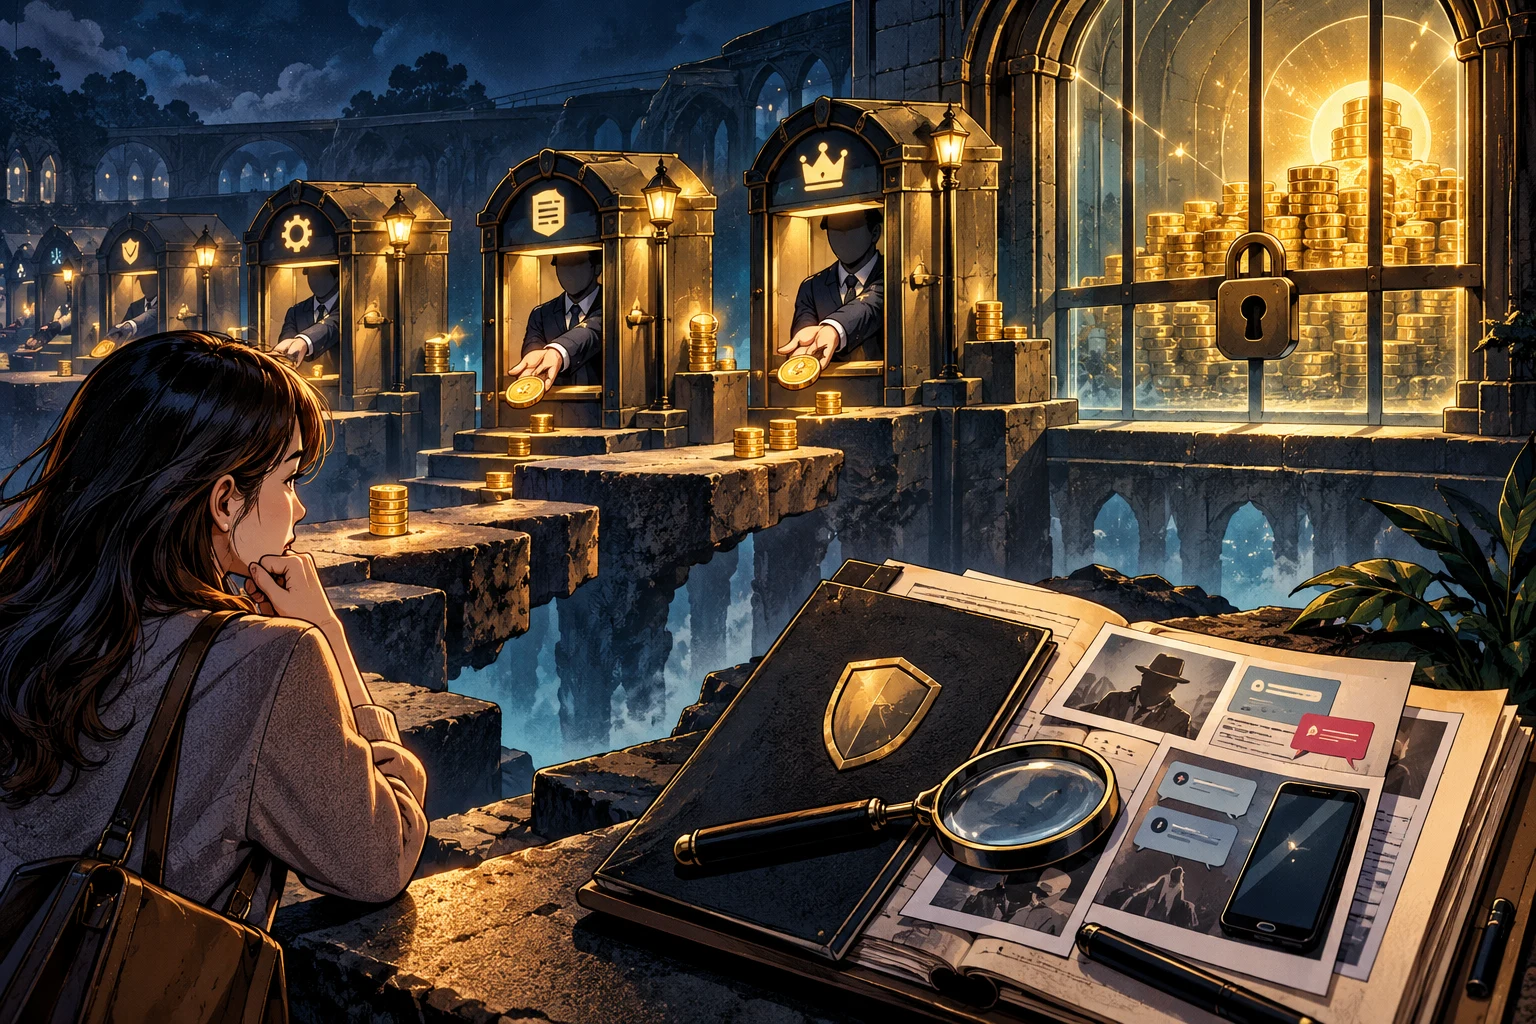
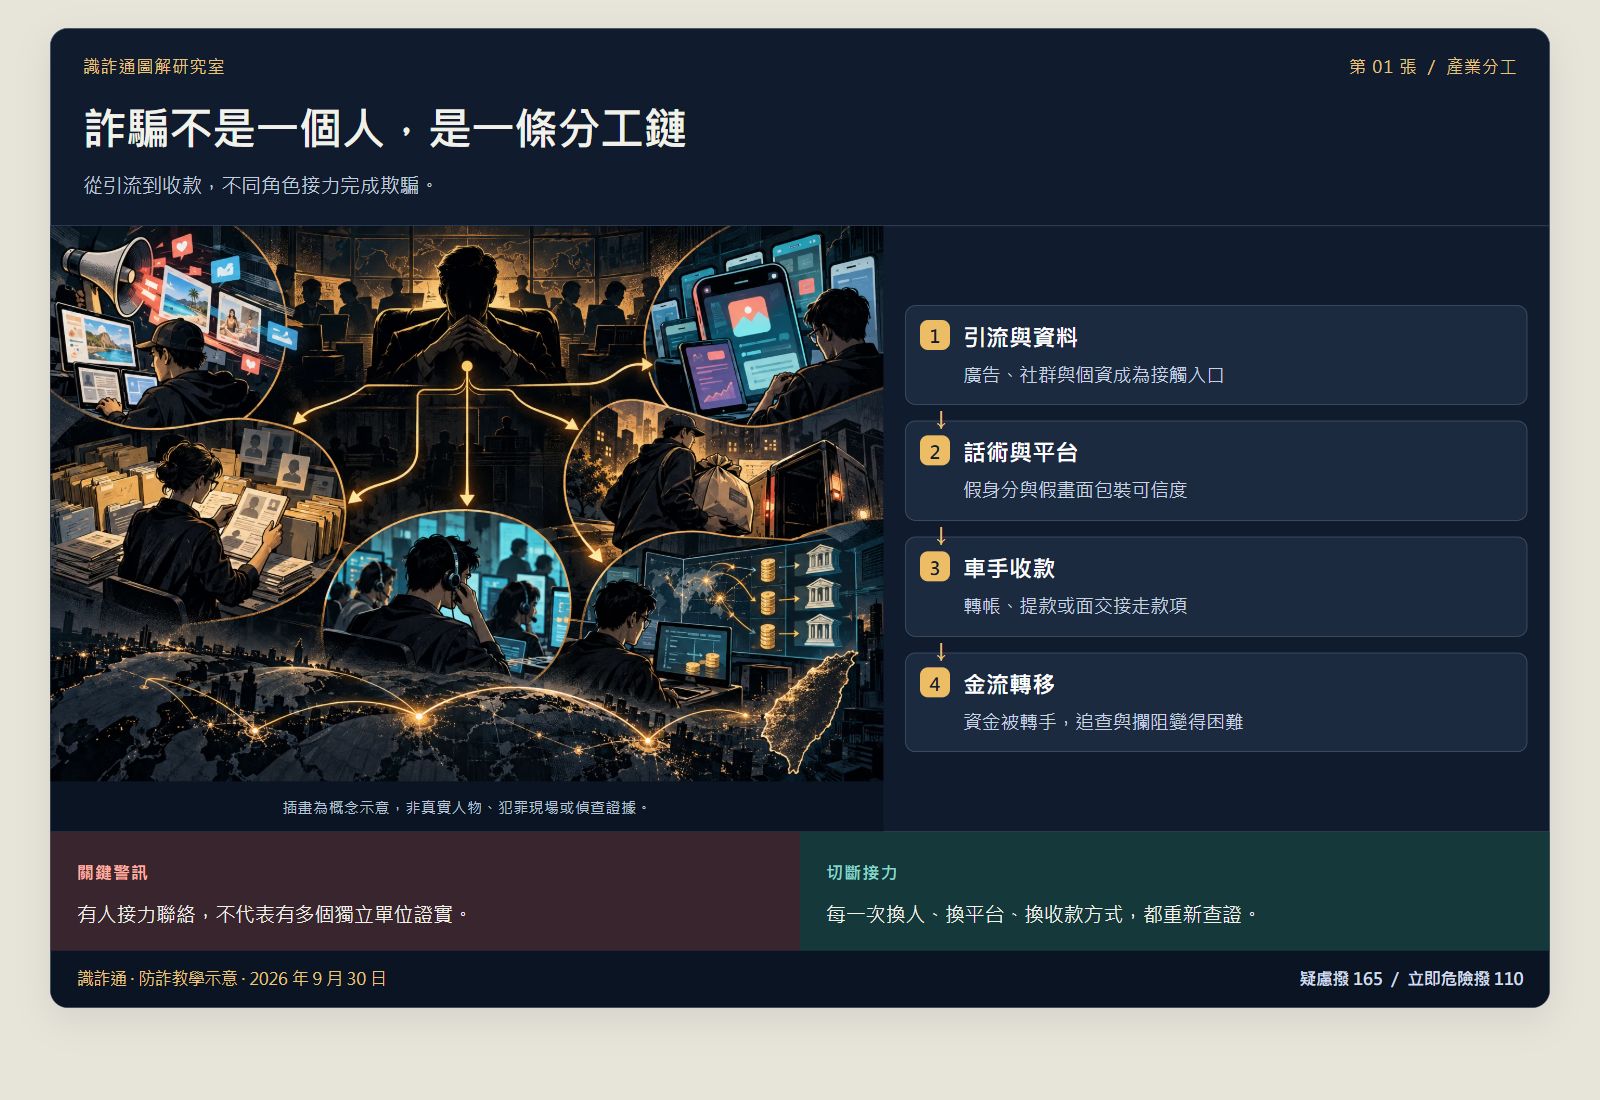
Different people work together, from first contact to collecting money.
Conceptual illustration, not real people, a crime scene or investigative evidence.
1
Outreach and data
Ads, social media and personal data create contact opportunities.
2
Scripts and platforms
False identities and fabricated screens create credibility.
3
Cash collection
Money is collected through transfers, withdrawals or in-person handovers.
4
Moving funds
Funds change hands, making tracing and interception harder.
Warning signs
Several callers do not mean several independent agencies have confirmed the story.
Protective action
Verify again whenever the person, platform or payment method changes.
Open sources and scope
Based on official advice and cases. The four stages are simplified for teaching; roles and order differ between cases and do not establish wrongdoing by any particular person or service.
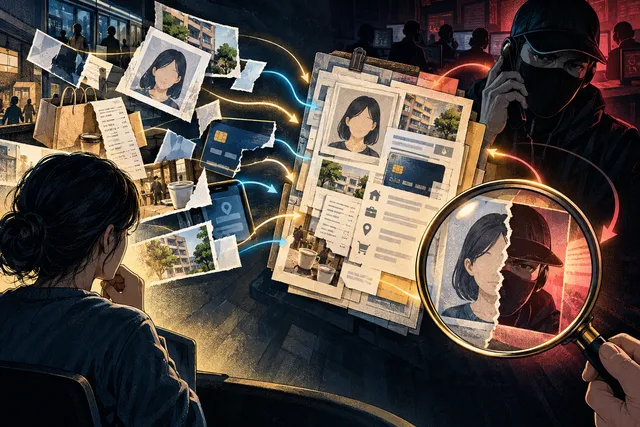
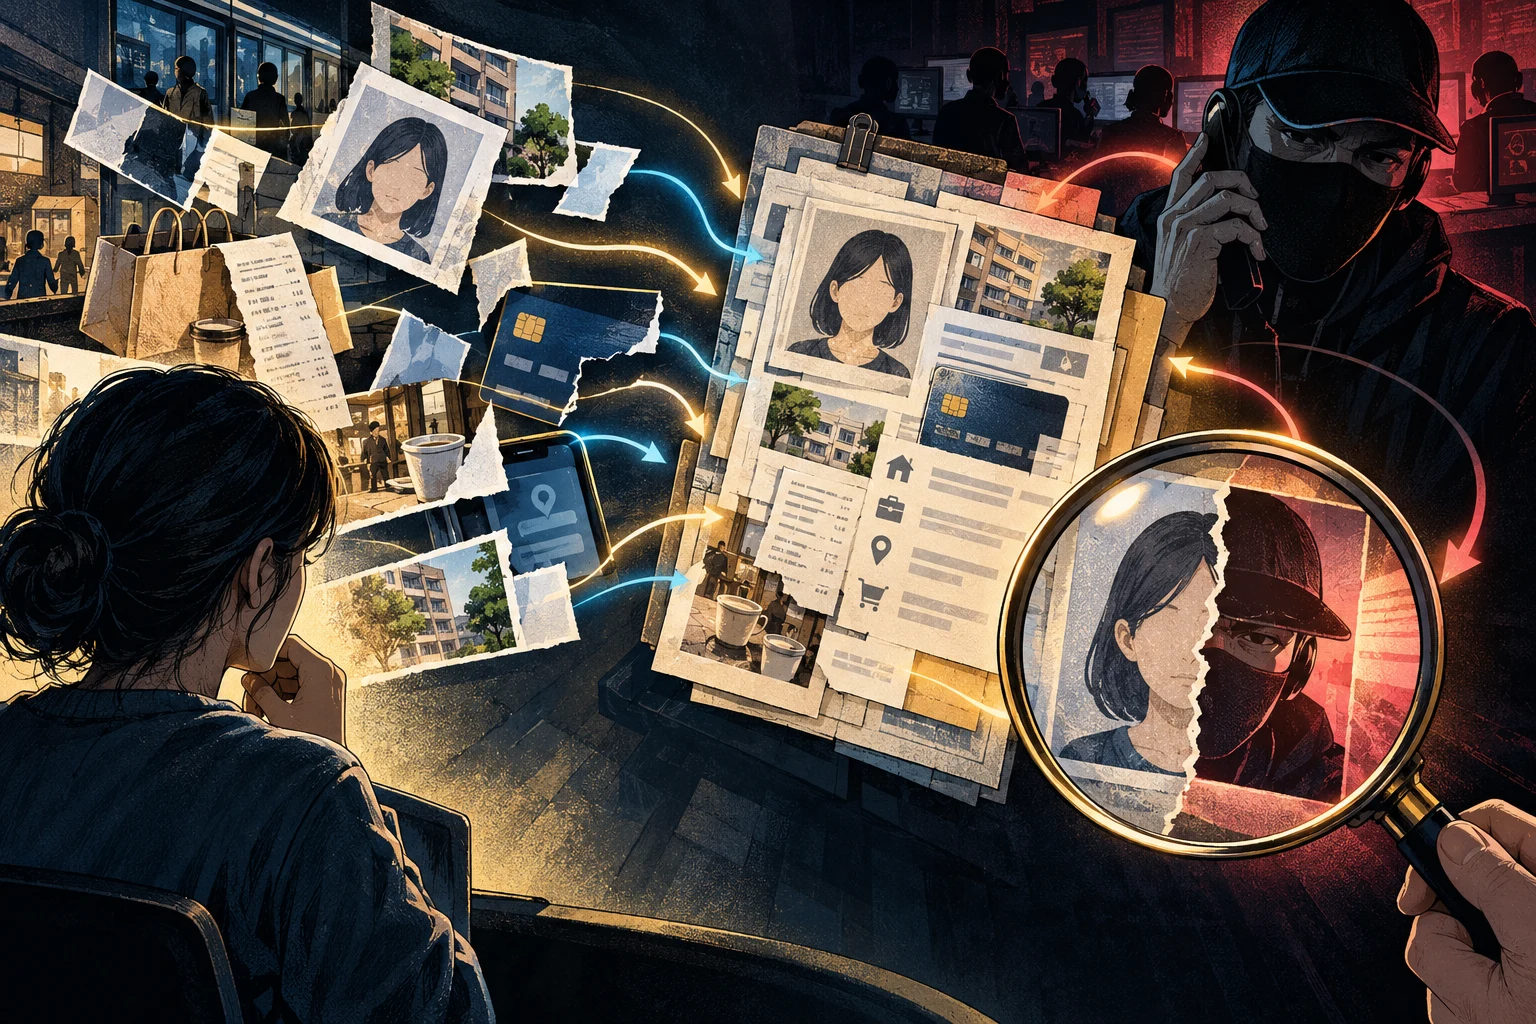
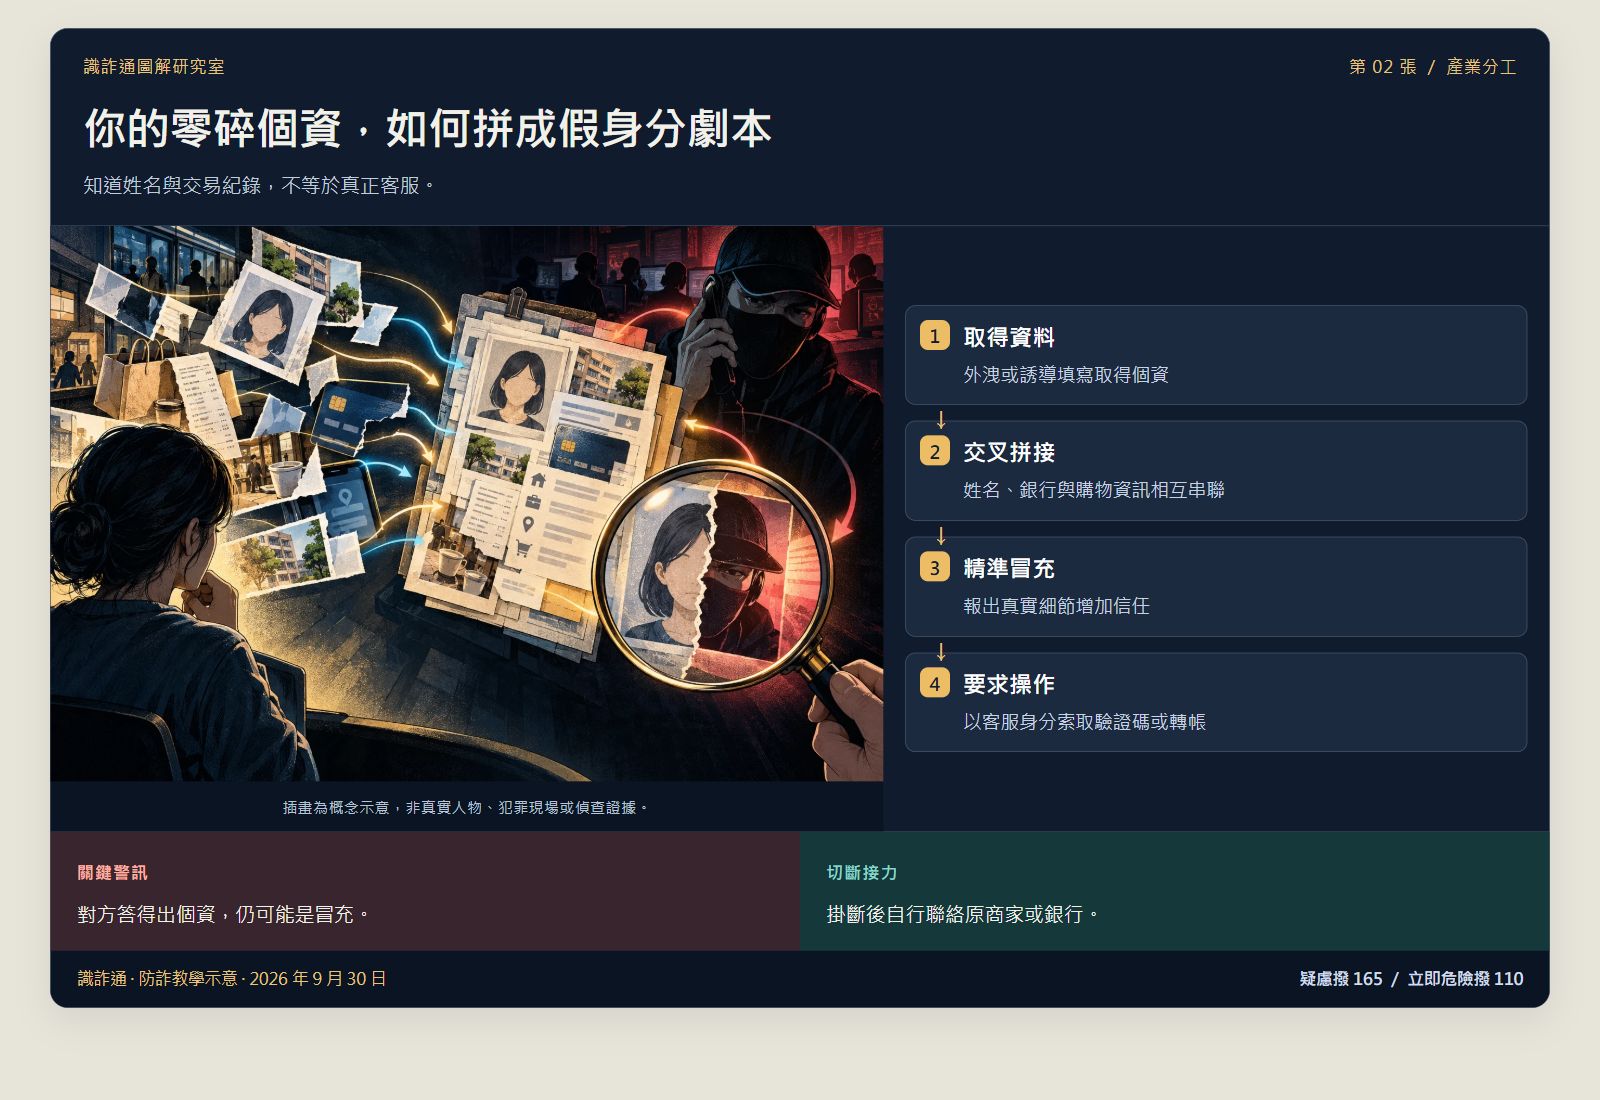
How fragments of your data support an impersonation
Knowing your name and transactions does not make someone genuine customer support.
Conceptual illustration, not real people, a crime scene or investigative evidence.
1
Obtaining data
Leaks or deceptive forms expose personal information.
2
Combining records
Names, bank details and purchase information are linked.
3
Targeted impersonation
Real details are quoted to gain trust.
4
Requesting action
Someone posing as support asks for verification codes or a transfer.
Warning signs
A caller who knows your details may still be an impostor.
Protective action
Hang up and contact the original retailer or bank yourself.
Open sources and scope
Based on official advice and cases. The four stages are simplified for teaching; roles and order differ between cases and do not establish wrongdoing by any particular person or service.
Shi Zha Tong visual guides 03 / Calls and personal data
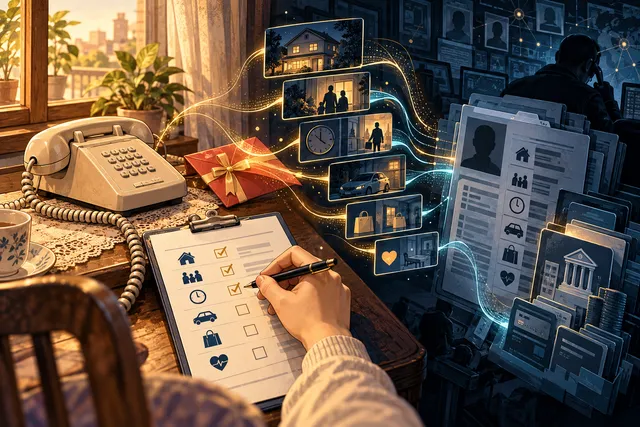
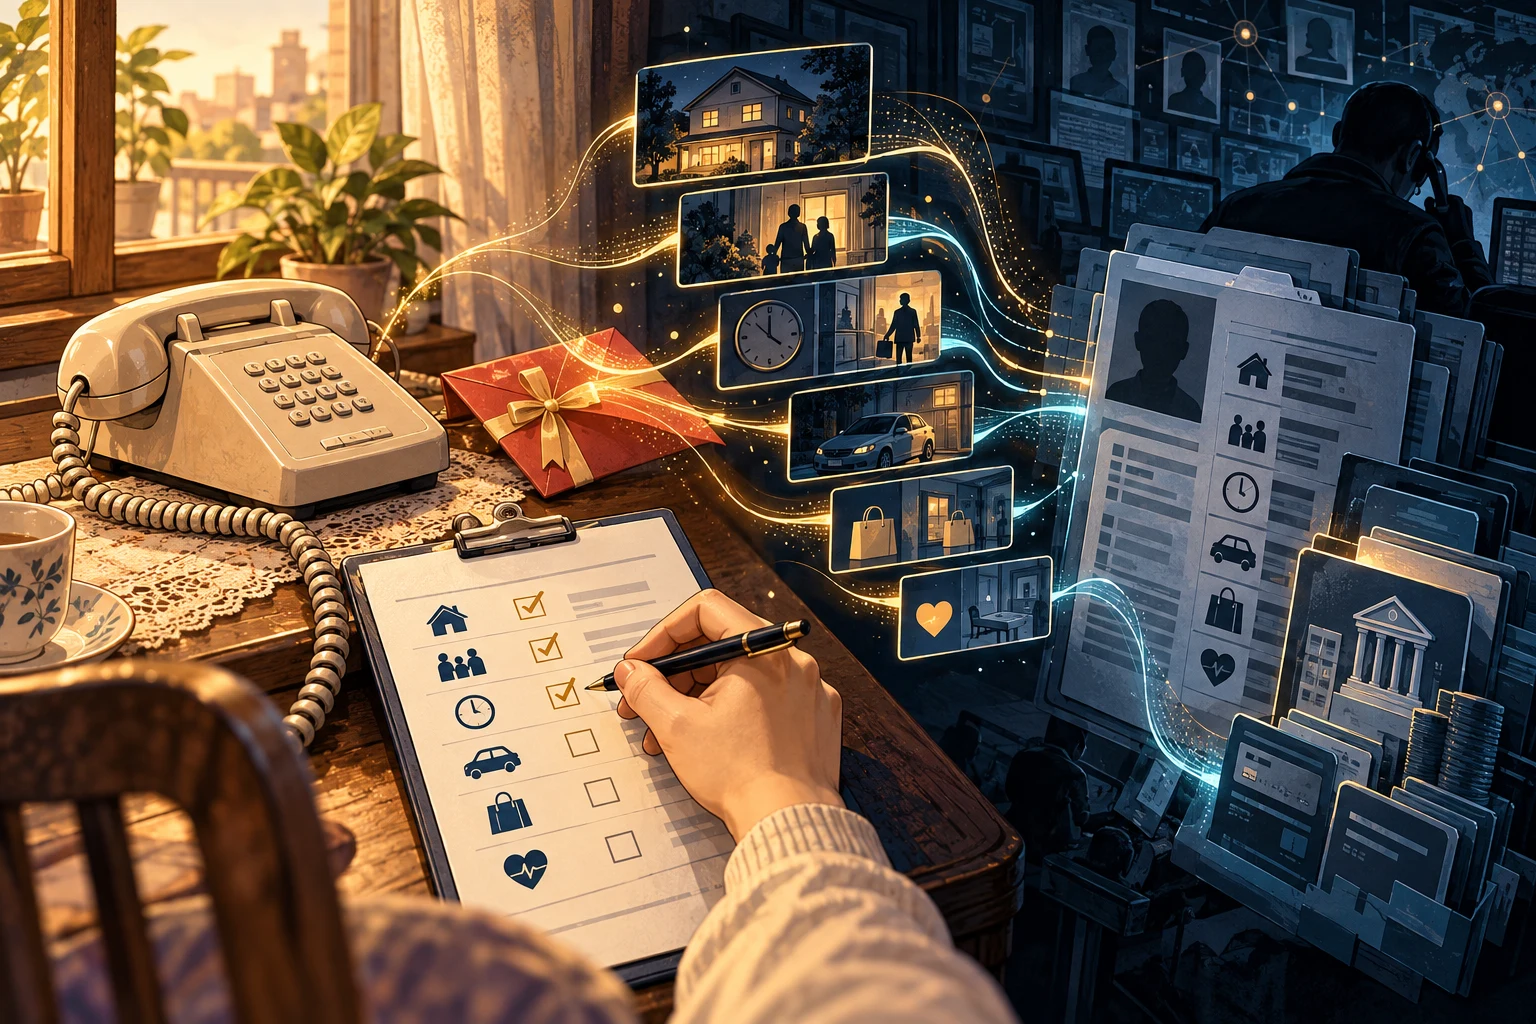
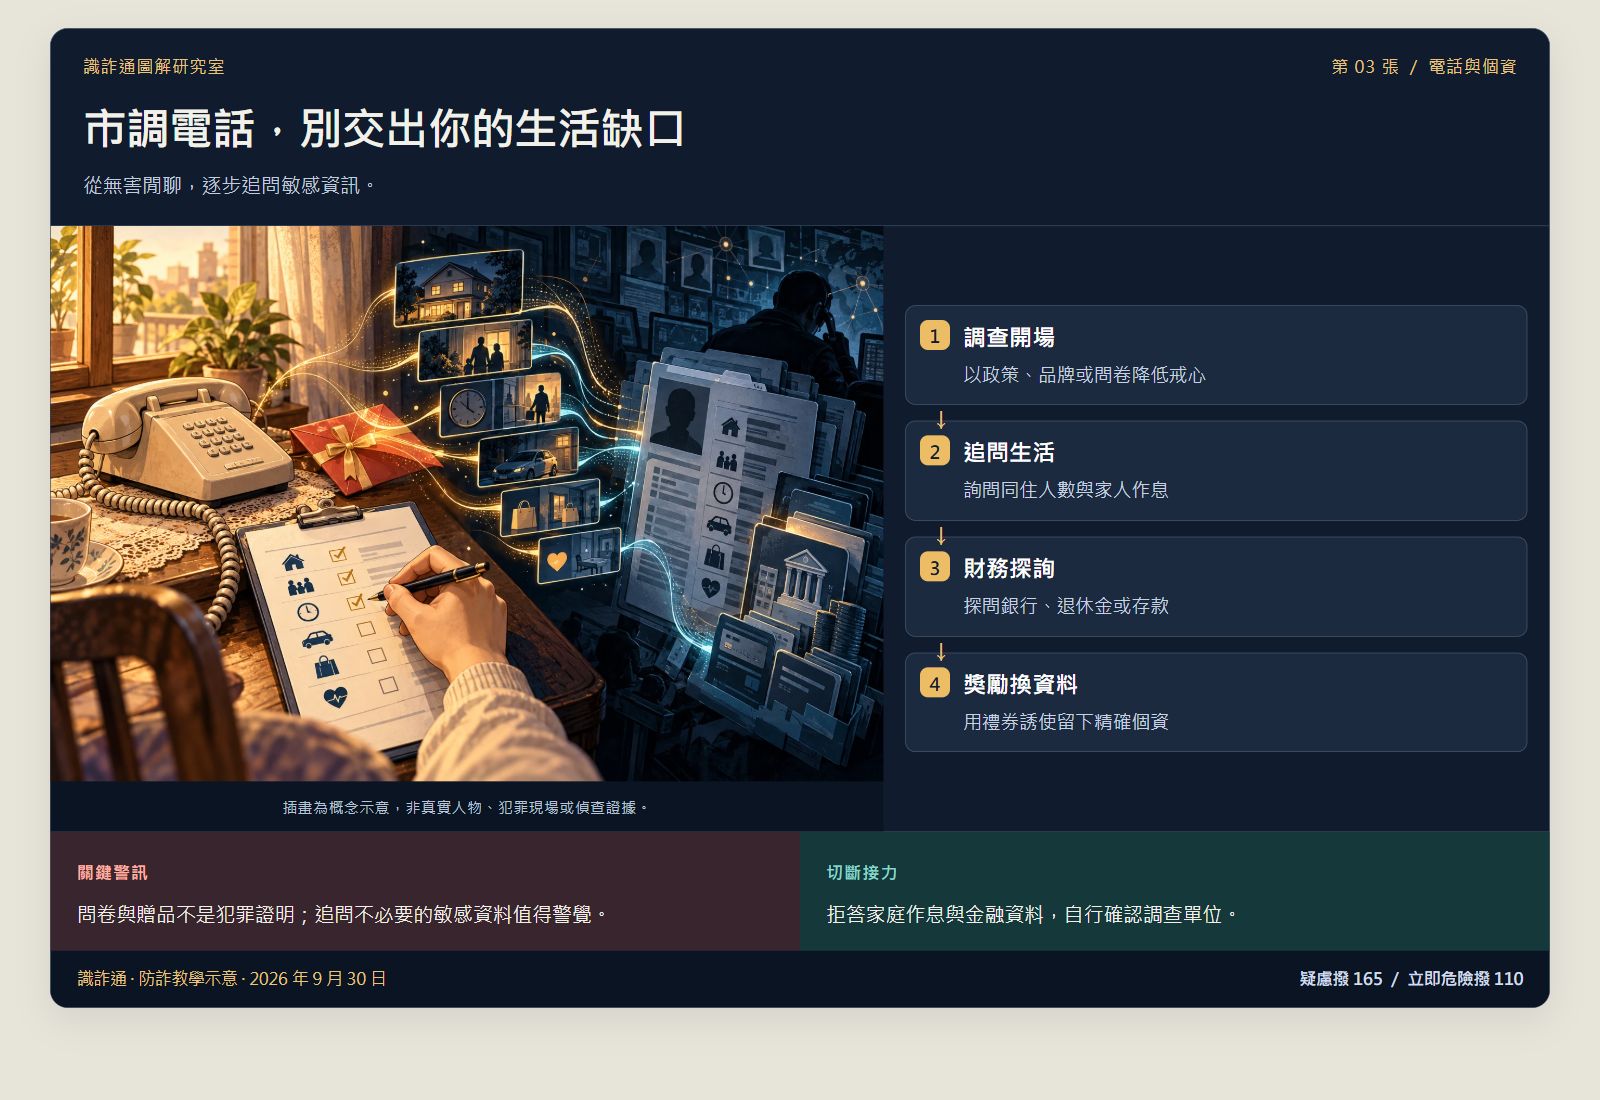
Survey calls: protect your private routines
An ordinary conversation can turn into questions about sensitive information.
Conceptual illustration, not real people, a crime scene or investigative evidence.
1
Survey introduction
Policy, brand or questionnaire topics lower suspicion.
2
Household questions
Questions reveal who lives with you and family schedules.
3
Financial questions
The caller asks about banks, pensions or savings.
4
Rewards for data
Gift vouchers encourage disclosure of precise personal details.
Warning signs
Surveys and gifts are not proof of crime. Unnecessary sensitive questions deserve caution.
Protective action
Decline questions about family routines and finances. Verify the survey organisation independently.
Open sources and scope
Based on official advice and cases. The four stages are simplified for teaching; roles and order differ between cases and do not establish wrongdoing by any particular person or service.
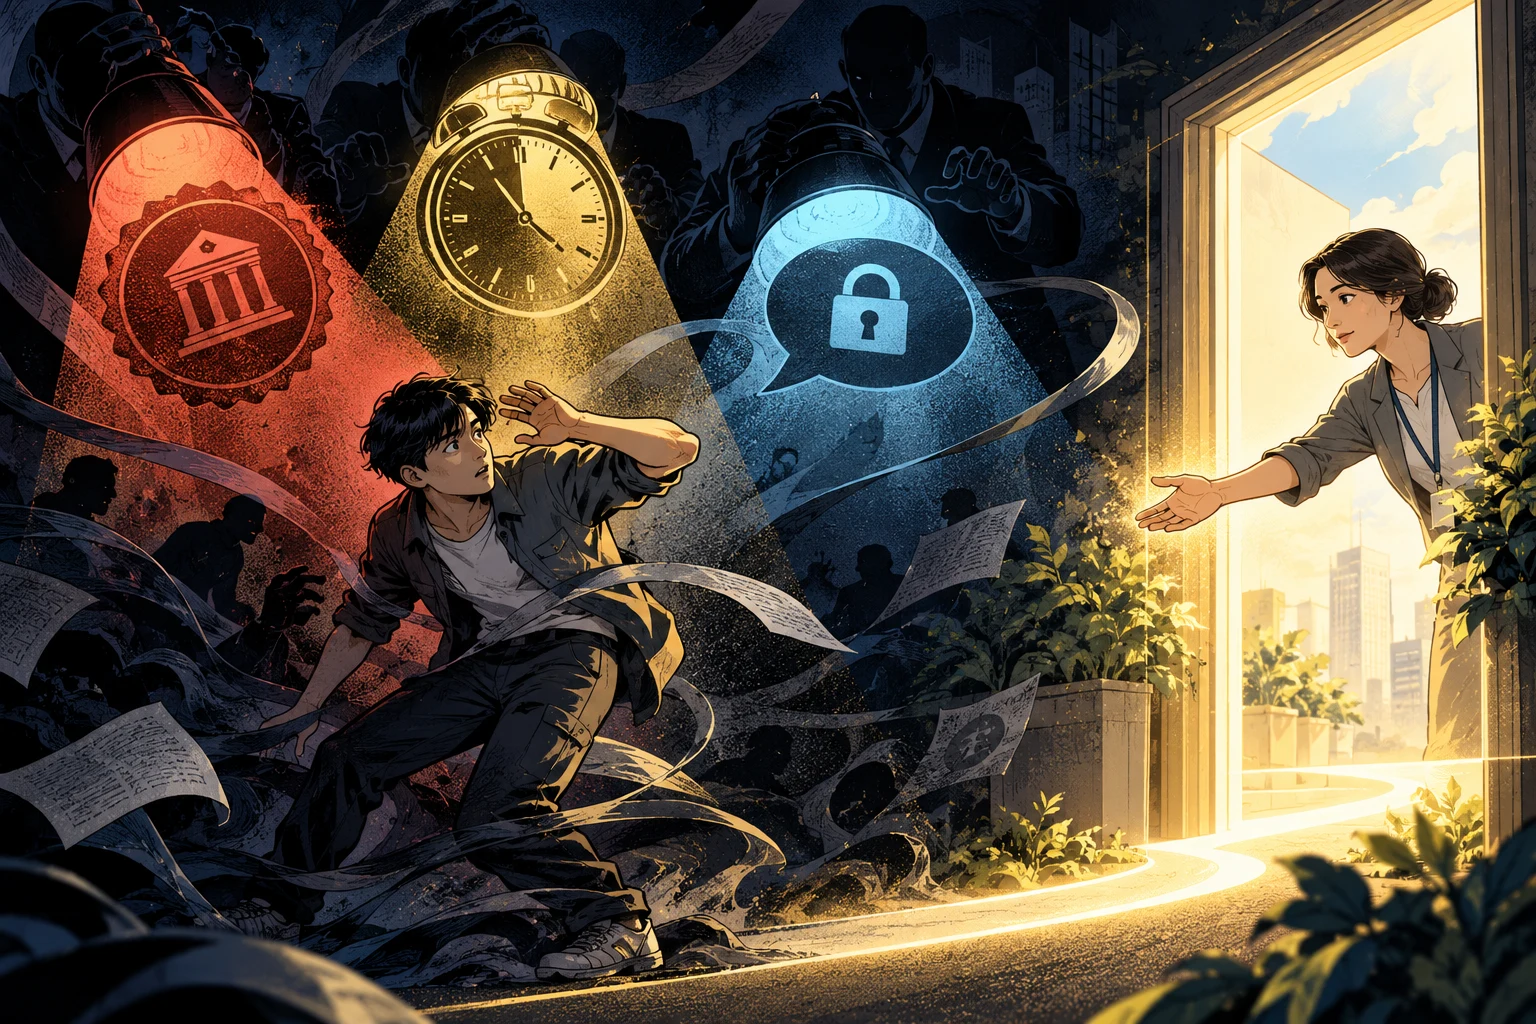
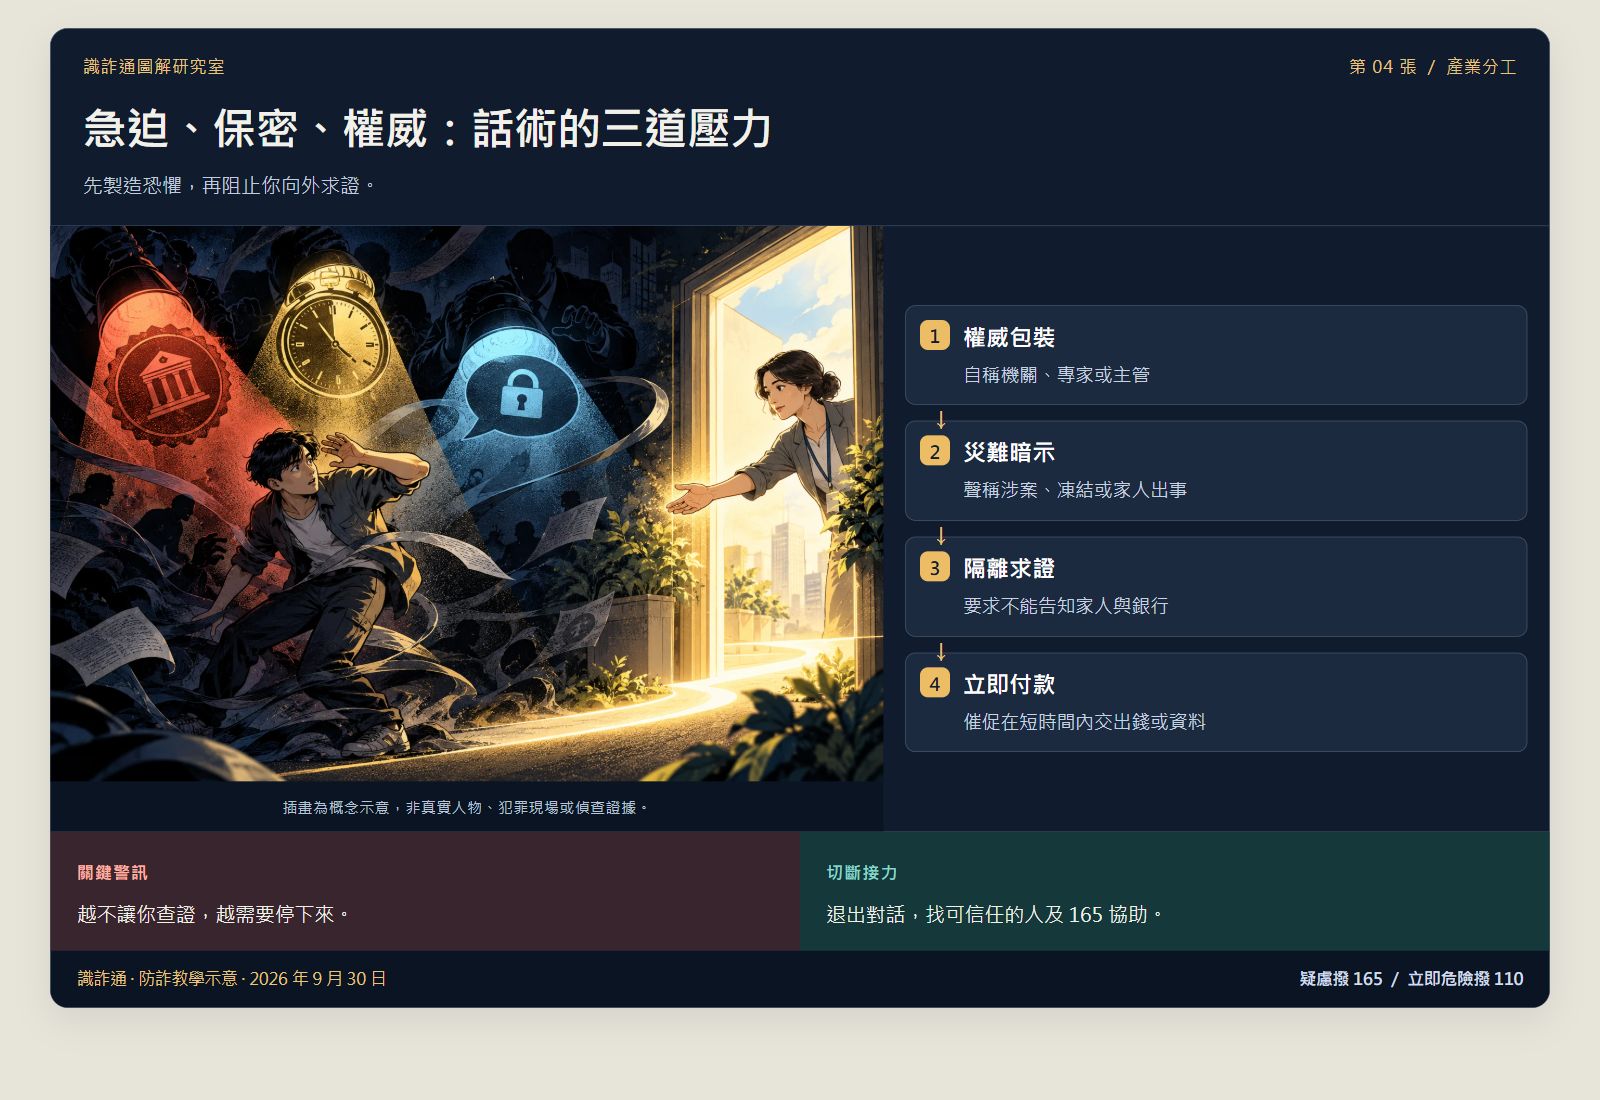
Urgency, secrecy and authority: three forms of pressure
Fear is created first, then outside verification is blocked.
Conceptual illustration, not real people, a crime scene or investigative evidence.
1
Claiming authority
The caller claims to be an agency, expert or supervisor.
2
Threatening trouble
They mention an investigation, frozen funds or a family emergency.
3
Blocking verification
They tell you not to inform family or your bank.
4
Demanding payment
They demand money or information within a short deadline.
Warning signs
The harder someone makes verification, the more important it is to stop.
Protective action
Leave the conversation and ask someone you trust or 165 for help.
Open sources and scope
Based on official advice and cases. The four stages are simplified for teaching; roles and order differ between cases and do not establish wrongdoing by any particular person or service.
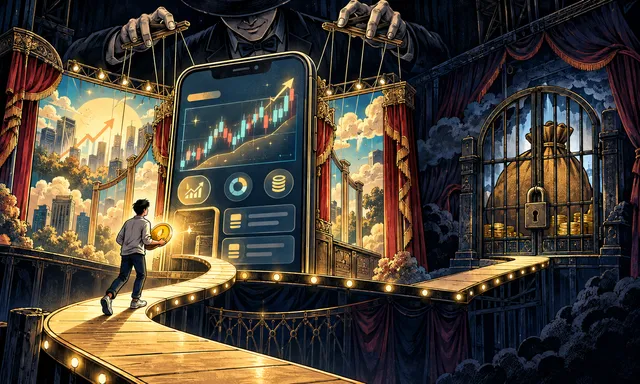
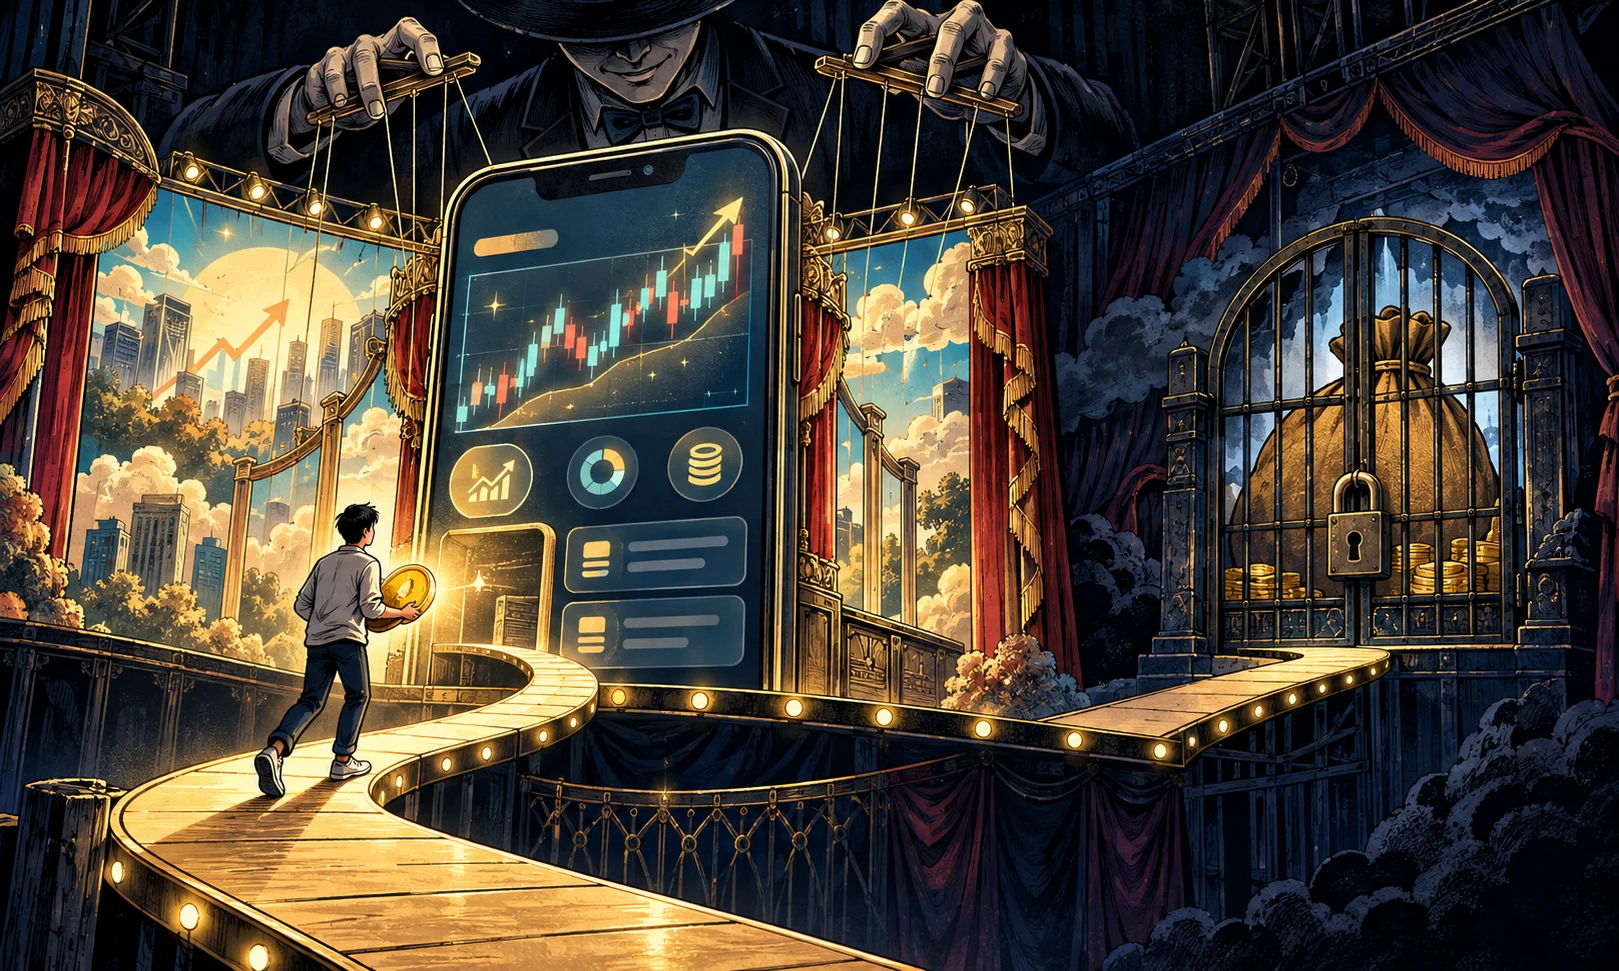
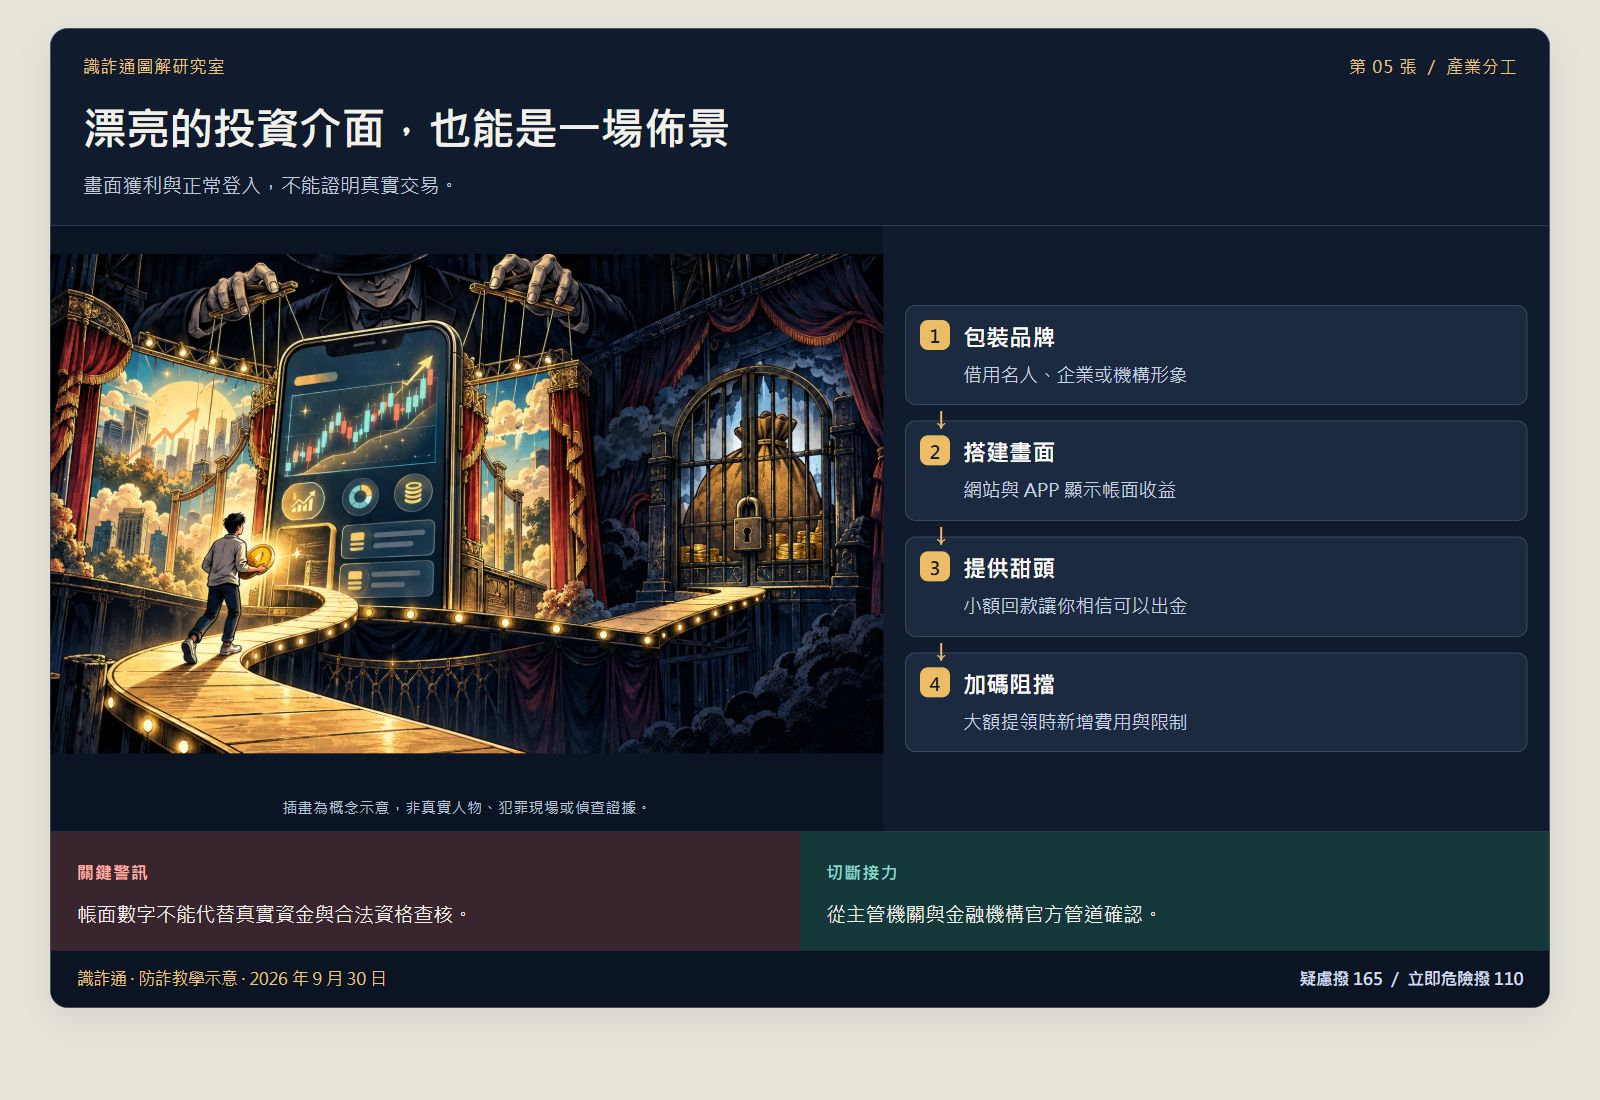
A polished investment screen can be a staged display
Displayed profits and a working login do not prove real transactions.
Conceptual illustration, not real people, a crime scene or investigative evidence.
1
Borrowed credibility
Celebrity, company or institution identities are borrowed.
2
Fabricated interface
A website or app displays apparent account gains.
3
A small payout
A small payout makes withdrawals seem possible.
4
Withdrawal barriers
Larger withdrawals trigger new fees and restrictions.
Warning signs
On-screen numbers cannot replace checks on actual funds and regulatory status.
Protective action
Verify through official channels of the regulator and financial institution.
Open sources and scope
Based on official advice and cases. The four stages are simplified for teaching; roles and order differ between cases and do not establish wrongdoing by any particular person or service.
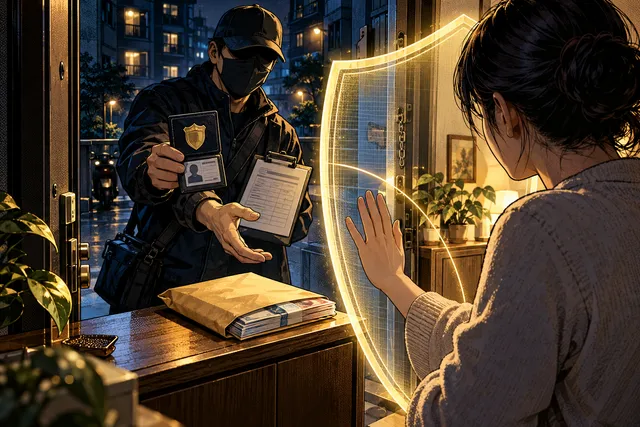
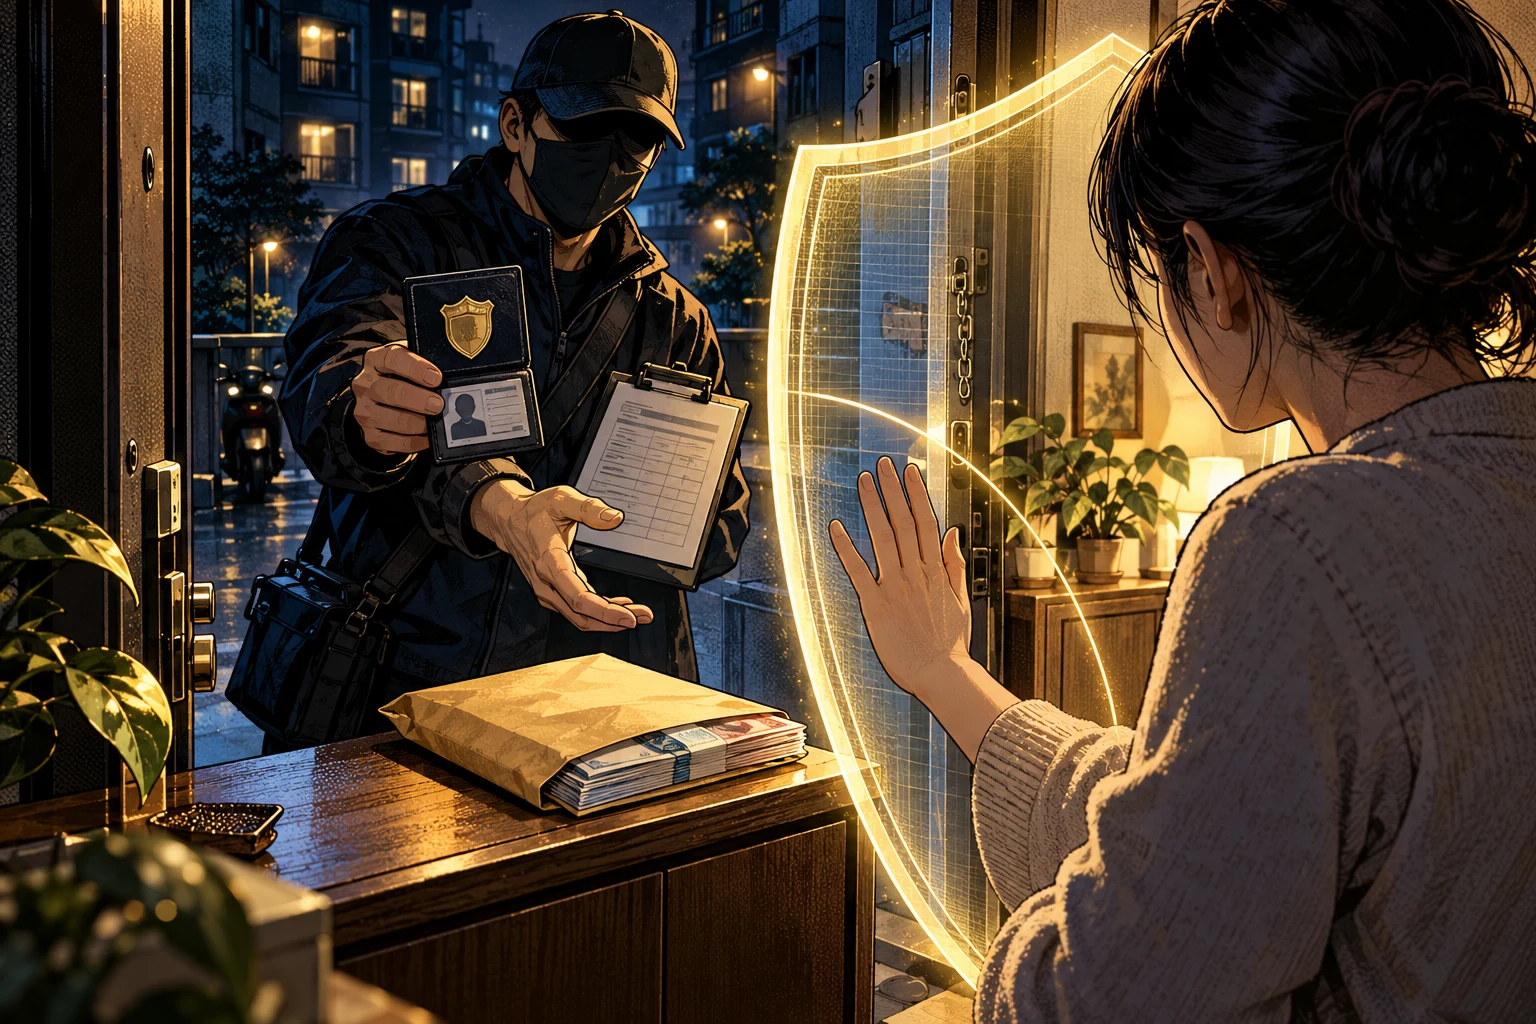
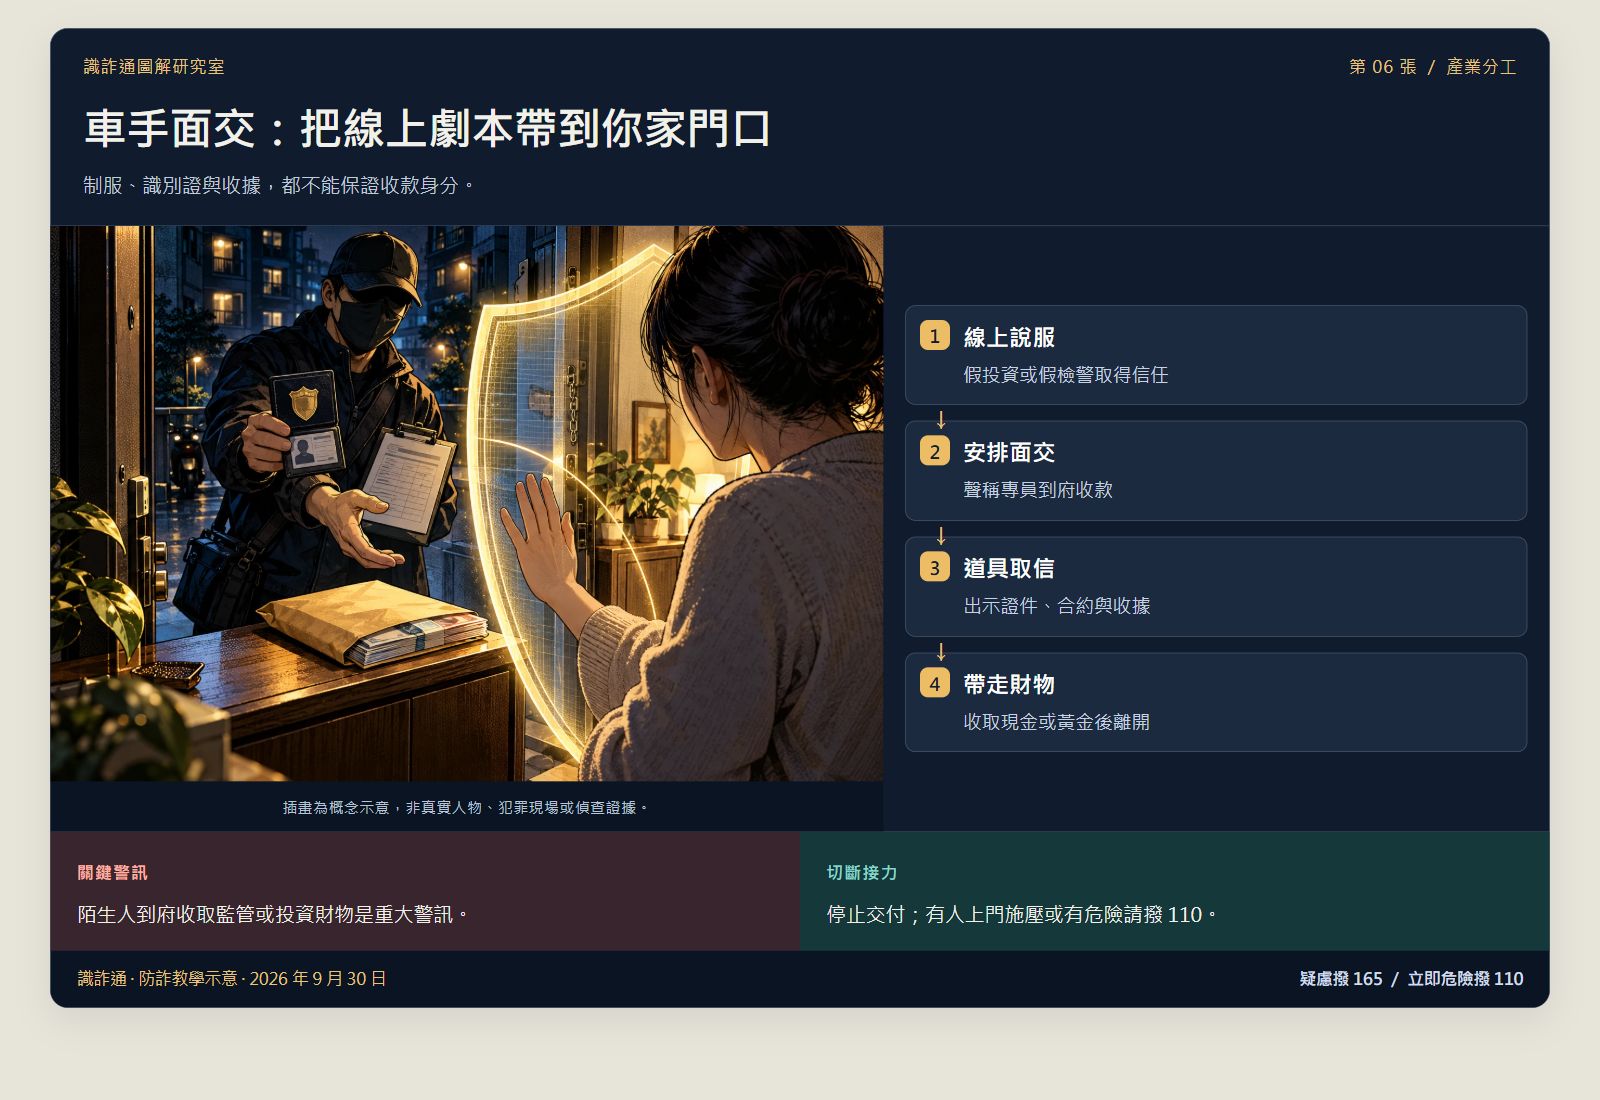
Uniforms, ID badges and receipts do not guarantee who is collecting money.
Conceptual illustration, not real people, a crime scene or investigative evidence.
1
Online persuasion
A fake investment or police story gains trust.
2
Arranging a handover
A supposed representative is sent to collect money at home.
3
Props for credibility
Identification, contracts and receipts are shown.
4
Taking valuables
The collector leaves with cash or gold.
Warning signs
A stranger collecting assets for ‘supervision’ or investment at home is a serious warning sign.
Protective action
Do not hand anything over. Call 110 if someone pressures you at your door or there is danger.
Open sources and scope
Based on official advice and cases. The four stages are simplified for teaching; roles and order differ between cases and do not establish wrongdoing by any particular person or service.
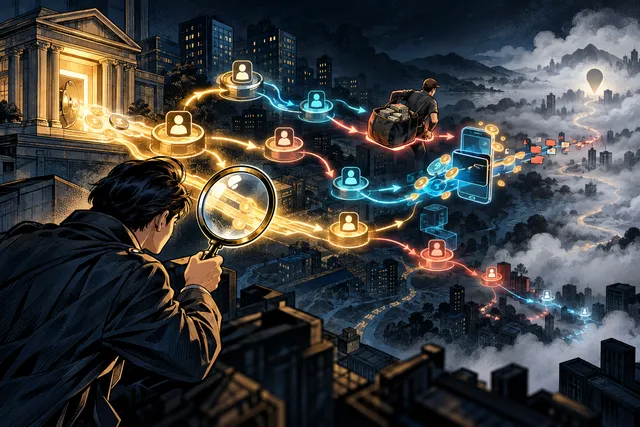
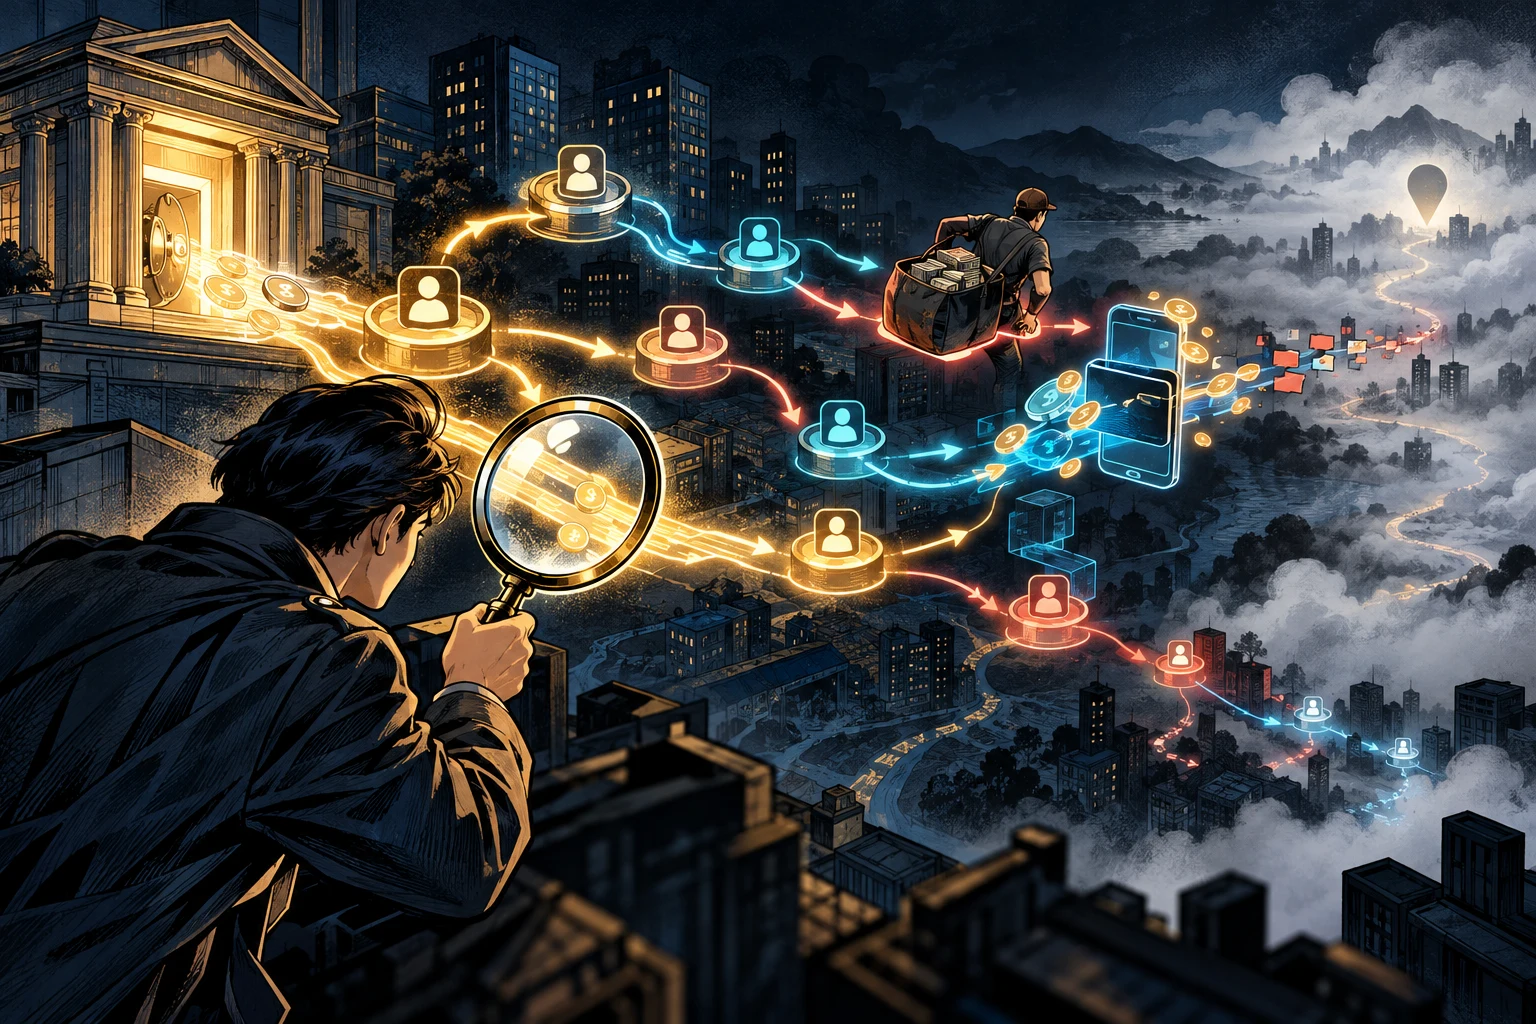
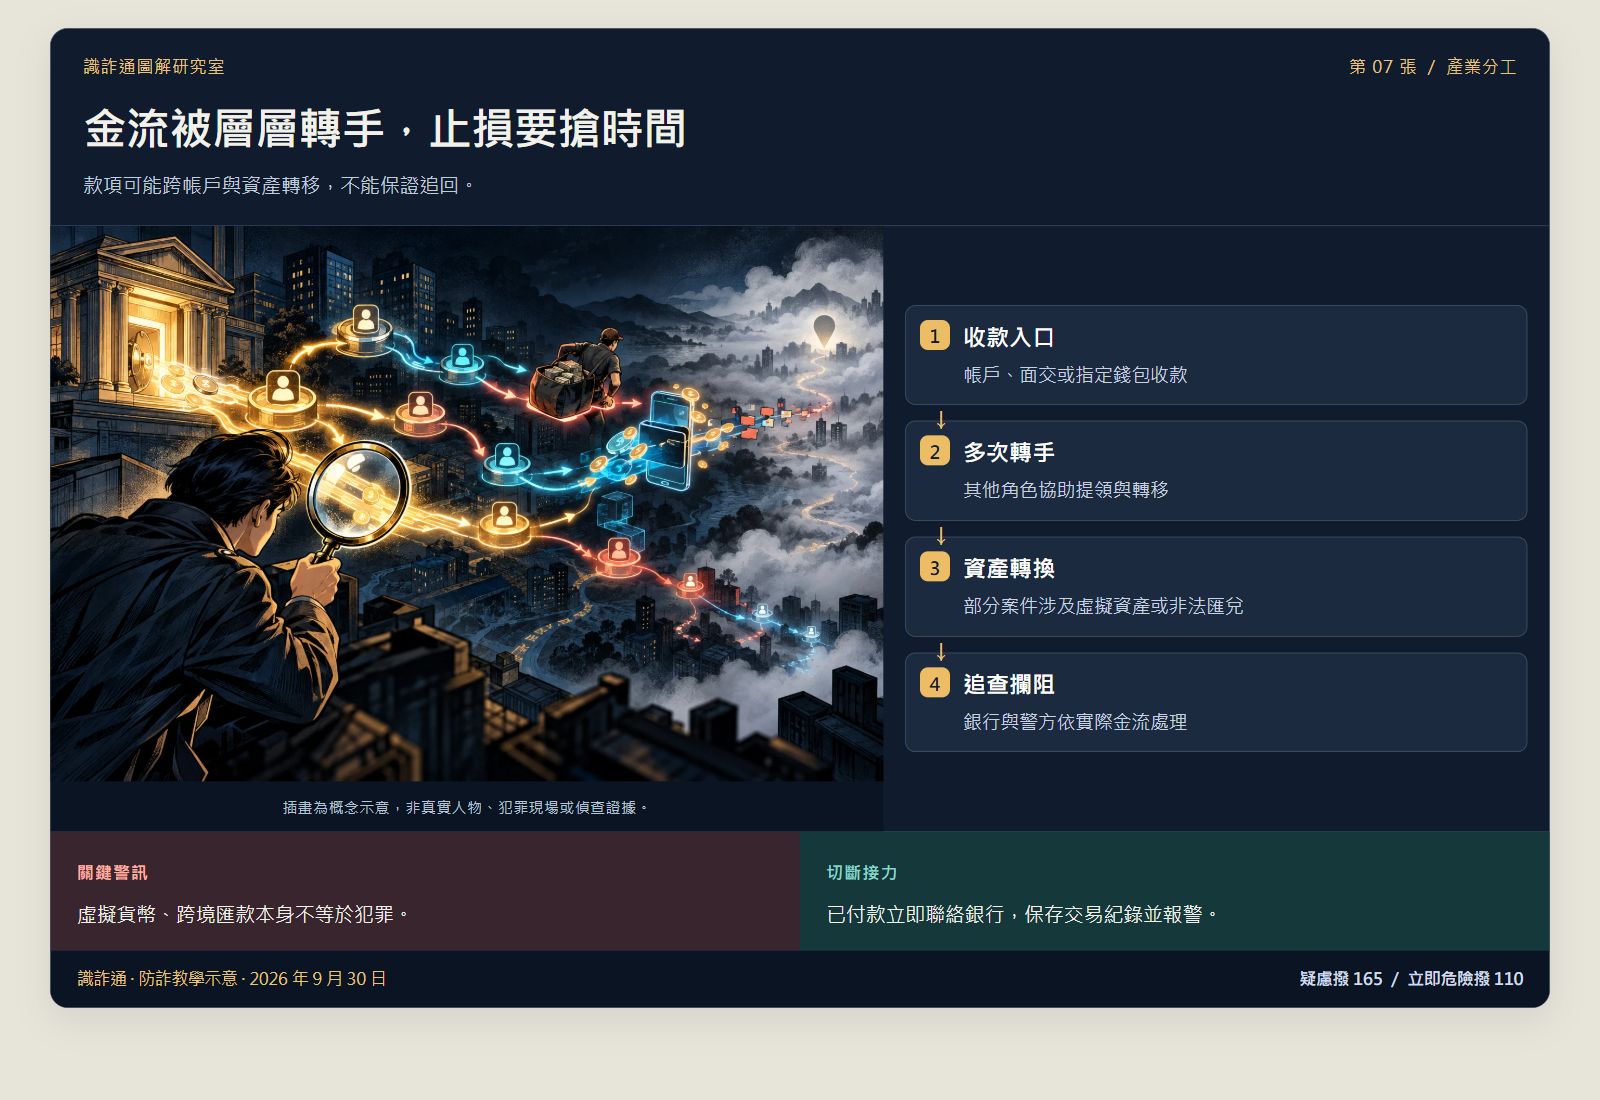
Money may move between accounts and assets. Recovery is not guaranteed.
Conceptual illustration, not real people, a crime scene or investigative evidence.
1
Receiving money
Money enters through accounts, cash handovers or specified wallets.
2
Repeated transfers
Other people help withdraw and move the money.
3
Changing assets
Some cases involve virtual assets or illegal remittance operations.
4
Tracing and interception
Banks and police act on the actual financial trail.
Warning signs
Cryptocurrency and cross-border remittances are not crimes in themselves.
Protective action
If you paid, contact your bank immediately, save transaction records and report to police.
Open sources and scope
Based on official advice and cases. The four stages are simplified for teaching; roles and order differ between cases and do not establish wrongdoing by any particular person or service.
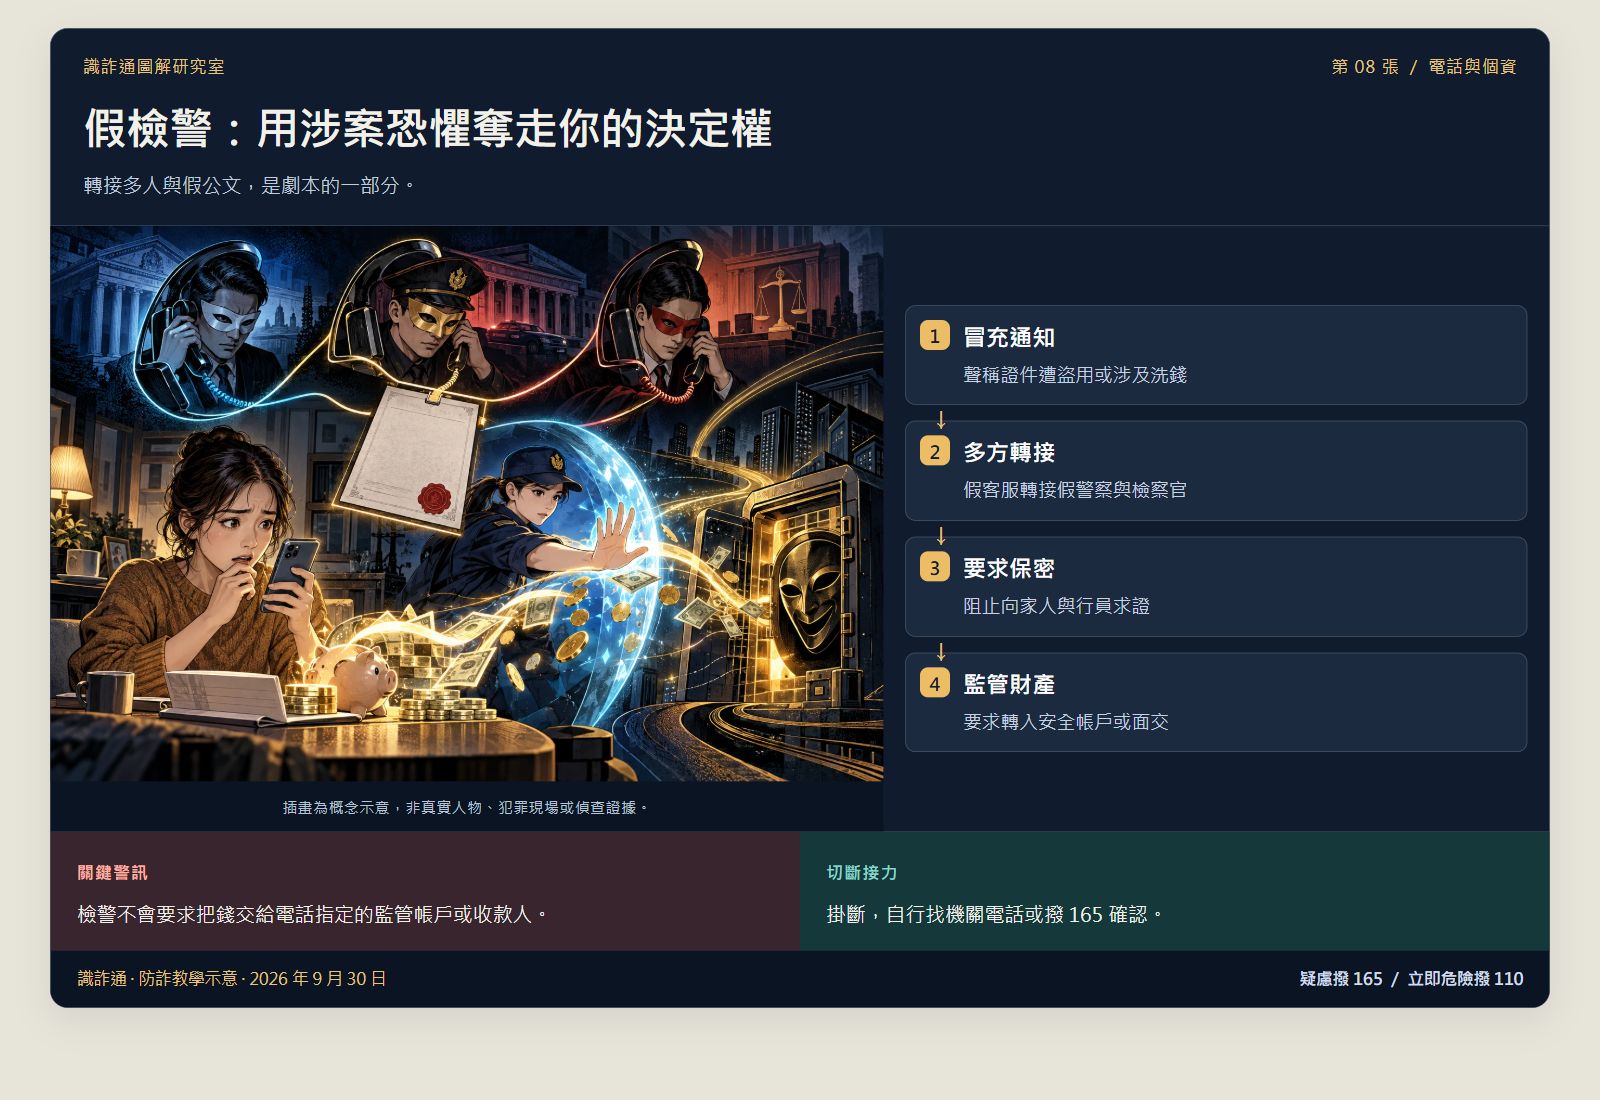
Shi Zha Tong visual guides 08 / Calls and personal data
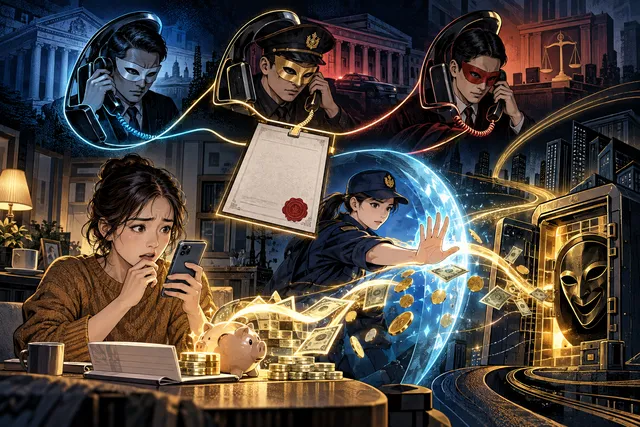
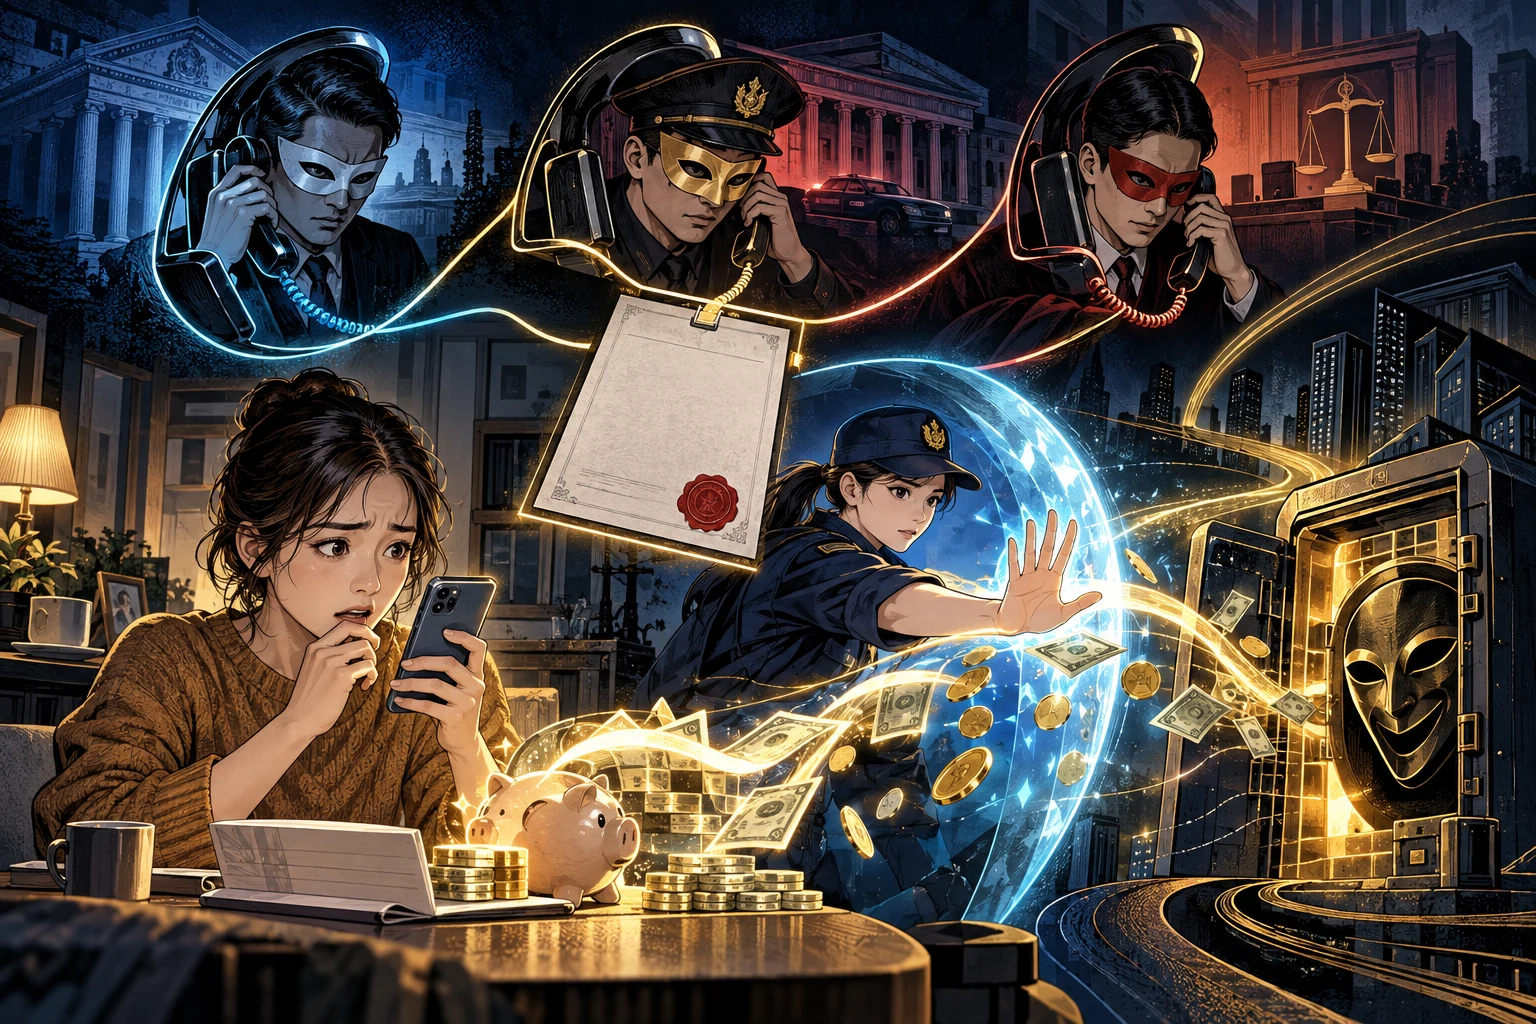
Fake police exploit fear of being investigated
Multiple call transfers and forged documents can be parts of the same script.
Conceptual illustration, not real people, a crime scene or investigative evidence.
1
False notification
Someone claims your identity was stolen or used for money laundering.
2
Transferred calls
Fake customer support transfers you to fake police and prosecutors.
3
Demanding secrecy
They prevent you from checking with family or bank staff.
4
Taking control of assets
They demand a transfer to a ‘safe account’ or an in-person handover.
Warning signs
Police and prosecutors do not tell you to give money to a supervised account or collector specified over the phone.
Protective action
Hang up. Find the agency’s number yourself or call 165 to check.
Open sources and scope
Based on official advice and cases. The four stages are simplified for teaching; roles and order differ between cases and do not establish wrongdoing by any particular person or service.
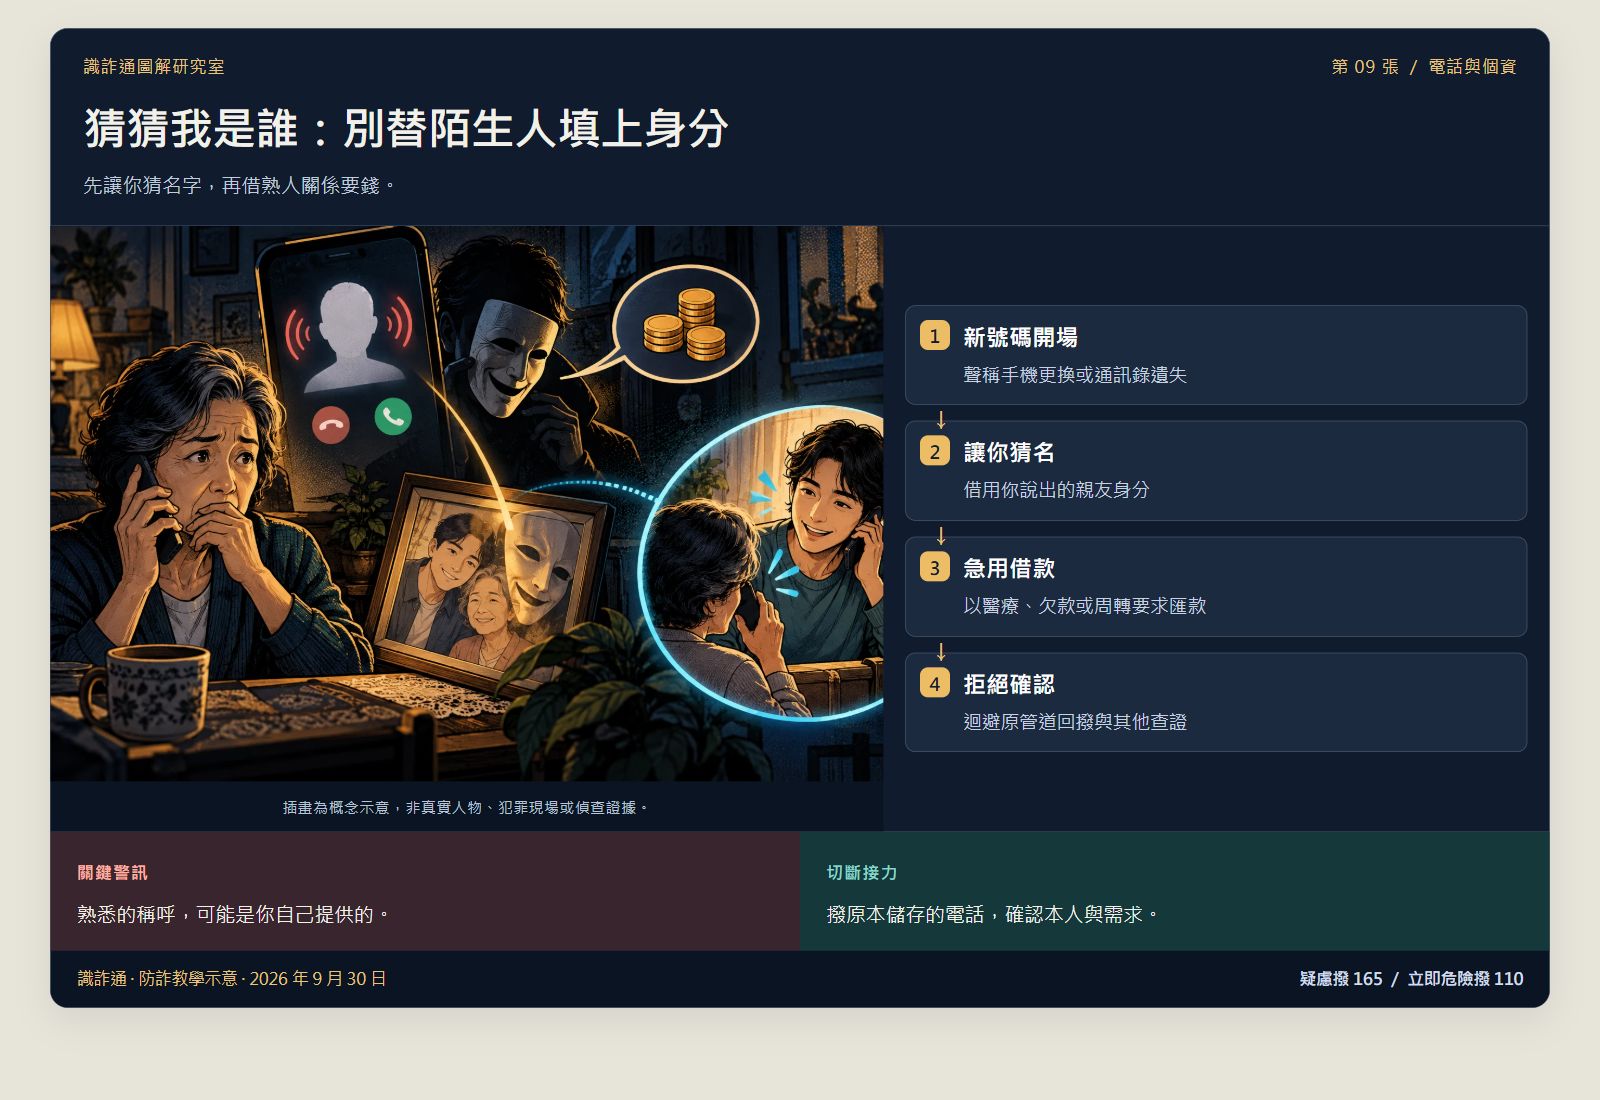
Shi Zha Tong visual guides 09 / Calls and personal data
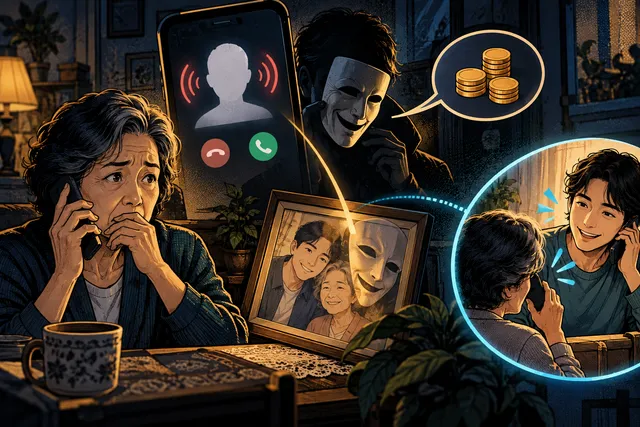
‘Guess who?’: do not supply an impostor’s identity
They let you guess a name, then use that relationship to ask for money.
Conceptual illustration, not real people, a crime scene or investigative evidence.
1
A new number
They claim a changed phone or lost contact list.
2
Getting you to guess
They adopt the relative or friend’s name you suggest.
3
An urgent loan
Medical bills, debt or cash-flow problems justify a transfer.
4
Avoiding confirmation
They avoid callbacks through known channels and other checks.
Warning signs
You may have supplied the familiar name yourself.
Protective action
Call the previously saved number to confirm the person and the request.
Open sources and scope
Based on official advice and cases. The four stages are simplified for teaching; roles and order differ between cases and do not establish wrongdoing by any particular person or service.
Shi Zha Tong visual guides 10 / Calls and personal data
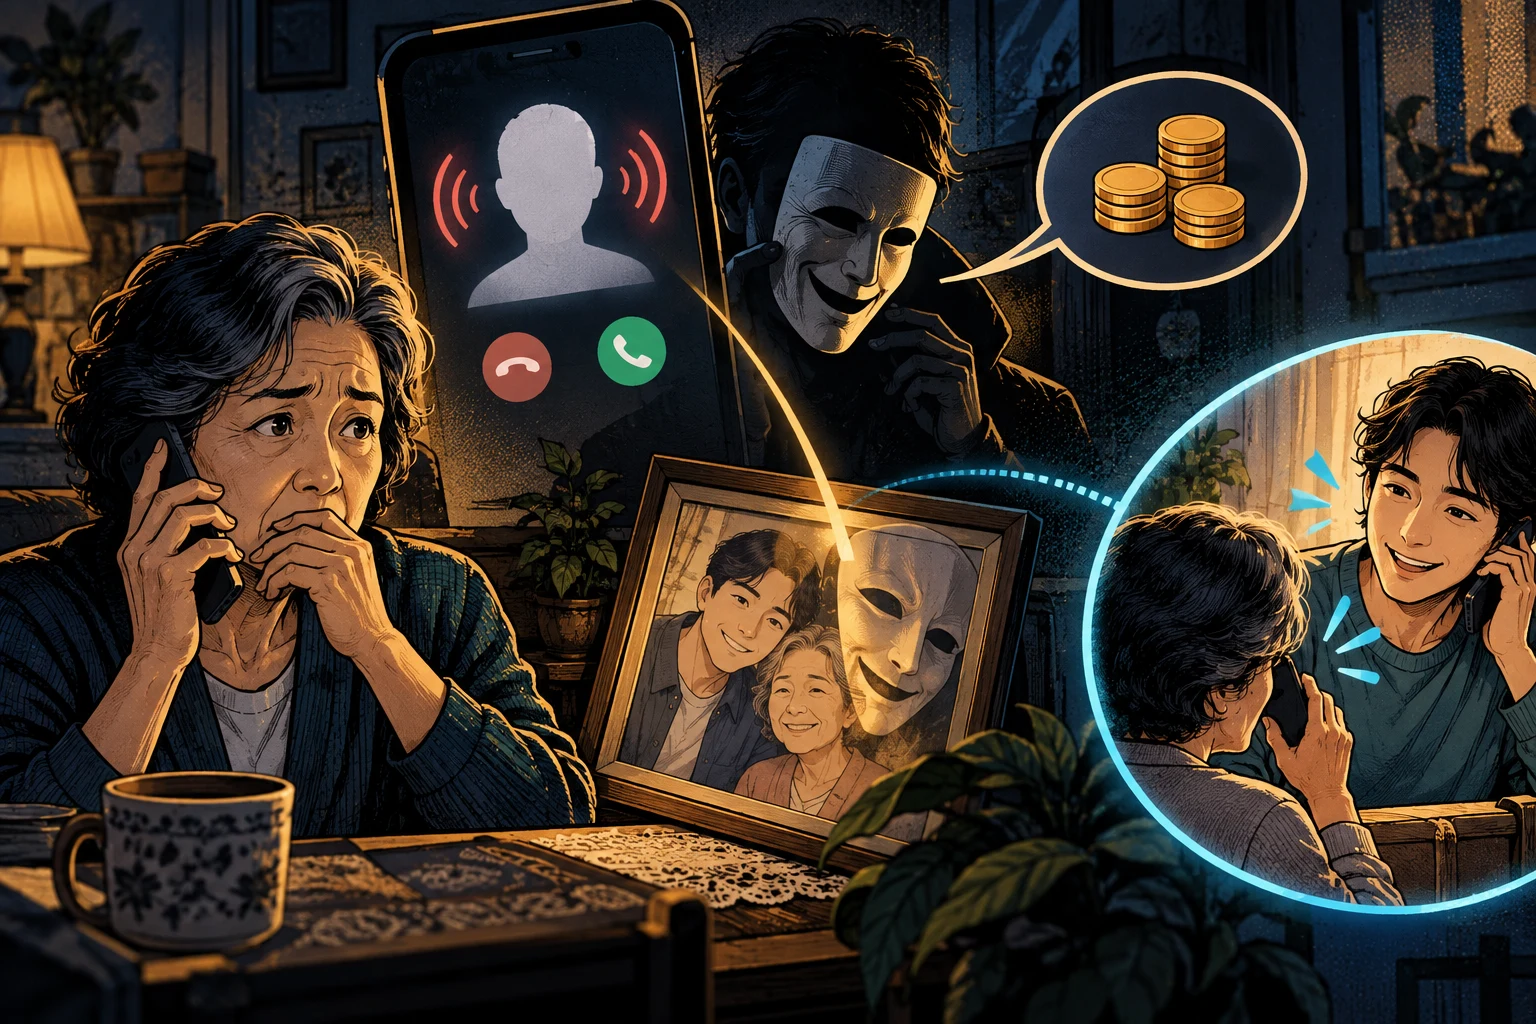
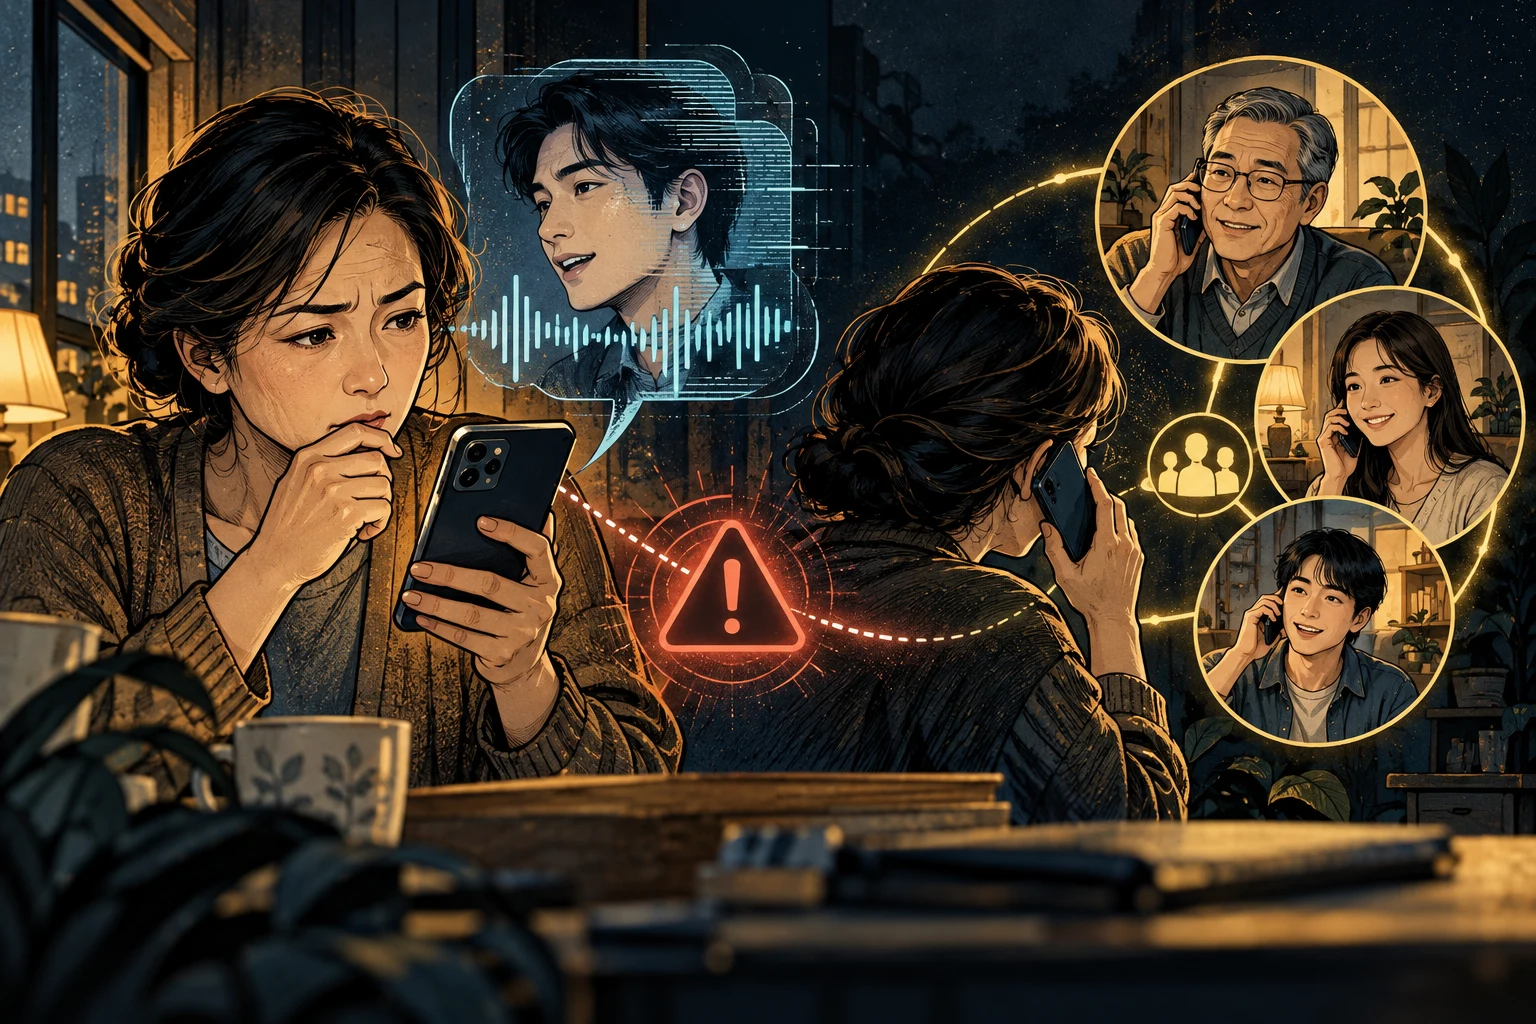
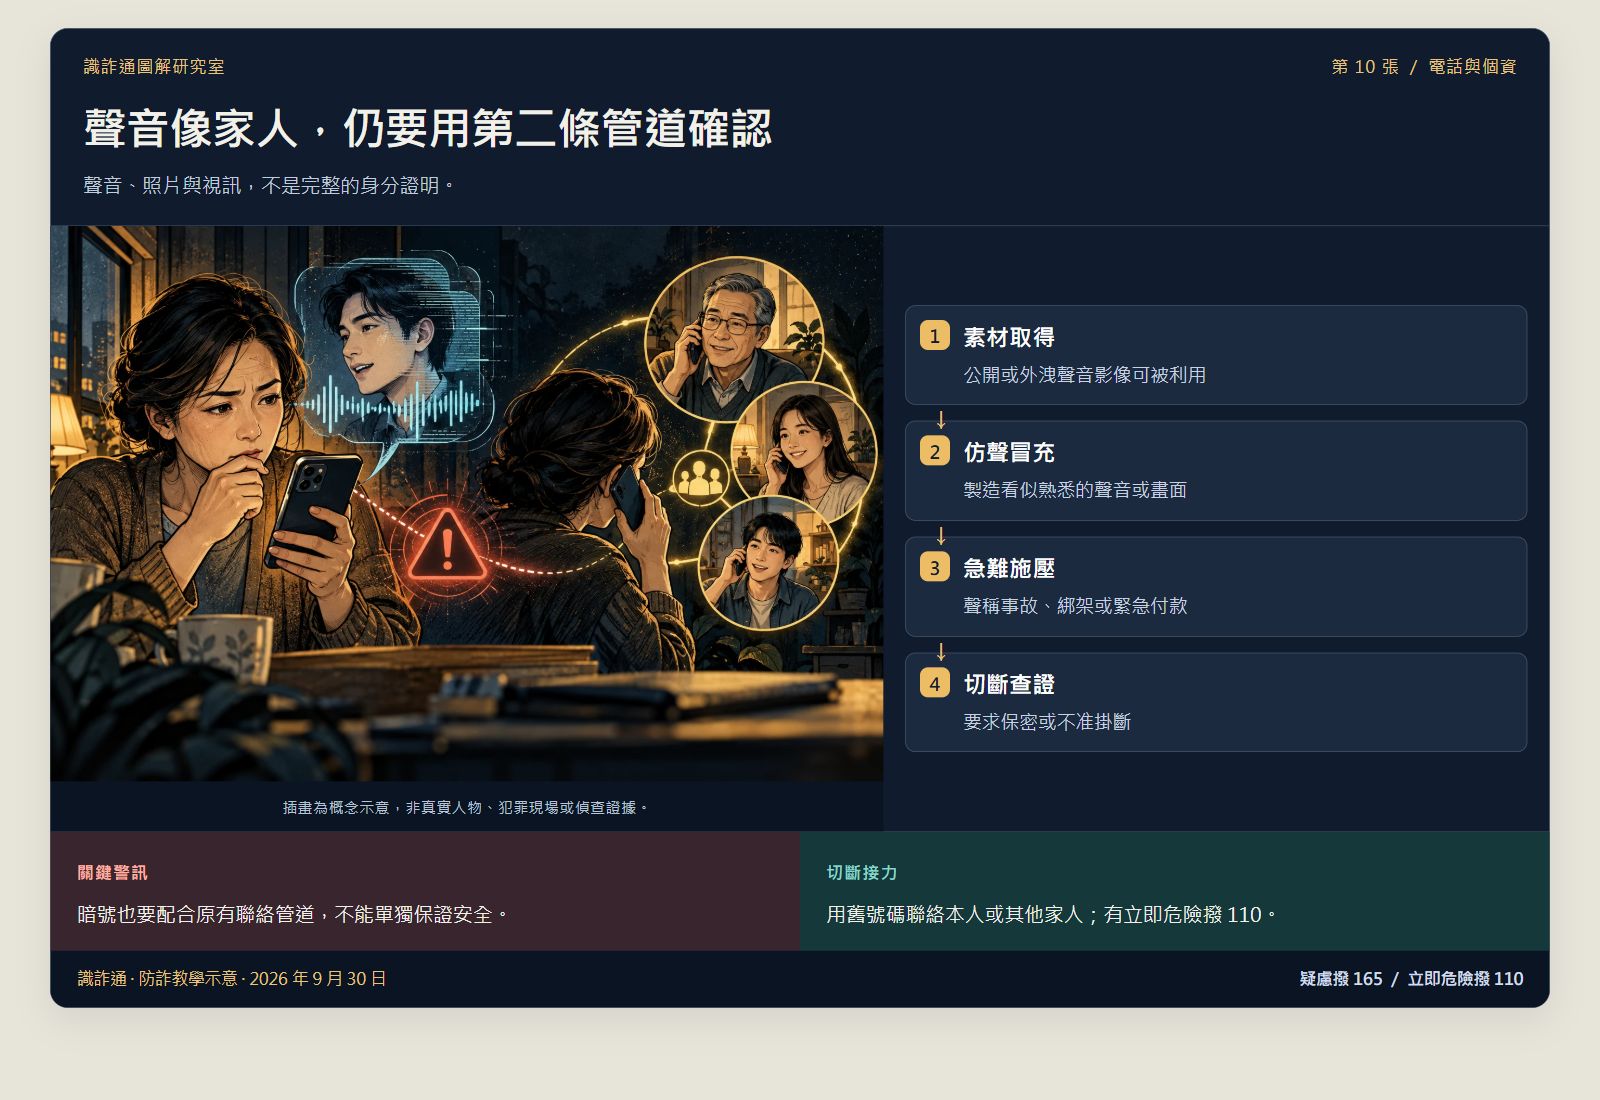
A familiar voice still needs a second channel
Voice, photos and video are not complete proof of identity.
Conceptual illustration, not real people, a crime scene or investigative evidence.
1
Obtaining material
Public or leaked recordings and images can be misused.
2
Imitating a person
A familiar-looking image or voice is fabricated.
3
Emergency pressure
An accident, kidnapping or urgent payment is claimed.
4
Blocking checks
They demand secrecy or tell you not to hang up.
Warning signs
A family code word should be combined with known contact channels. It cannot guarantee safety alone.
Protective action
Use the old number to reach the person or another family member. Call 110 for immediate danger.
Open sources and scope
Based on official advice and cases. The four stages are simplified for teaching; roles and order differ between cases and do not establish wrongdoing by any particular person or service.
Shi Zha Tong visual guides 11 / Dating and investment
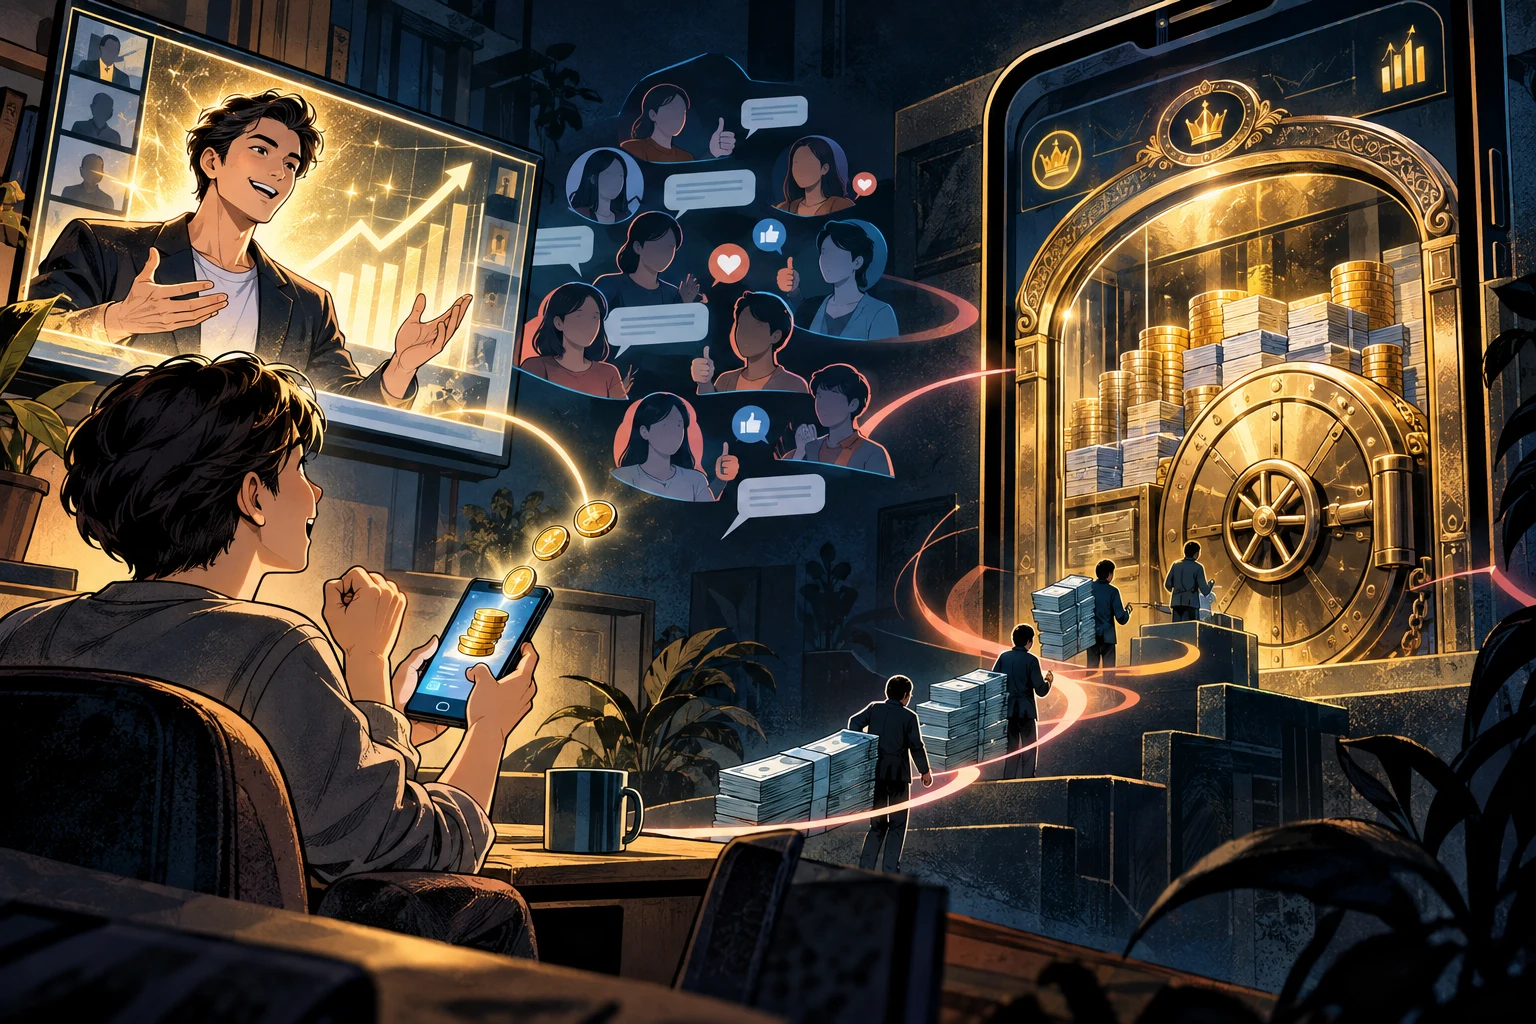
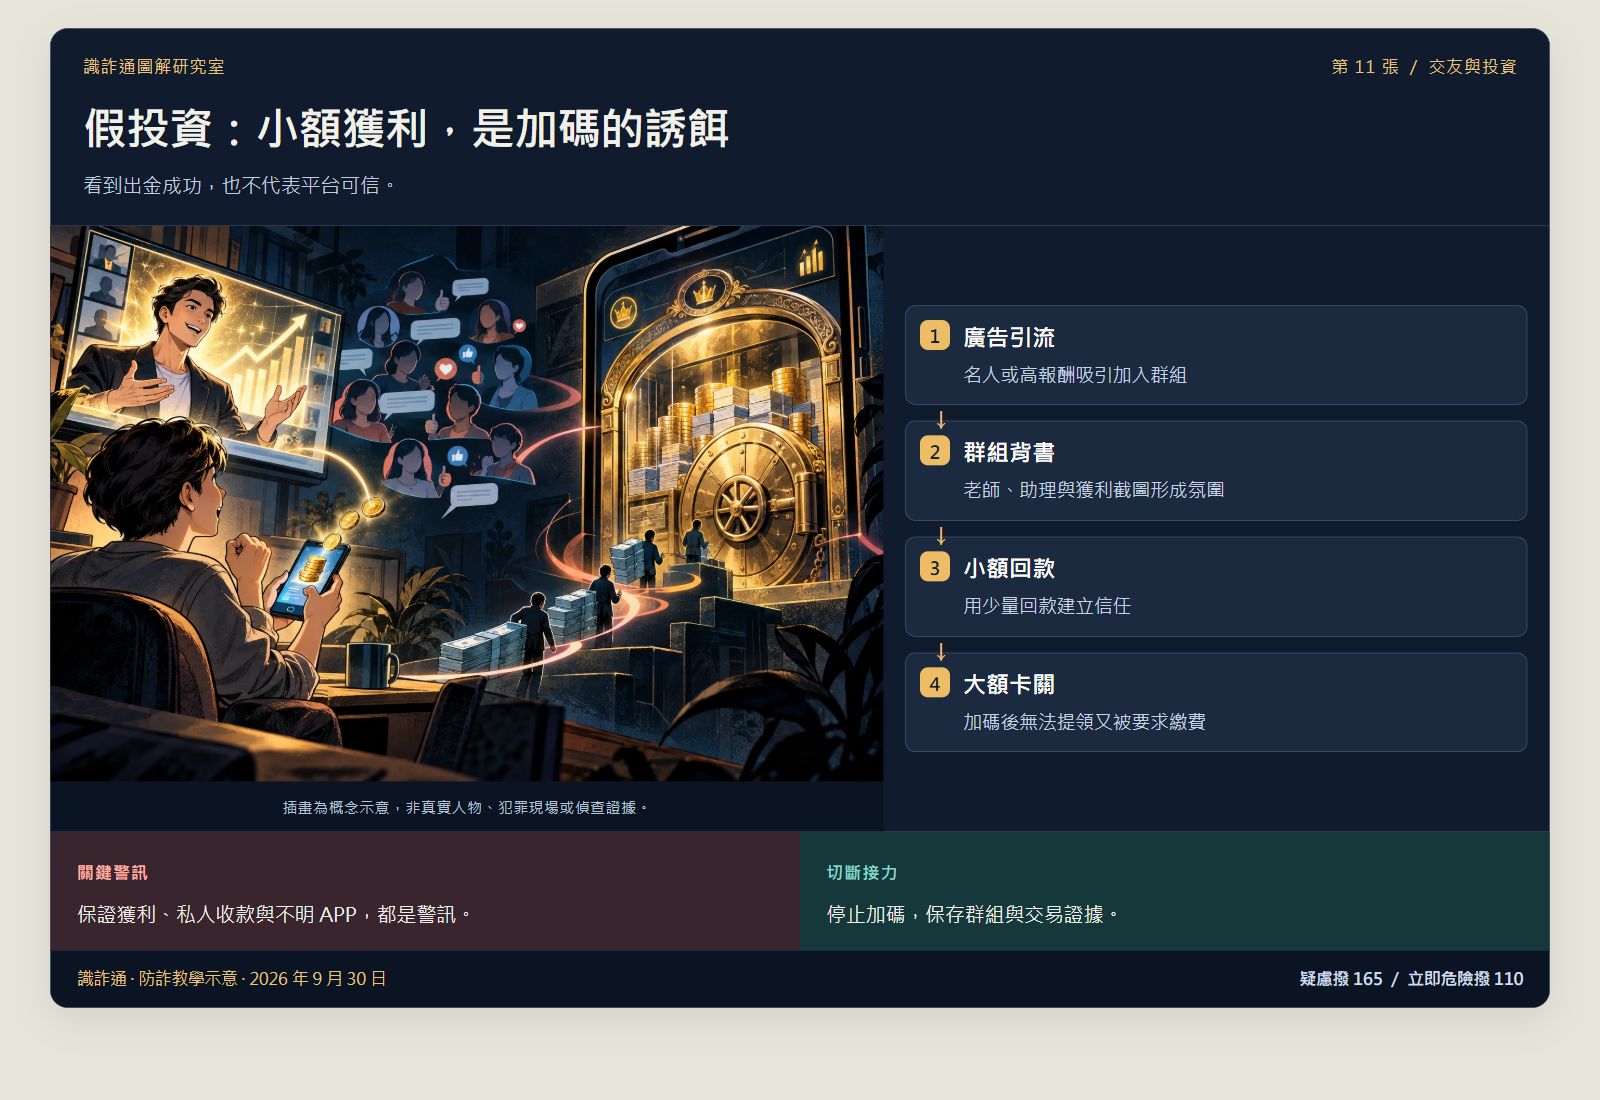
Fake investments use small gains to encourage larger deposits
A successful withdrawal does not prove a platform is trustworthy.
Conceptual illustration, not real people, a crime scene or investigative evidence.
1
Investment ads
Celebrities or high returns attract people into groups.
2
Group endorsement
A ‘teacher’, assistants and profit screenshots create confidence.
3
Small payouts
A small payout builds trust.
4
Large withdrawals blocked
After larger deposits, withdrawals fail and more fees are demanded.
Warning signs
Guaranteed profits, personal payment accounts and unfamiliar apps are warning signs.
Protective action
Stop adding money. Save group messages and transaction evidence.
Open sources and scope
Based on official advice and cases. The four stages are simplified for teaching; roles and order differ between cases and do not establish wrongdoing by any particular person or service.
Shi Zha Tong visual guides 12 / Dating and investment
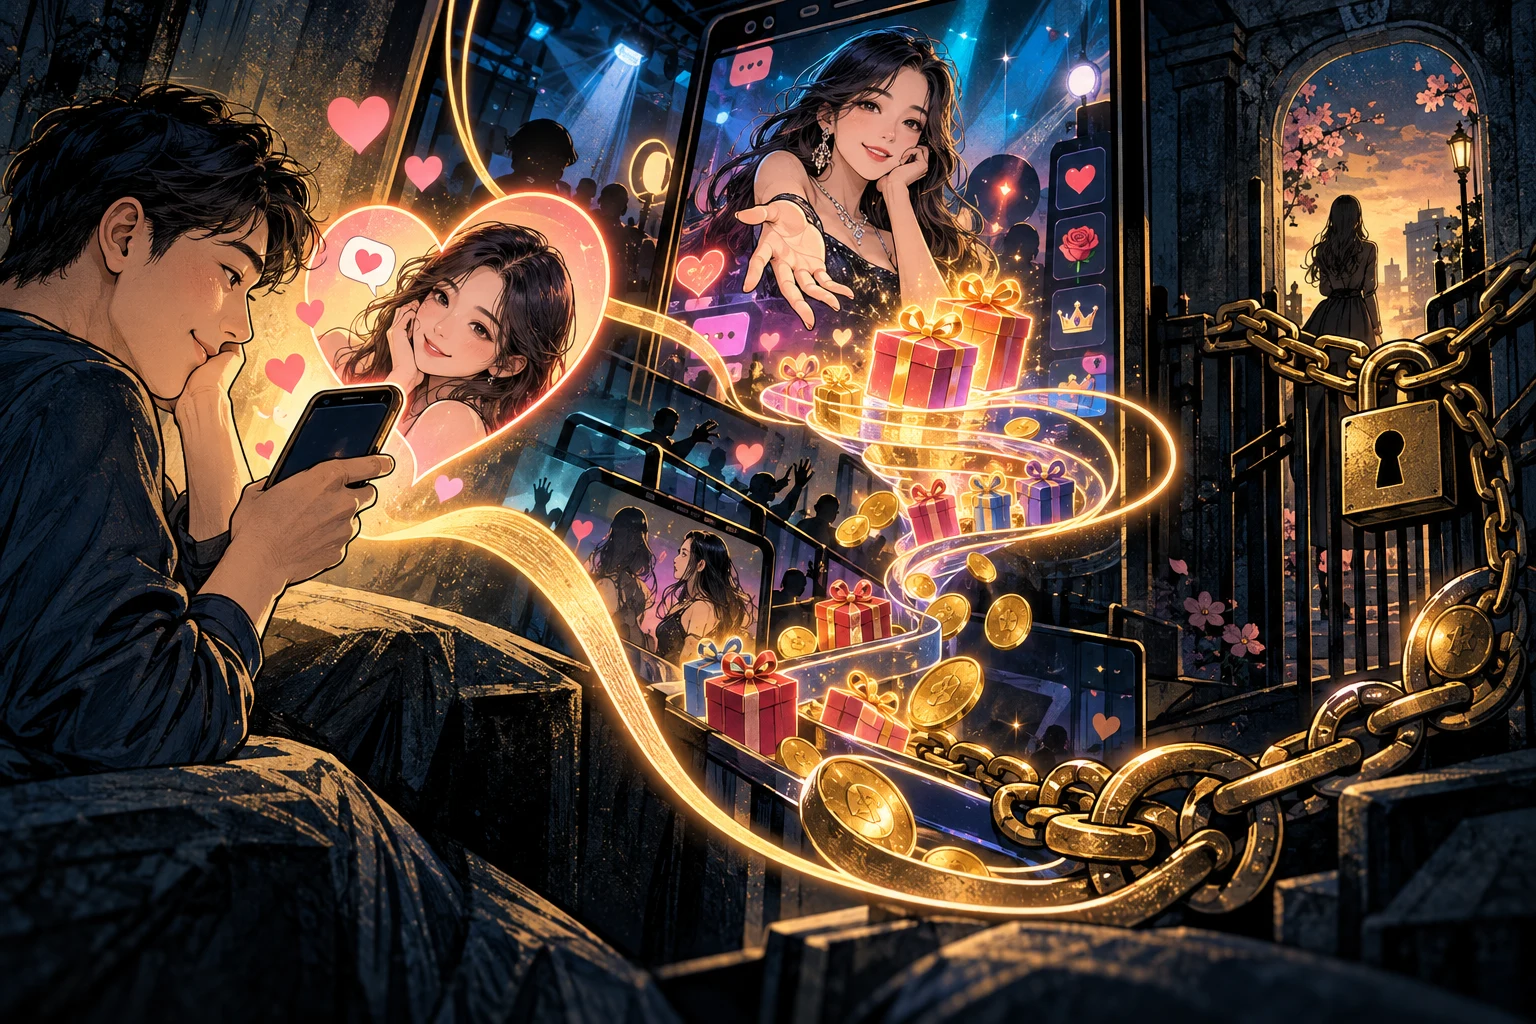
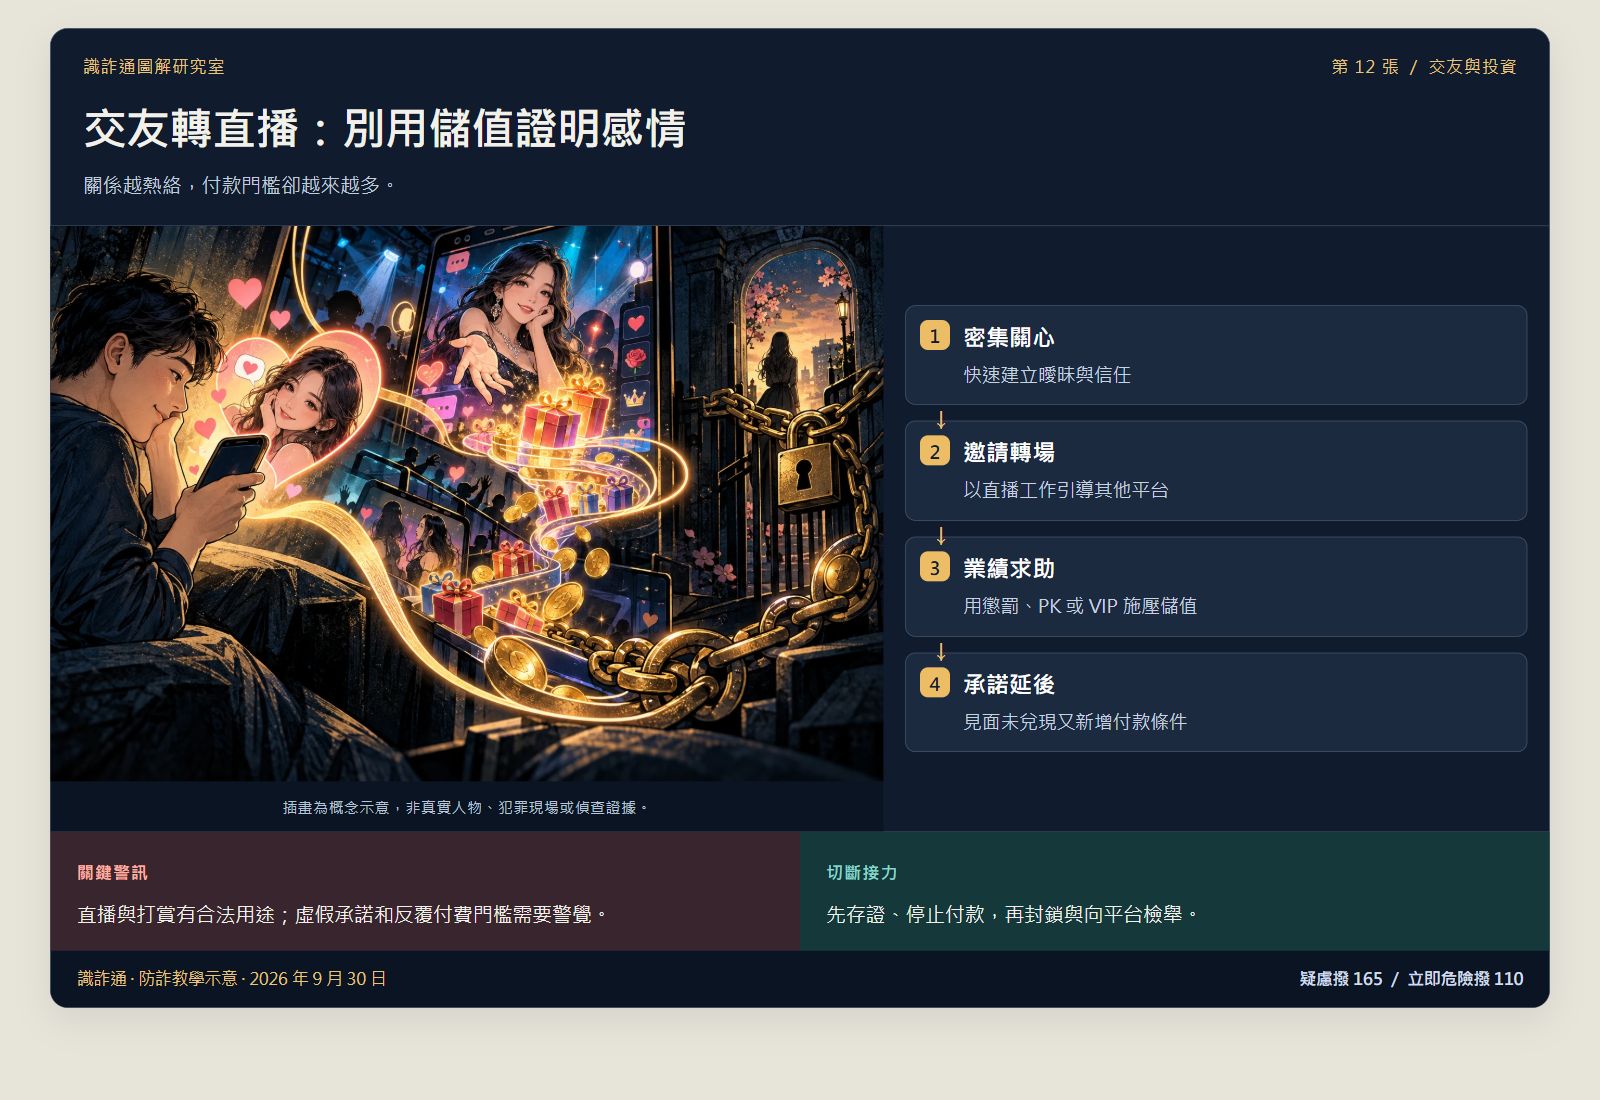
Dating to livestreaming: money does not prove affection
As the relationship grows, more payment conditions appear.
Conceptual illustration, not real people, a crime scene or investigative evidence.
1
Intense attention
Romantic interest and trust are built quickly.
2
Moving platforms
Livestreaming work is used to invite you to another platform.
3
Performance pressure
Punishment stories, competitions or VIP access pressure you to top up.
4
Delayed promises
Meetings do not happen and new payment conditions appear.
Warning signs
Livestreaming and tipping can be legitimate. False promises and repeated payment conditions deserve caution.
Protective action
Save evidence, stop paying, then block the person and report them to the platform.
Open sources and scope
Based on official advice and cases. The four stages are simplified for teaching; roles and order differ between cases and do not establish wrongdoing by any particular person or service.
Shi Zha Tong visual guides 13 / Dating and investment
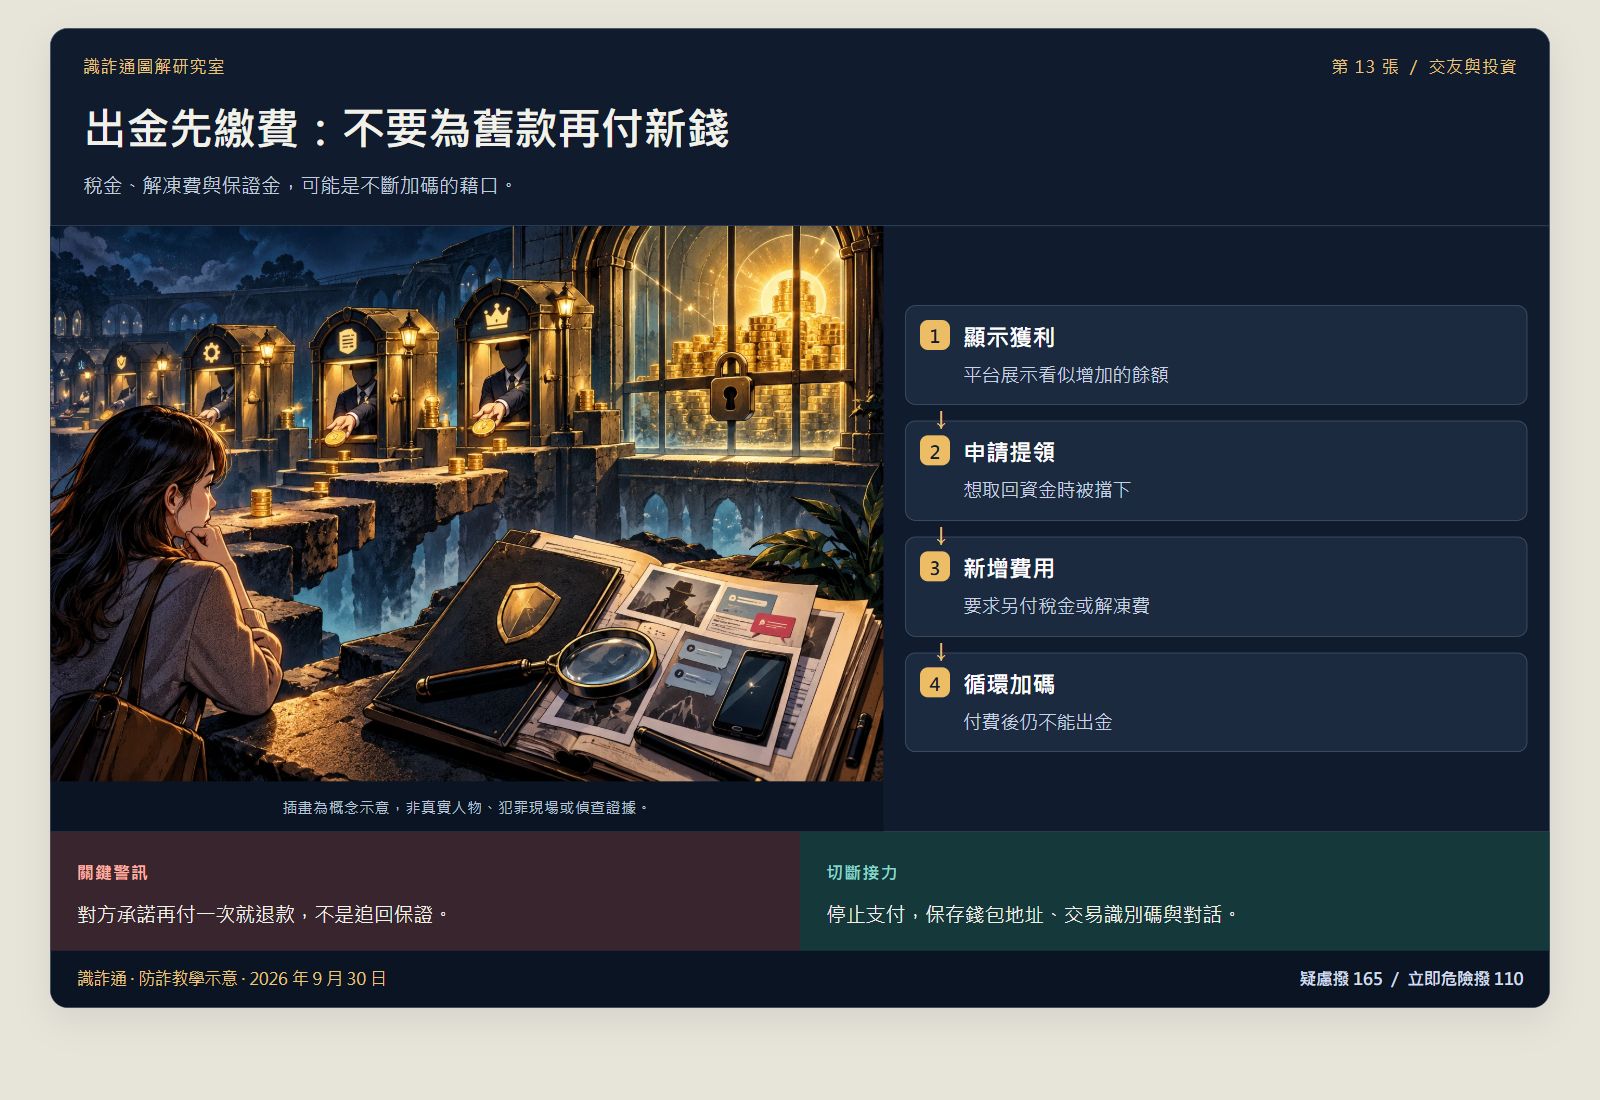
Withdrawal fees: do not pay new money to recover old money
Taxes, unlocking fees and deposits can become excuses for repeated payments.
Conceptual illustration, not real people, a crime scene or investigative evidence.
1
Apparent profits
The platform displays a rising balance.
2
Requesting a withdrawal
Your attempt to retrieve funds is blocked.
3
New charges
Additional tax or unlocking fees are demanded.
4
Repeated payments
Even after paying, you still cannot withdraw.
Warning signs
A promise of a refund after one more payment is not a recovery guarantee.
Protective action
Stop paying. Save wallet addresses, transaction IDs and conversations.
Open sources and scope
Based on official advice and cases. The four stages are simplified for teaching; roles and order differ between cases and do not establish wrongdoing by any particular person or service.
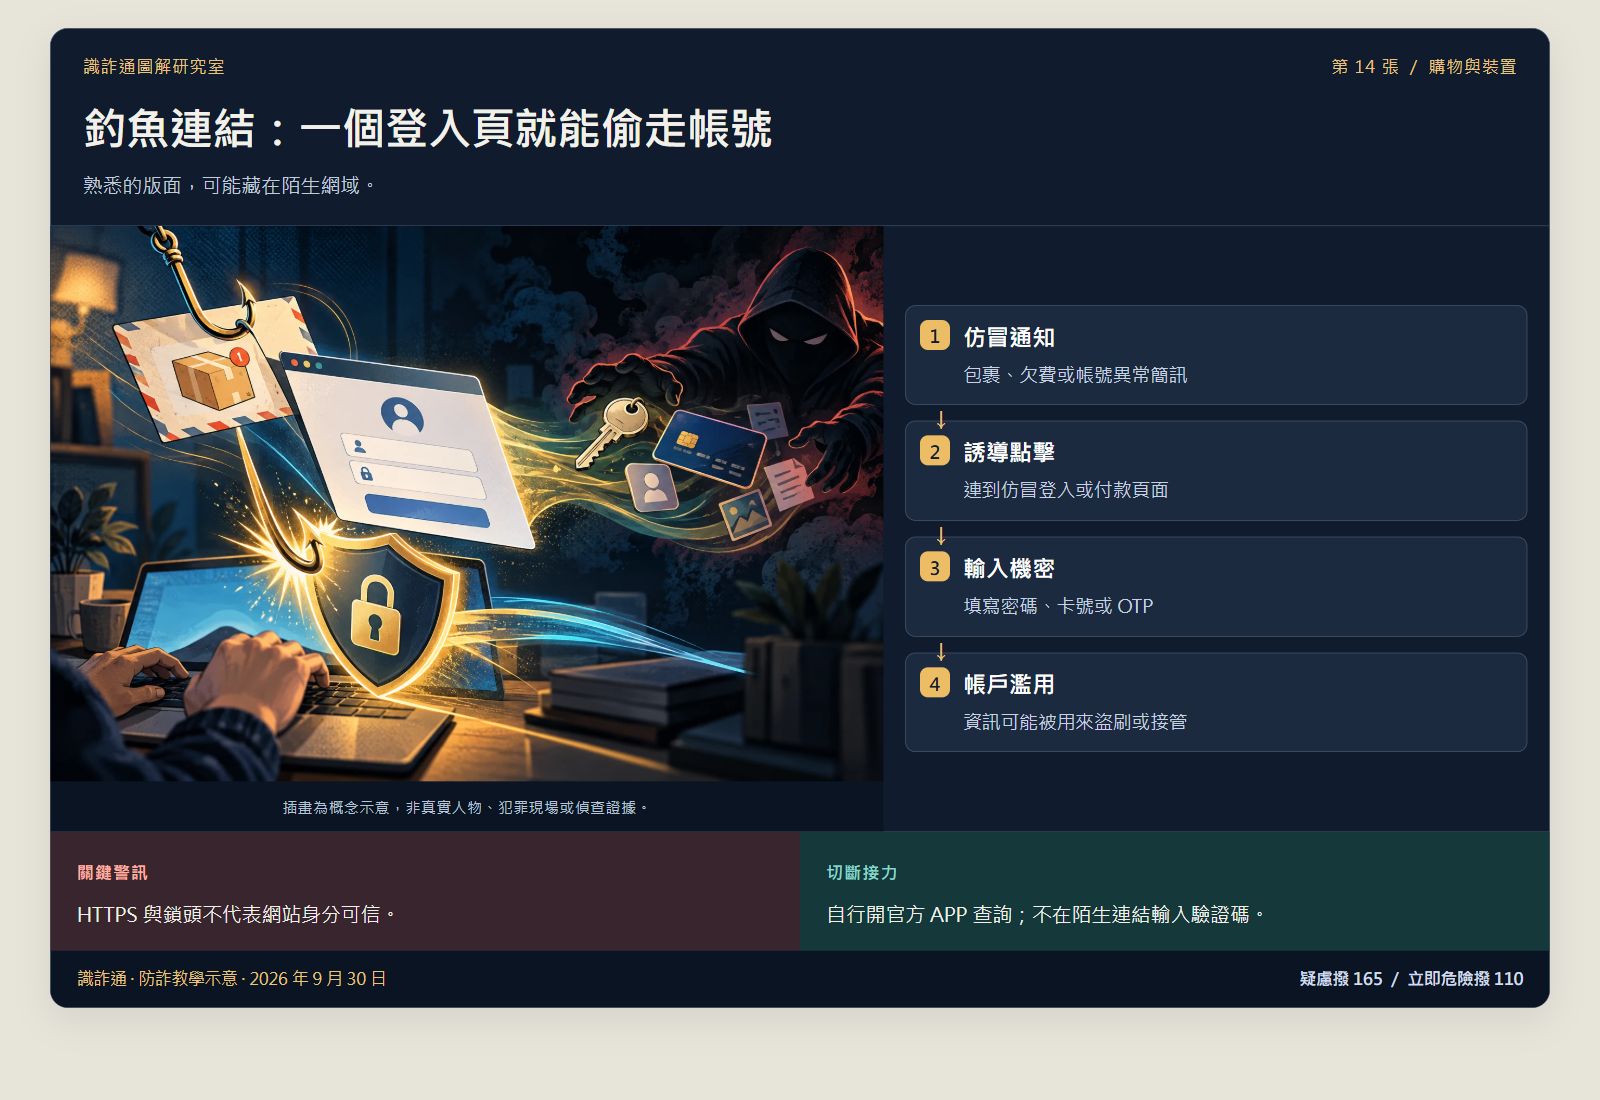
Shi Zha Tong visual guides 14 / Shopping and devices
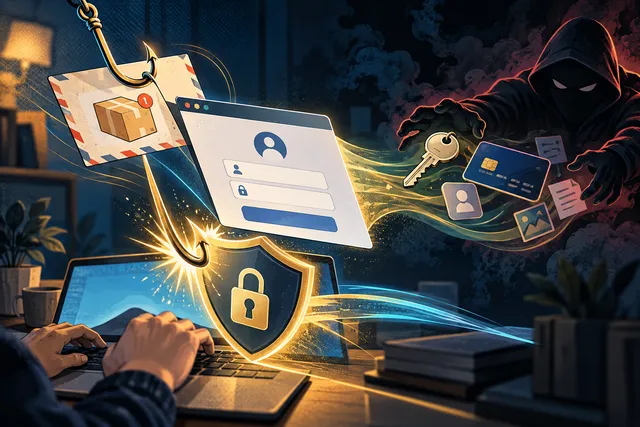
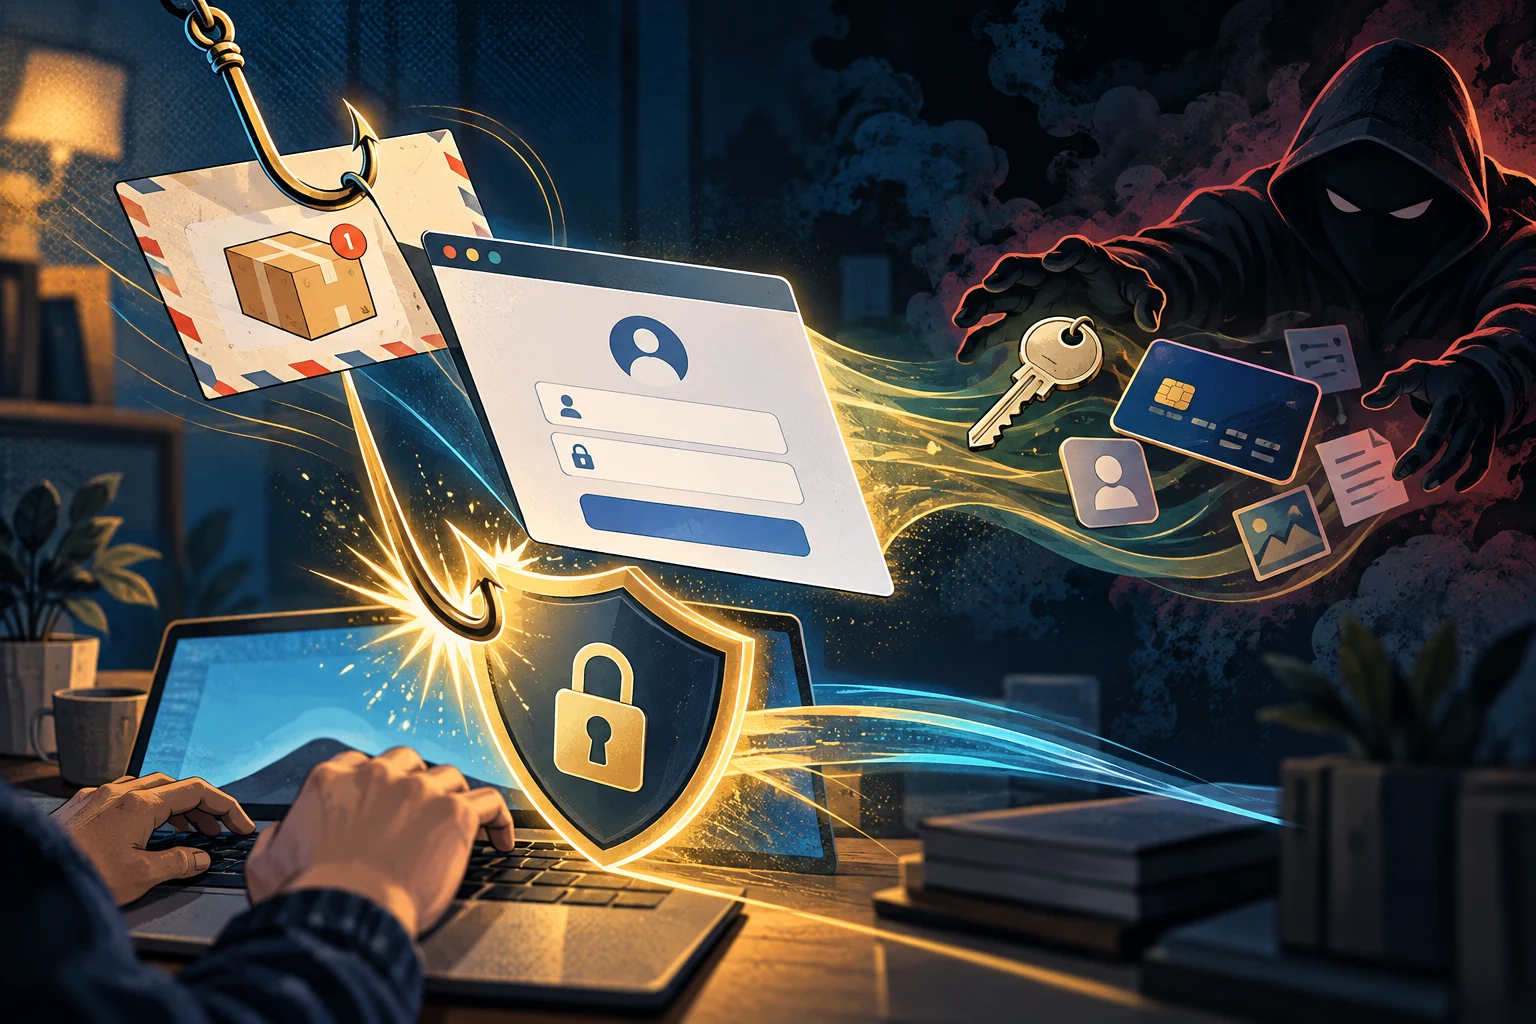
Phishing links: a login page can steal your account
A familiar design may be hosted on an unfamiliar domain.
Conceptual illustration, not real people, a crime scene or investigative evidence.
1
Fake notification
A message mentions a parcel, unpaid bill or account problem.
2
Clicking a link
It leads to a counterfeit login or payment page.
3
Entering secrets
Passwords, card numbers or one-time passwords are entered.
4
Account misuse
The information may be used for unauthorised payments or account takeover.
Warning signs
HTTPS and a padlock do not establish a website’s identity.
Protective action
Open the official app yourself. Do not enter verification codes through unfamiliar links.
Open sources and scope
Based on official advice and cases. The four stages are simplified for teaching; roles and order differ between cases and do not establish wrongdoing by any particular person or service.
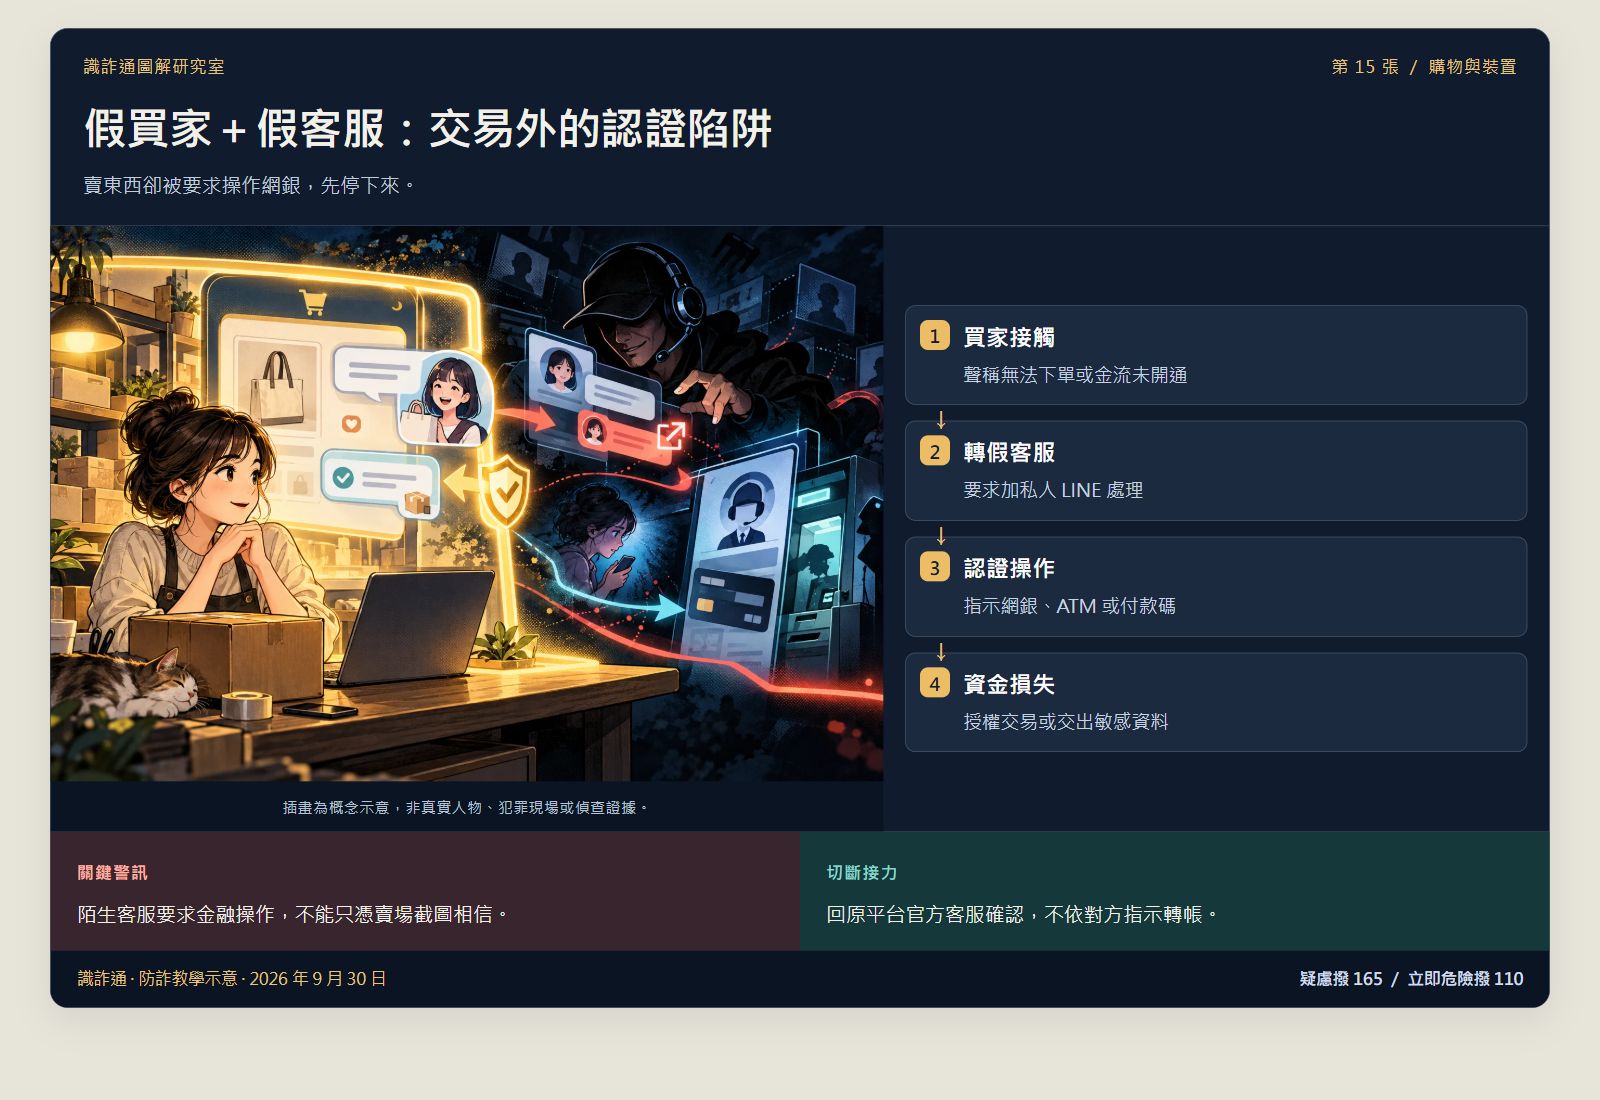
Shi Zha Tong visual guides 15 / Shopping and devices
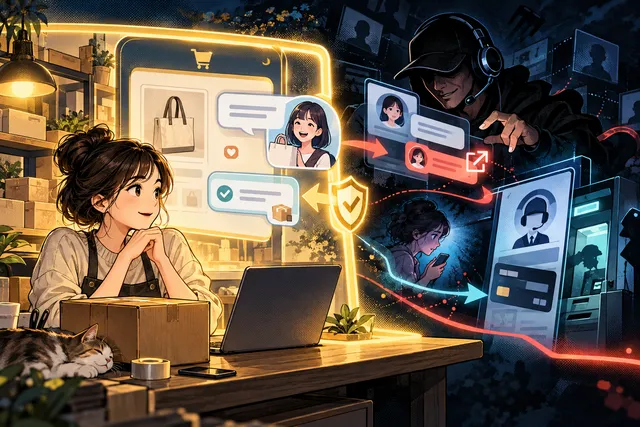
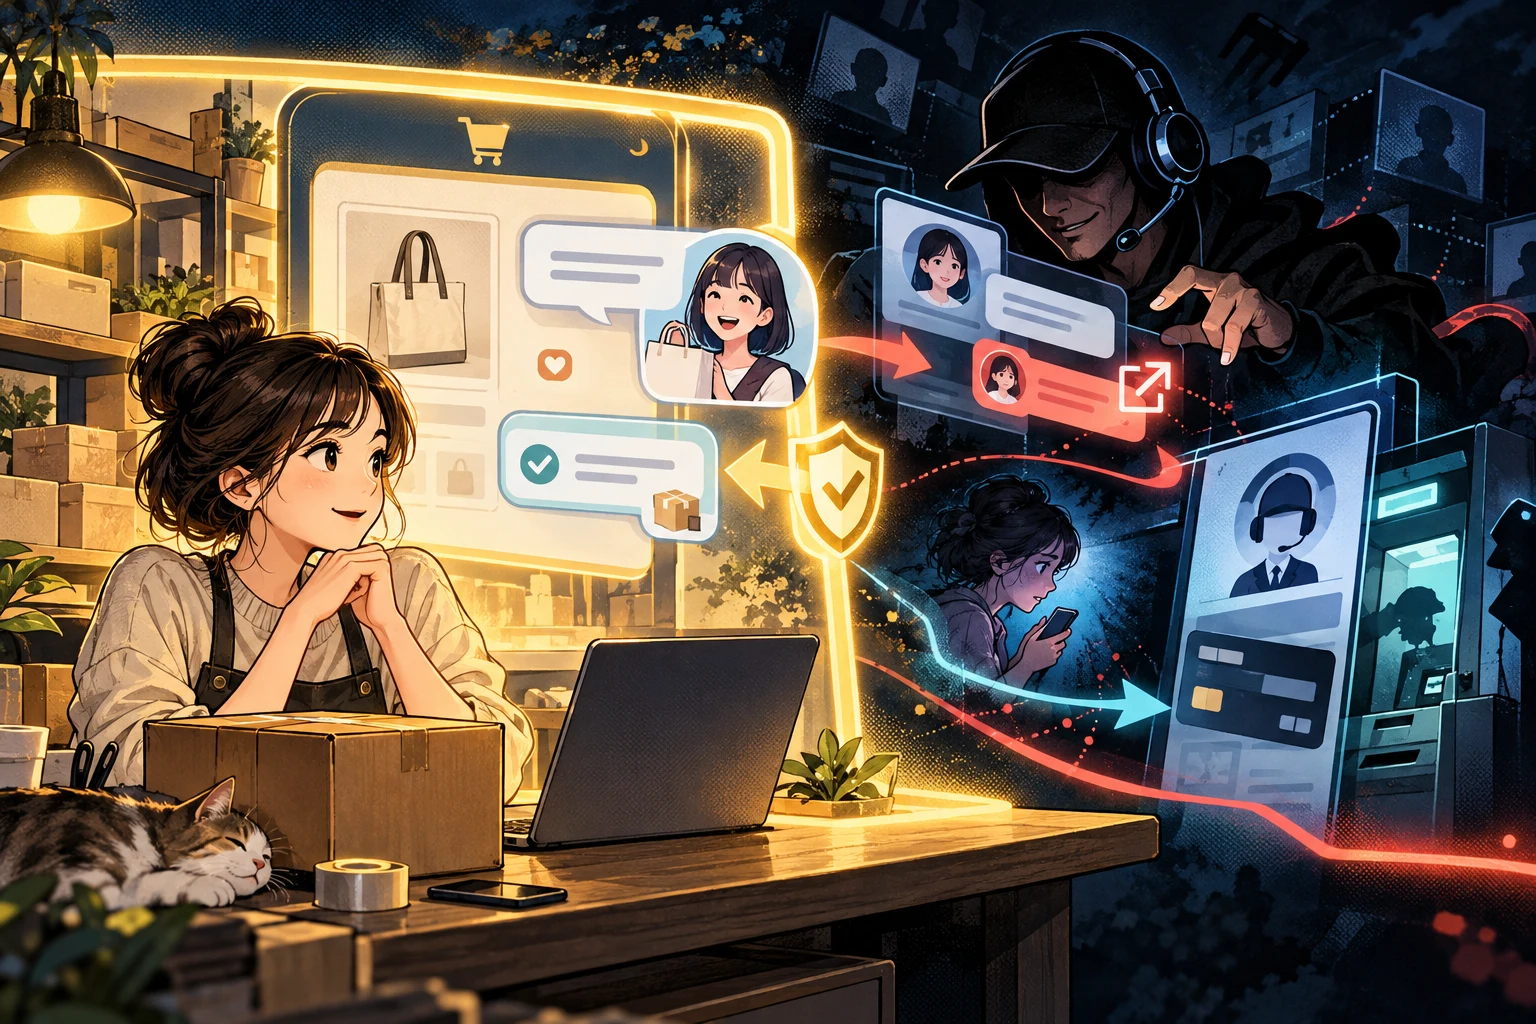
Fake buyer and fake support: verification outside the platform
If selling something leads to online-banking instructions, stop.
Conceptual illustration, not real people, a crime scene or investigative evidence.
1
Buyer contact
A buyer claims an order cannot be placed or payments are not enabled.
2
Fake support
You are told to add a private LINE account for help.
3
‘Verification’ instructions
They give instructions for online banking, an ATM or a payment code.
4
Financial loss
You authorise a transaction or disclose sensitive information.
Warning signs
A store screenshot is not enough to trust a stranger requesting financial actions.
Protective action
Check with official support on the original platform. Do not transfer money on the caller’s instructions.
Open sources and scope
Based on official advice and cases. The four stages are simplified for teaching; roles and order differ between cases and do not establish wrongdoing by any particular person or service.
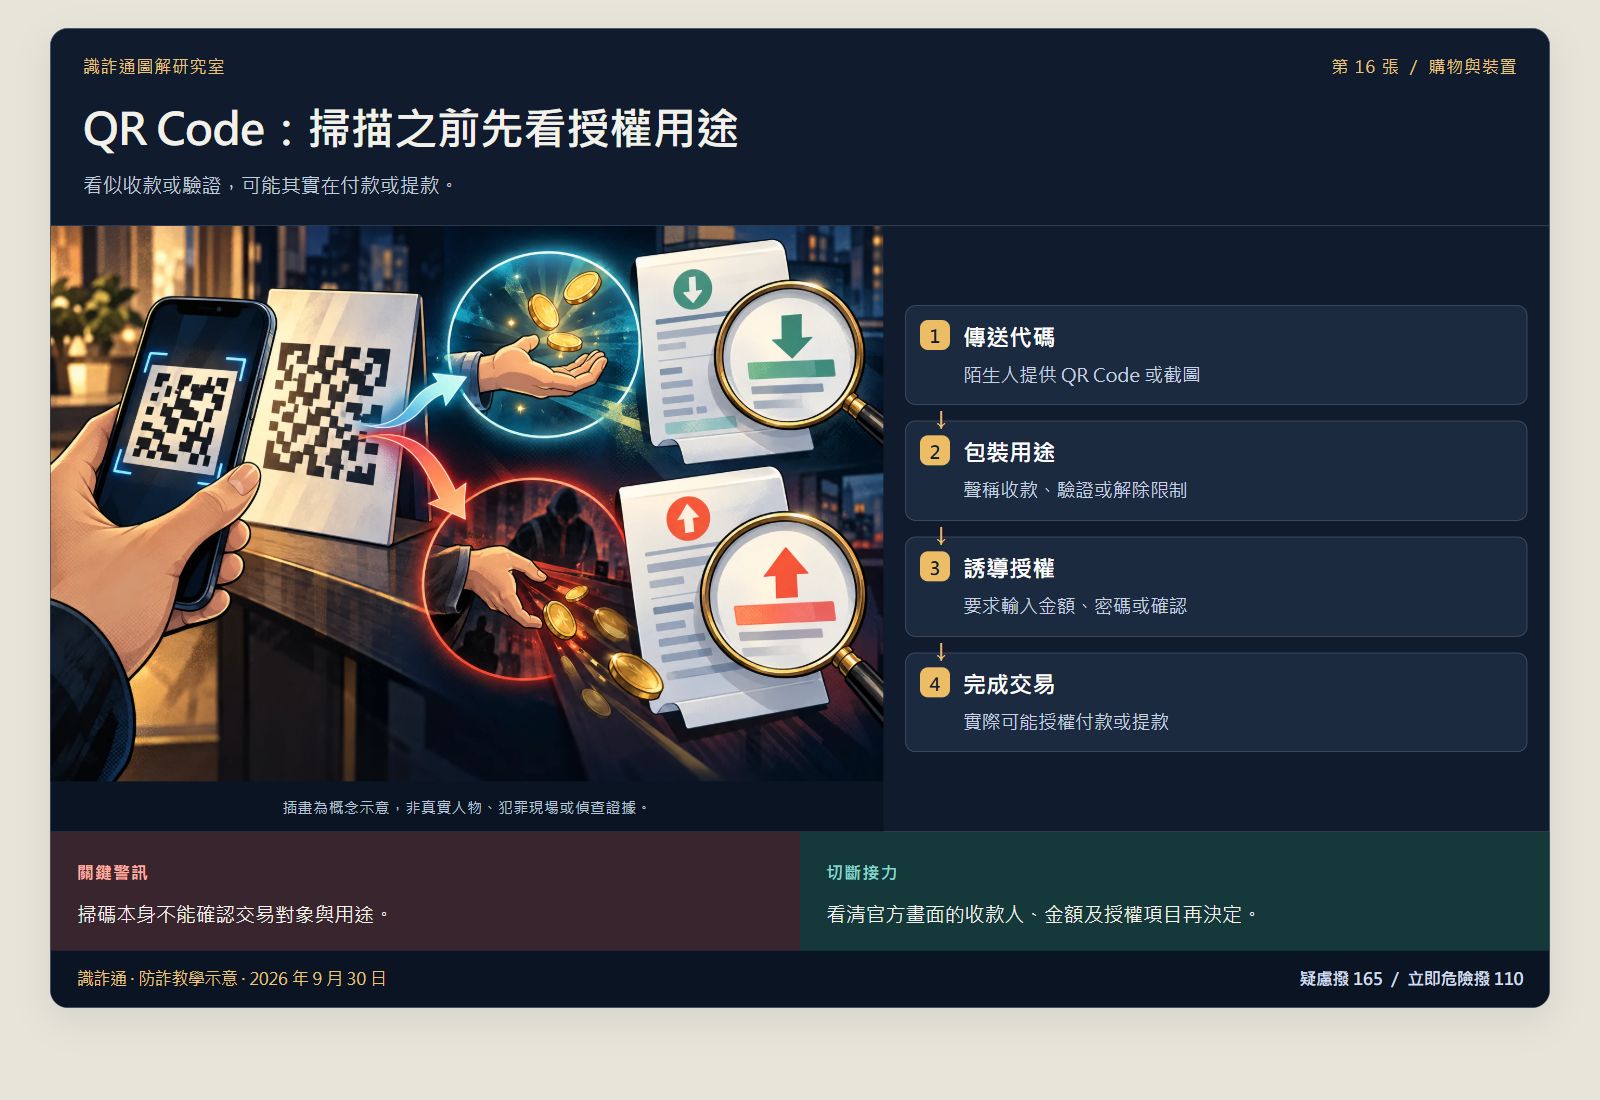
Shi Zha Tong visual guides 16 / Shopping and devices
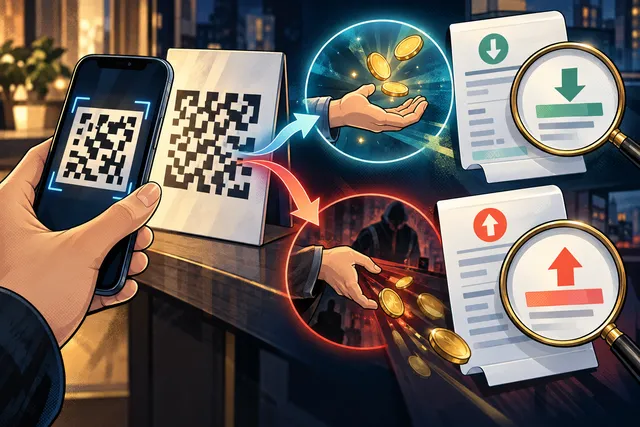
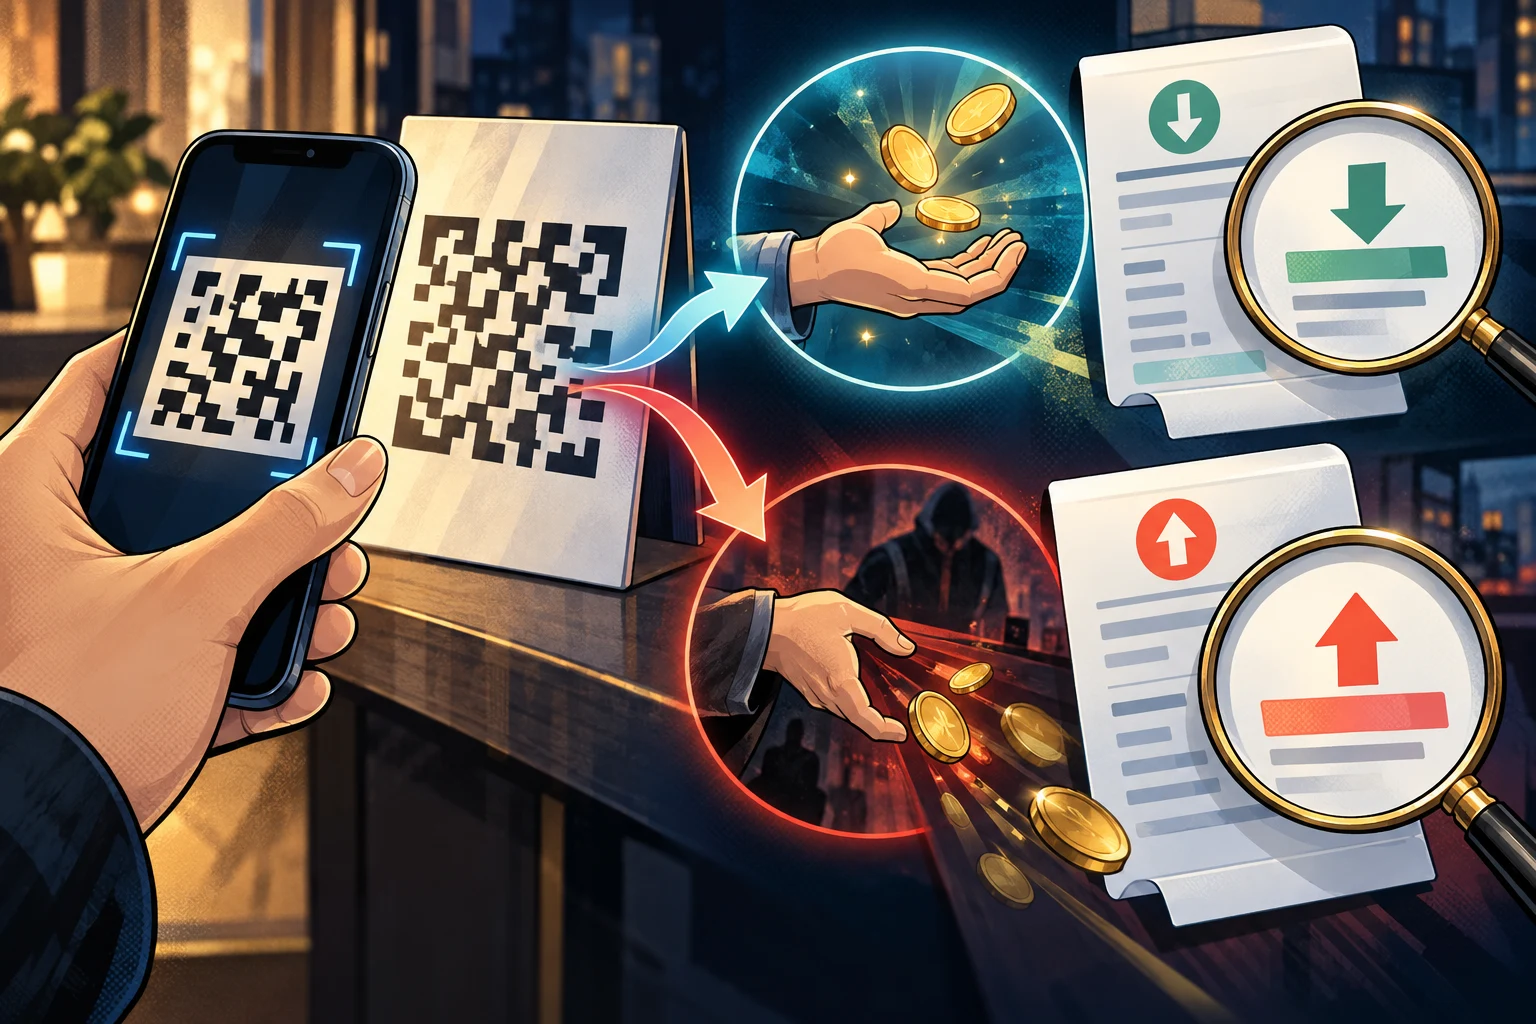
QR codes: check what you are authorising
An apparent payment receipt or check may actually authorise a payment or withdrawal.
Conceptual illustration, not real people, a crime scene or investigative evidence.
1
Receiving a code
A stranger sends a QR code or screenshot.
2
A false purpose
They claim it receives money, verifies identity or removes a restriction.
3
Authorising action
You are asked to enter an amount, password or confirmation.
4
Completing a transaction
The action may actually authorise a payment or cash withdrawal.
Warning signs
Scanning a code does not verify the other party or the purpose.
Protective action
Read the recipient, amount and authorisation on the official screen before deciding.
Open sources and scope
Based on official advice and cases. The four stages are simplified for teaching; roles and order differ between cases and do not establish wrongdoing by any particular person or service.
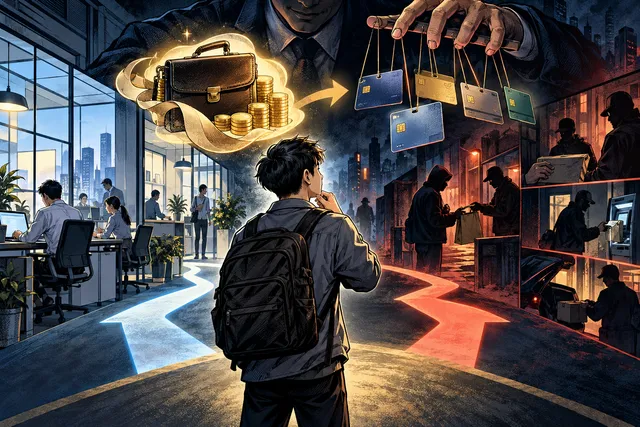
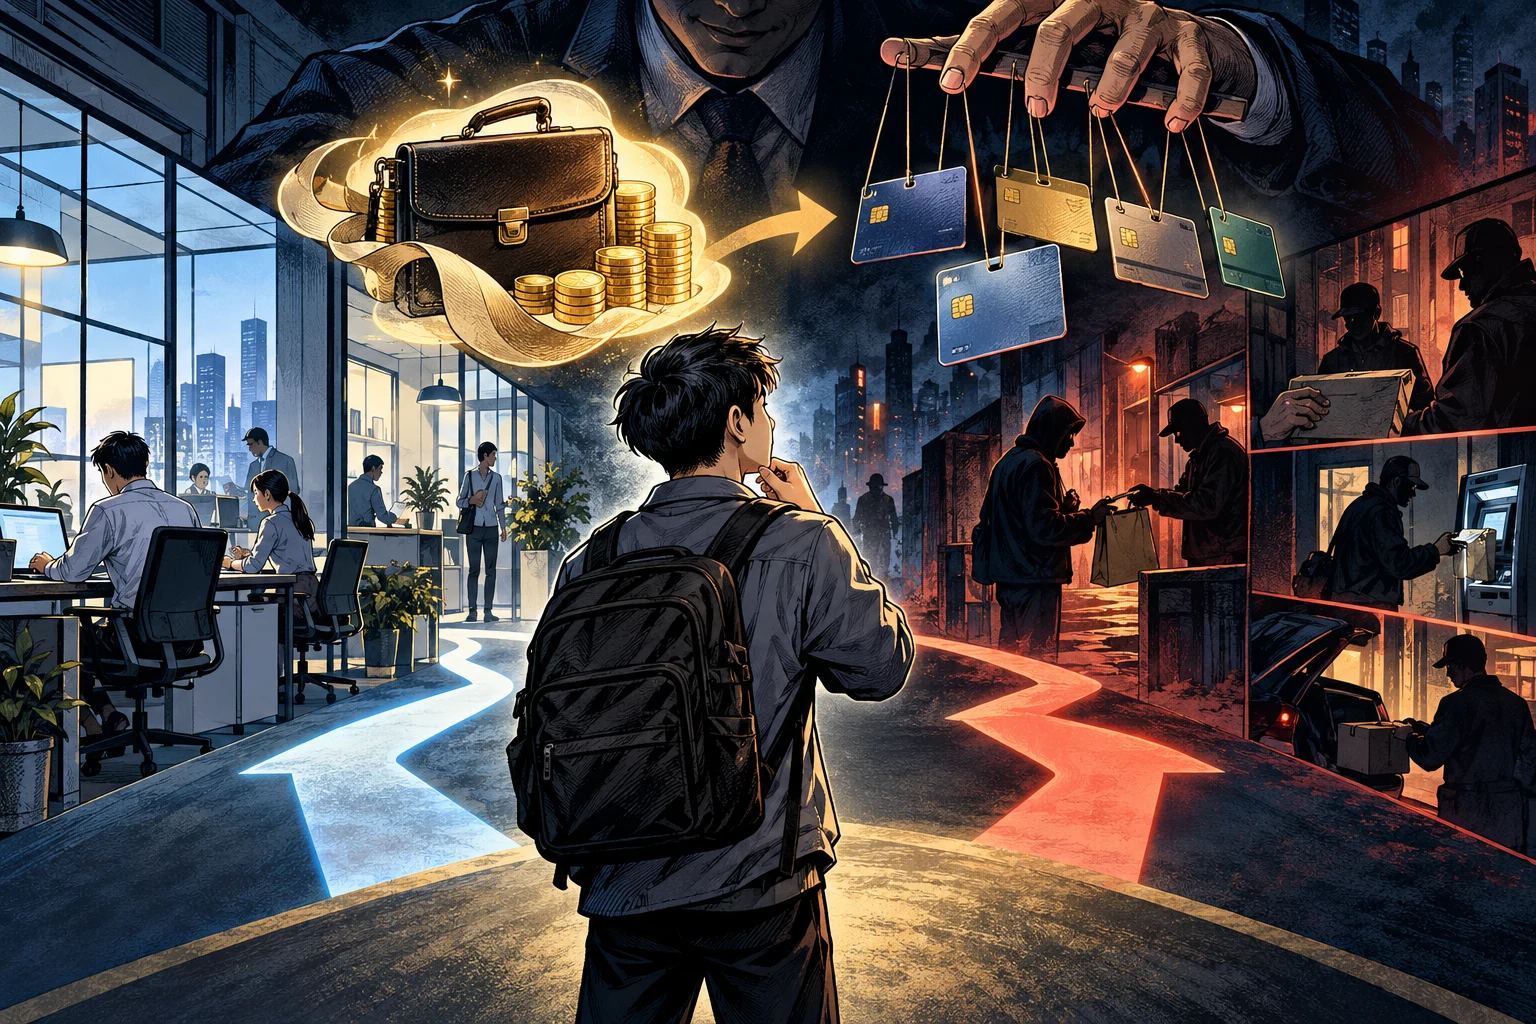
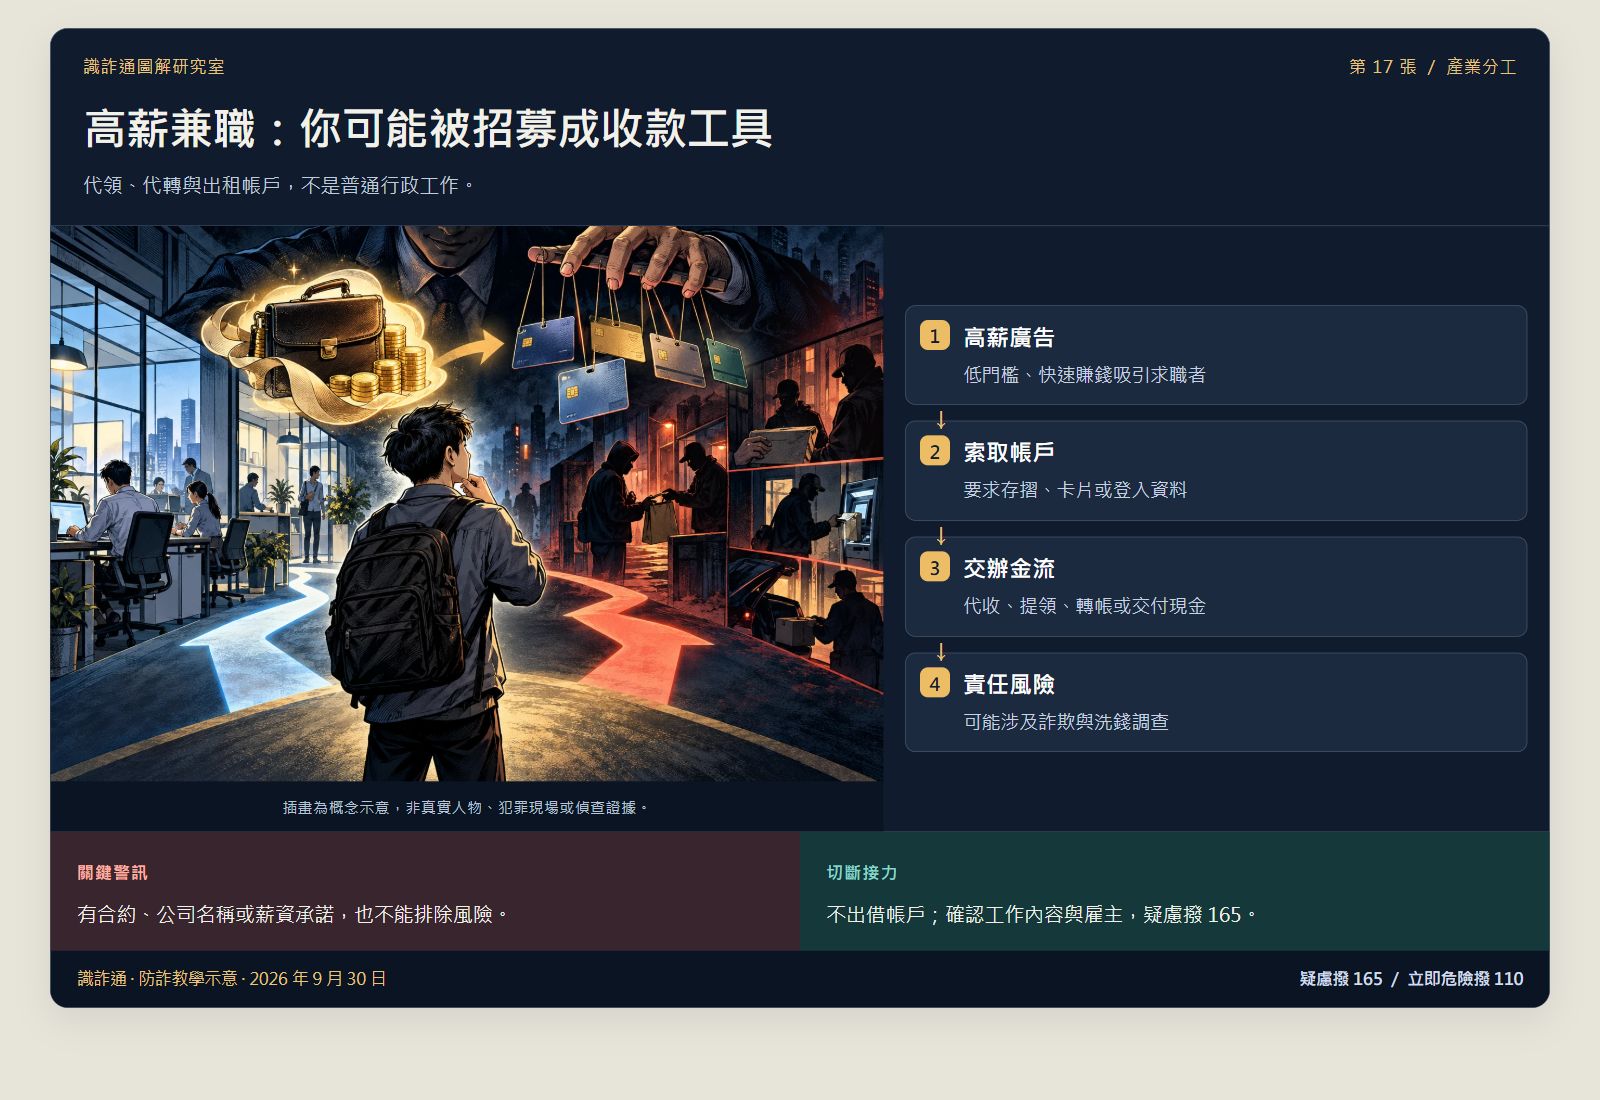
High-paying side jobs can recruit you to handle scam money
Withdrawing, forwarding money and renting out accounts are not ordinary administrative tasks.
Conceptual illustration, not real people, a crime scene or investigative evidence.
1
An easy high-paying job
Low entry requirements and fast earnings attract applicants.
2
Requesting an account
Passbooks, cards or login details are requested.
3
Money-handling tasks
You receive, withdraw, transfer or deliver money for someone else.
4
Liability risks
You may become involved in fraud or money-laundering investigations.
Warning signs
A contract, company name or salary promise does not remove the risk.
Protective action
Do not lend accounts. Verify the employer and duties; call 165 if unsure.
Open sources and scope
Based on official advice and cases. The four stages are simplified for teaching; roles and order differ between cases and do not establish wrongdoing by any particular person or service.
Shi Zha Tong visual guides 18 / Shopping and devices
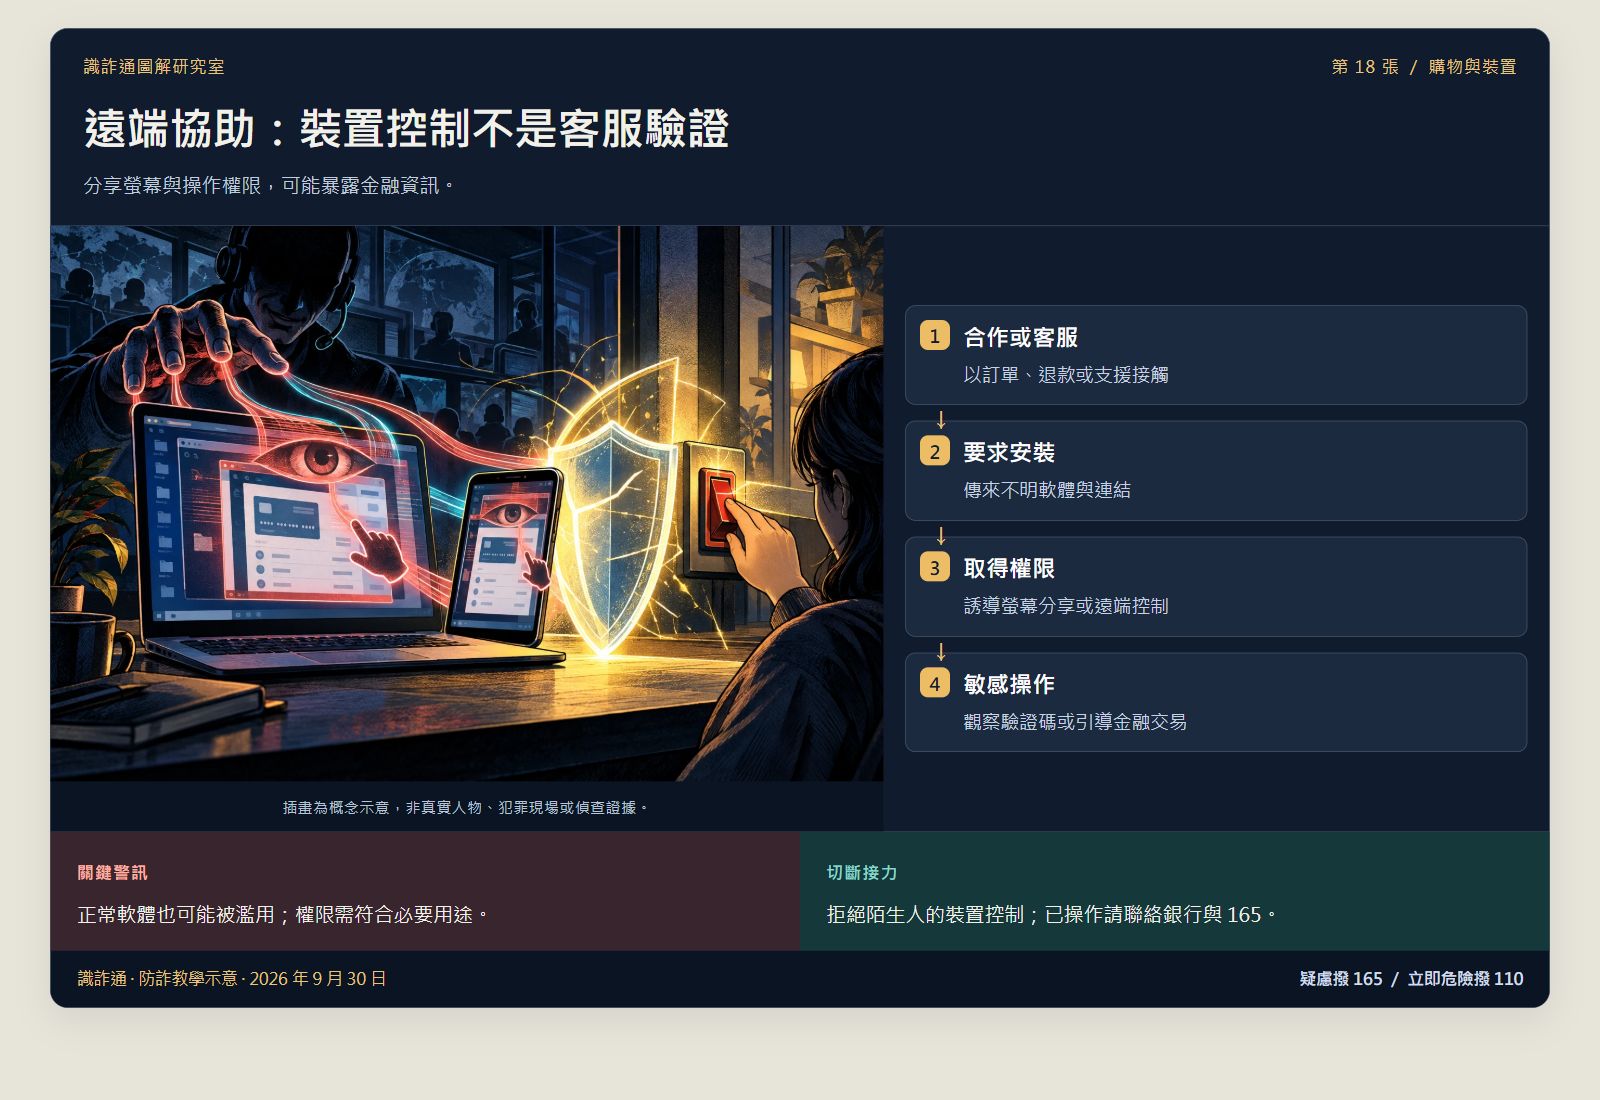
Remote assistance: device control is not customer verification
Screen sharing and control permissions can expose financial information.
Conceptual illustration, not real people, a crime scene or investigative evidence.
1
Support contact
Someone approaches you about an order, refund or support.
2
Installing software
They send unfamiliar software or links.
3
Granting access
They persuade you to share your screen or allow remote control.
4
Sensitive actions
They watch verification codes or guide financial transactions.
Warning signs
Legitimate software can be misused. Permissions should match a necessary purpose.
Protective action
Refuse device control by strangers. If you already acted, contact your bank and 165.
Open sources and scope
Based on official advice and cases. The four stages are simplified for teaching; roles and order differ between cases and do not establish wrongdoing by any particular person or service.
Shi Zha Tong visual guides 19 / Limiting loss and staying safe
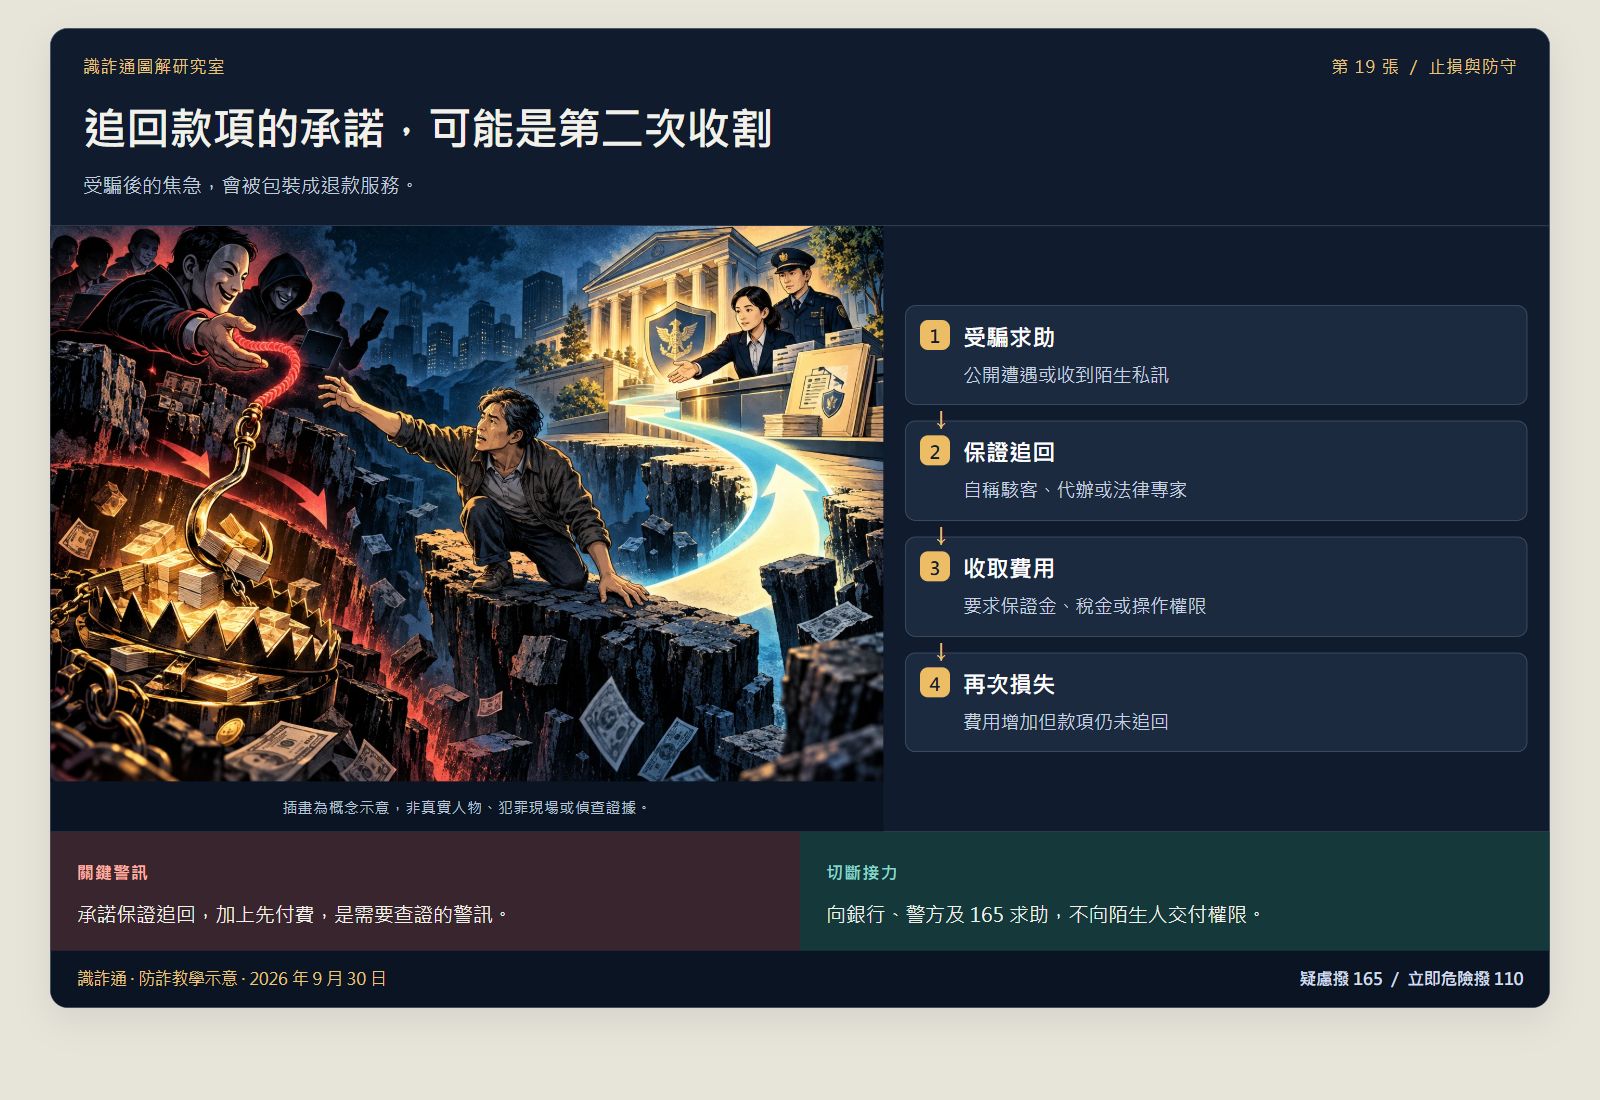
Recovery promises can lead to a second scam
Anxiety after a scam can be exploited as a supposed refund service.
Conceptual illustration, not real people, a crime scene or investigative evidence.
1
Seeking help
You share your experience or receive an unsolicited message.
2
Guaranteed recovery
Someone claims to be a hacker, recovery agent or legal expert.
3
Upfront fees
They demand a deposit, tax or access permissions.
4
Further losses
Fees grow but the money remains unrecovered.
Warning signs
Guaranteed recovery combined with upfront payment is a warning sign requiring verification.
Protective action
Ask your bank, police and 165 for help. Do not give access permissions to strangers.
Open sources and scope
Based on official advice and cases. The four stages are simplified for teaching; roles and order differ between cases and do not establish wrongdoing by any particular person or service.
Shi Zha Tong visual guides 20 / Limiting loss and staying safe
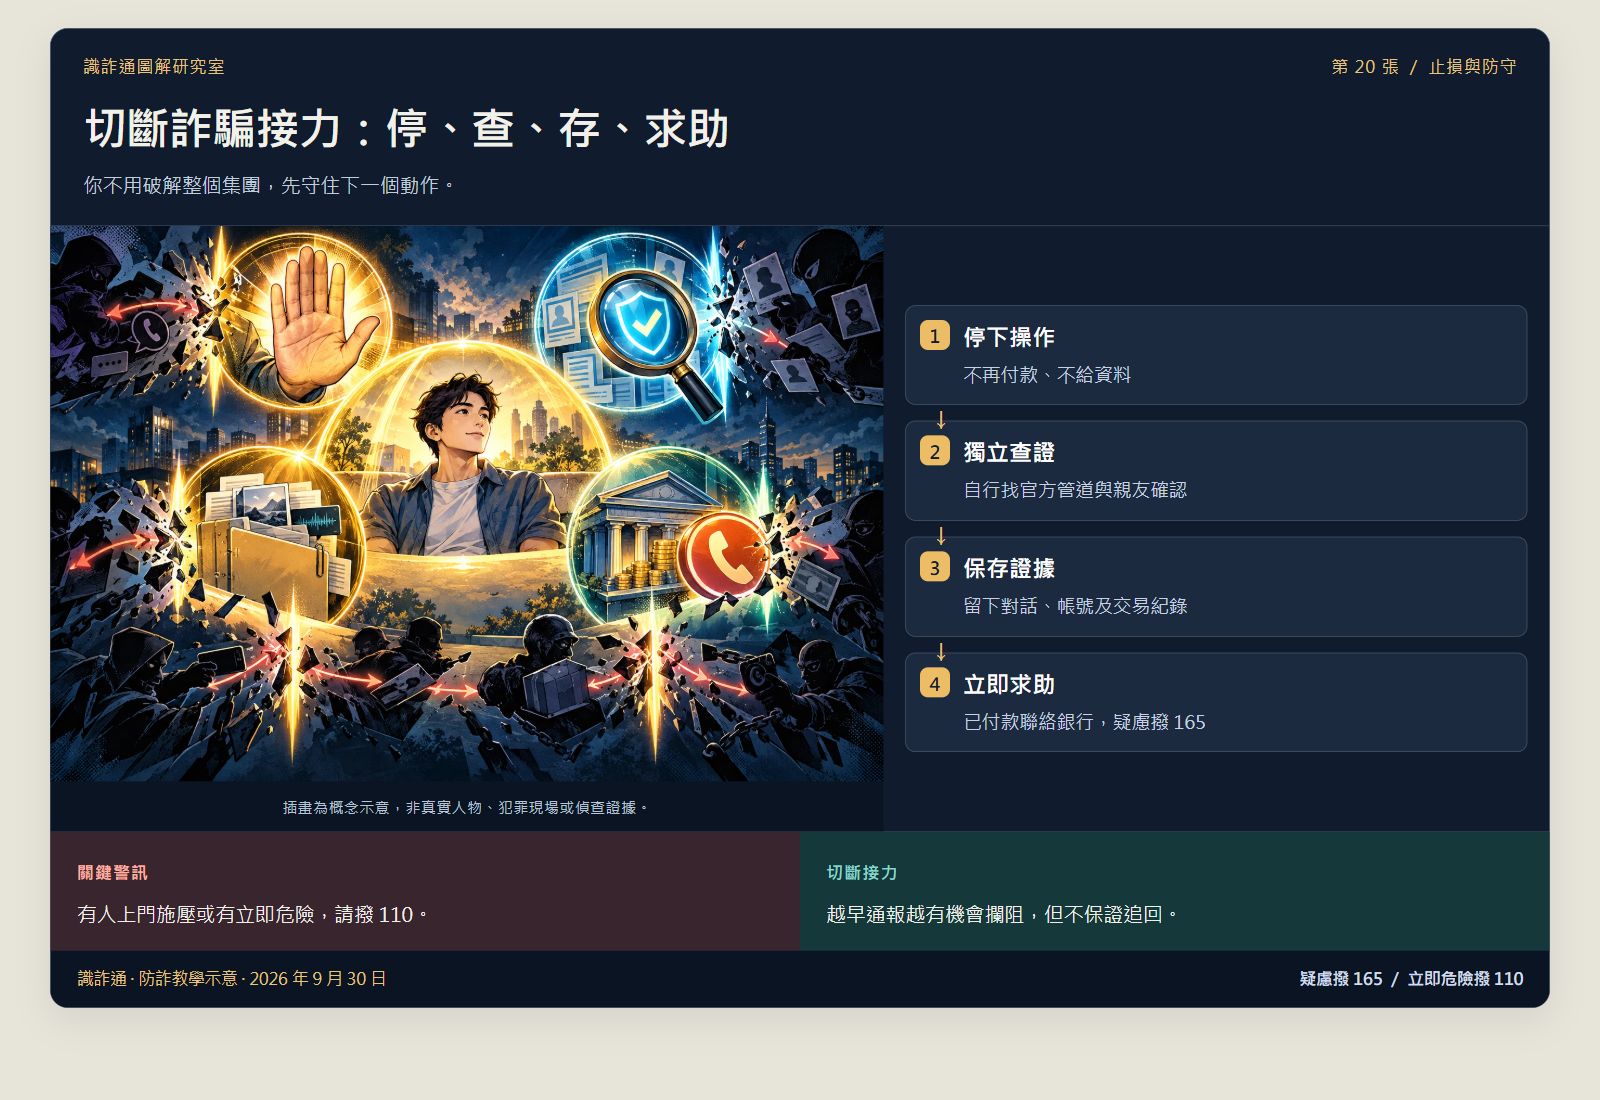
Break the chain: stop, check, save and get help
You do not need to expose the whole operation. Protect your next action.
Conceptual illustration, not real people, a crime scene or investigative evidence.
1
Stop acting
Stop paying and sharing information.
2
Check independently
Find official channels yourself and check with family or friends.
3
Save evidence
Keep conversations, account details and transaction records.
4
Get help immediately
Contact your bank if you paid; call 165 if unsure.
Warning signs
Call 110 if someone pressures you at your door or there is immediate danger.
Protective action
Earlier reporting may improve the chance of interception, but recovery is not guaranteed.
Open sources and scope
Based on official advice and cases. The four stages are simplified for teaching; roles and order differ between cases and do not establish wrongdoing by any particular person or service.
They may be probing vulnerabilities, beyond your preferences.
Pause if an ordinary-looking questionnaire starts seeking financial data, family schedules or your exact address.
Recognise these three signs
Questions about banks and savings
Requests for household schedules
Gifts in exchange for identifying data
01 | Mechanism: how surveys become a data entry point
A caller claiming to conduct a survey may move from everyday topics to family and financial details. Watch for this data collection pattern. The risk is sensitive information enabling impersonation, rather than simply answering a landline.
Credible cover:Policy, brand and satisfaction surveys make the questions seem justified.
Gradual escalation:General preferences lead to questions about banks, exact addresses or family schedules.
Combining information:Your name and bank may later support a fake customer-service story. Knowing your data does not prove identity.
This is risk analysis, not a claim that every survey call is criminal. An area code does not reveal an exact address, household registration or wealth. Age or gender alone does not determine scam vulnerability.
02 | Five questions and the information they expose
“How old are you? Are you retired?”
Purpose analysisAge and occupation can be legitimate statistical questions. Asking next about pension amounts and savings builds a financial profile.
How to respondDecline, or give a broad, less identifying range. Do not disclose assets.
“How many people are home during the day? Do your children live with you?”
Purpose analysisExact living arrangements may reveal when nobody is available to help verify a claim.
How to respond“I prefer not to share family details. Thank you.”
“Do you invest in stocks? Which bank do you use?”
Purpose analysisBank names and investment habits may help disguise later fake service calls or investment pitches.
How to respondNever disclose account details, balances, passwords or verification codes.
“When do your children finish work? When are you home?”
Purpose analysisFamily routines and time spent alone can help choose a moment to apply pressure.
How to respondDo not disclose schedules. Tell your family after hanging up.
“Leave your name and address for a gift voucher.”
Purpose analysisRewards may encourage you to disclose identifying data. A gift proves neither fraud nor safety.
How to respondCheck the organiser, data purpose and necessity before deciding to participate.
03 | From casual conversation to targeted impersonation
Gain trust
Start with a survey and low-sensitivity questions.
Gather information
Collect identifying data, banking relationships or family details.
Disguise identity
Later callers quote real details while posing as banks, police, prosecutors or relatives.
Pressure for money
Urgency, secrecy and “supervised accounts” become excuses to demand transfers or valuables.
This is a teaching model, not an investigative finding. Selling lists or committing particular offences requires case-specific evidence.
04 | Protection: what if you already shared information?
Still on the call:Decline and hang up. Ask the survey company and commissioning body if needed, but a correct business number does not prove identity. Find official contact details yourself.
Family details disclosed:Alert your family to fake relatives, kidnapping and police calls. Call the person using the number you already saved.
Financial data or a code disclosed:Contact your bank through official channels immediately. Explain what leaked, ask about account protection, then consult 165.
Caller ID:“+” usually indicates international format, not evidence of crime. Its absence does not guarantee safety either. Never establish identity from the displayed number alone.
Words you can use
“I do not share family or financial data. I will contact the official organisation myself if I need to check anything.”
05 | Evidence: established facts versus analysis
Official advice supports that leaked data can enable impersonation and caller ID is not proof of identity. The questionnaire examples and connected stages here are educational analysis of the supplied scenario. Available case evidence does not establish the whole proposed survey-crime chain.
When meeting requires payment first, the relationship becomes a collection tool.
See how livestream invitations and pleas for sales support turn affection into repeated payment pressure.
Recognise these three signs
Pay first to meet or chat privately
Sales targets and punishment pressure
More fees before promises are fulfilled
01 | Mechanism: making affection conditional on payment
The warning sign is payment as a condition of a relationship: gifts, points or deposits before meeting, private chat or continuing contact. Sales targets and threatened punishment may make you mistake paying for a duty to care for the person.
Pressure to repay affection:Intense attention first, then demands for financial return.
Fear of loss:Claims that refusal will cause punishment or loss of a meeting opportunity.
Sunk costs:Money already spent makes another payment seem like a way to finally obtain the promise.
This analyses conversation and payment risks. Livestreaming, tipping and changing messaging platforms also have lawful uses; none alone establishes a crime.
02 | The invitation hides a payment threshold
“I’m livestreaming. Come support me.”
Purpose analysisMoving a dating conversation to a payment platform raises risk if rushed and reasonable verification is refused.
How to respondDo not use unknown installation links or pay for romantic promises.
“I’ll be punished for missing my target. Help me.”
Purpose analysisGuilt and responsibility make someone else’s sales target your obligation.
How to respond“I won’t solve your sales target by topping up.”
“I’m losing the PK. Send gifts now to save me.”
Purpose analysisCountdowns, comparisons and crowd pressure reduce thinking time. On-screen votes do not verify a genuine contest.
How to respondLeave the stream, pause payments and review the conversation with someone you trust.
“Upgrade to VIP for private chat, LINE or a meeting.”
Purpose analysisUsing a relationship as a paid reward may create endlessly rising thresholds.
How to respondDo not pay for meetings or disclose prepaid point codes.
“One more deposit and we can meet or refund you.”
Purpose analysisNew fees before earlier promises are kept can drain more money while you try to recover old payments.
How to respondStop adding money. Keep original promises, payment records and recipient details.
03 | Affection, platform switch, more payments, disappearance
Build a persona
Photos and self-descriptions build attraction. Rapid intimacy does not verify identity.
Move platforms
Streaming, popularity tests or work requirements are used to suggest an app or private messages.
Set payment conditions
Sales targets, PK, VIP and deposits create repeated demands for payment.
Delay or disappear
Promises keep being delayed. Questioning them or stopping payment may result in blocking.
Unknown installers, contact access, remote control and requests for intimate images add risks. Permissions should match the function. Official app-store listing is not a guarantee of safety.
04 | Keep evidence before ending contact
Stop payments:Do not pay refund fees, unlocking fees or meeting deposits.
Keep evidence:Save full conversations, account identifiers, platform names, orders, dates and payment records. A single isolated screenshot may miss context.
Contact your payment provider:Tell your bank or payment provider about suspected fraud. Ask about transaction disputes and account protection. Refund eligibility depends on the transaction and evidence.
Seek help and report:Consult 165 and report to police when needed. After preserving evidence, block the person and report them to the platform.
Image-based threats:Do not send more images or money. Keep threats and report to police; do not negotiate alone.
Words you can use
“I won’t pay to meet, chat privately or meet your targets. Stop asking me to top up.”
05 | Evidence: an app name does not establish wrongdoing
The supplied scenario mentioned Kova. Available sources do not establish that the app itself is involved in fraud, so this analysis focuses on observable payment demands, false promises and unknown installers. Inflated votes, multiple chat operators and platform commissions are not treated as proven case facts.
This educational guide does not replace investigation of a platform, payment dispute or crime.
Editorial check: 1 October 2026. Sample scripts are teaching summaries, not verbatim recordings. Use the top menu for other methods and tools.
Common scam methods
Grouped by contact channel. Red borders highlight money and account risks. This independently made site provides educational information; call 165 if unsure.
Traditional / Calls, cash handovers and accounts
Fake police, prosecutors or financial regulators
Warning signs and protective steps
A caller claims to be police, a prosecutor or a financial regulator, accuses you of money laundering and demands savings for a “supervised account”, in secret.
What to doPolice and prosecutors do not demand transfers, cash handovers or passwords by phone. Hang up and call 165 yourself.
“Expert” tips, guaranteed returns or insider information lead to unknown apps and deposits that cannot be withdrawn.
What to doGuaranteed returns are a major warning. Check licensing with the regulator, then confirm the website and app directly with the provider. Legitimate firms can be impersonated.
A fake service agent claims instalments or duplicate charges were set by mistake and sends you to an ATM or online bank to “cancel”.
What to doDo not use an ATM or online bank on an unknown caller’s instructions. Hang up and call the service number on your card to confirm the real procedure.
Easy high pay or daily cash may conceal demands for your account, cash courier work or recruitment into overseas exploitation.
What to doCheck the employer and duties before interviewing. Stop if asked to pay first, surrender accounts or collect money for others. Verify overseas high-pay offers independently.
Fake websites or notices direct payments through stores or ATMs; strangers may also request cash.
What to doStores and ATMs also process legitimate payments. Independently check the item, account and details with the agency. Do not trust domain wording or a stranger’s instructions alone.
Tactics change. Stop first if any of these signs appears.
They rush you.Deadlines, immediate action, account freezing or arrest threats.
They demand secrecy.You are told not to tell family, bank staff or police.
They ask for money or data.Transfers, cash, points, bank cards, passwords or one-time codes (OTP).
They direct your actions.Links, QR codes, unknown apps or new LINE contacts.
They guarantee profit.“No losses”, insider tips and “expert” trading signals.
Caller ID looks official.Caller ID and message sender names can be forged.
Suspicious situation: stop, check, ask
Stop
Do not transfer or share data yet
Urgency and secrecy are warnings. Hang up first; do not call a number supplied by the caller.
Check
Check the official source
Find the official website or number yourself. Do not use their links. Taiwan government sites often use .gov.tw, but some official services use other domains; verify from the agency website rather than domain wording alone.
Ask
Ask family or 165
Tell someone you trust or consult 165. Another person’s view adds protection.
Stop when you hear these demands
These are common scam warnings. Pause payments and data sharing, then verify using official contacts you found yourself.
Police, prosecutors and courtsThey do not require money in a “supervised account” or handover to a home collector. Even if contacted about a case, independently find the official number and verify identity.
BanksStop if someone asks you to “cancel instalments” at an ATM or online bank, or disclose passwords or OTP. Call the number on your card.
Government agenciesCheck subsidies, refunds and fines on the agency’s official site. Do not enter card numbers, passwords or OTP through unknown messages.
E-commerce and deliveryStop if a buyer asks for private service contacts or online banking for “payment verification”. Use contacts published on the platform’s official website.
Scenario quiz
Choose your response to five common situations. Each answer gives an immediate explanation.
Message: “Your ETC toll is overdue. Penalties start today. Tap the link to pay.”
Government and toll messages are often impersonated. Open the official app or type the official URL yourself.
A supposed prosecutor says your account is linked to money laundering, demands secrecy and transfer of savings to a “safe account”.
Police and prosecutors do not demand transfers to “safe” or “supervised” accounts. In this context these are scam terms.
An investment group’s “teacher” guarantees profit, while members post screenshots of earnings.
Members and screenshots may be staged. Small successful withdrawals can be bait to increase deposits, not proof of credibility.
Your “son” calls from a new number, sounds different, needs NT$200,000 after an accident and says not to tell his father.
AI can imitate voices. A changed number and secrecy are warnings. Verify using an existing contact channel.
A buyer says your shop has not activated payment services, asks you to add LINE customer service and follow online banking instructions.
Platforms do not ask buyers to make sellers verify accounts this way. Following strangers’ banking instructions may authorise transfers or disclose transaction access.
Family scam-prevention agreement
Agree on these four habits to reduce fake-relative and fake-police risks. Print and place beside the phone if useful.
Agree on a family code; ask it when someone claims to be family needing urgent money.
Transfers above an agreed amount(such as NT$10,000): discuss with another family member first.
If anyone demands secrecy, tell someone you trust.
Relatives using new numbers: call the old number or verify by video.
What to do if already scammed
Act quickly. Open the steps matching your situation. Being deceived is not your fault.
I transferred money or handed over cash
Report immediately through 165 or 110; provide the time, amount and account, and request assistance notifying a payment stop.
Notify the sending bank immediately; give transaction details and ask about interception or stopping payment. Success depends on the funds’ status; recovery is not guaranteed.
Keep evidence: conversations, account details, URLs, transfer receipts and call records. Do not delete them.
Make a statement at a police station, bringing identification and the evidence above.
Beware of recovery scams: supposed agents, lawyers or hackers offering recovery may be scammers. Do not pay recovery fees or deposits, or grant account access.
I shared personal data, card details or OTP
Contact the card-issuing bank immediately; arrange blocking or loss reporting and review recent transactions.
Change affected passwords using a trusted device; sign out unknown sessions and enable two-factor authentication. Replace reused passwords too.
Report to 165, keeping the caller’s number and website.
Watch for identity misuse: if identity documents leaked, request a personal credit report from Taiwan’s Joint Credit Information Center to check for applications made in your name.
I opened a link or installed an unknown app
Only opened a link, without entering data or installing: close the page and stop downloads or permissions. If you entered passwords, card data or OTP, follow the data-disclosure steps above.
Installed an app, shared a screen or allowed remote control: stop. Disconnect mobile data and Wi-Fi if needed. Airplane mode may leave Wi-Fi on; verify disconnection, then use another device to contact your bank and 165.
Preserve evidence, then ask a trusted technician: record the app, download URL and transactions. Check device administrator, accessibility and profile permissions. Removing the app may delete data; confirm before acting.
Factory reset is a last resort: it deletes device data, settings and possible evidence. Back up necessary data and confirm bank and police procedures before deciding whether to reset.
It is okay to feel overwhelmed.Shame, anxiety and trouble sleeping are common after a scam. Tell someone you trust or call the Ministry of Health and Welfare’s 1925 helpline, free 24 hours a day.
If it has already happened: choose the next step
Keep necessary evidence. Do not include passwords, one-time codes, complete ID documents or intimate images in public reports or requests for help. These are initial steps, not a guarantee of recovery.
You paid or transferred money
Contact your bank or payment provider yourself immediately. Explain the suspected scam and ask what measures are possible. Keep the time, amount, recipient details and transaction ID; ask police or 165 for help. Do not pay further deposits, taxes or recovery fees.
You shared passwords, codes or card details
Use a trusted device to open the official website or app. Follow the provider’s instructions for securing the account and active sessions. Contact the financial institution immediately if banking, cards or payments are involved. Address other accounts using the same password separately. Do not use a reset link sent by the caller.
You installed remote software or shared your screen
End the connection and remote control. Use another trusted device to contact your bank and 165. Save the software name, messages and installation time, and seek trusted technical support. A factory reset removes data and some evidence; arrange preservation and recovery before resetting.
You face threats or intimate-image blackmail
Do not pay or send more images. Save accounts, URLs and threatening messages, ask police for help and report through the platform. For child protection or sexual violence, seek a trusted adult and 113; call 110 for immediate danger. Do not forward intimate images just to report the incident.
Check suspicious numbers and websites
This is a risk-feature checker only. It examines number and URL format, without a scam database. Input stays in this browser and is not uploaded.No detected risk does not mean safe.
Sources and wording for 23 method cards were checked on 1 October 2026. Some official pages could only be checked through search excerpts; full text still needs verification. Links appear on each card. This is not official certification or verification of every statement on the site.
Entered numbers, accounts and URLs are processed only in browser memory. They are not sent to our server, stored in localStorage or included in shares. Closing or reloading clears queries. Text-size and language preferences are stored locally.
There are no memberships, ads or custom analytics. Cloudflare may process IP addresses, times and request logs for connectivity and security; hosting logs may exist. External official sites have their own data policies.
Accessibility and controls
Use Tab to move focus, Enter or Space for buttons, and arrow keys, Home or End for categories. Large text, system dark mode and print styles are supported. No accessibility certification or human screen-reader test has been completed.
Report site problems or content errors
This site is maintained by Xie Wei. Email content errors, broken links or usability problems to haixa534@gmail.com. The link opens your email app; you can edit before sending. This site does not automatically send your queries.
Include the page or card title, problem, suggested correction and official source. For usability issues, add device and browser versions. Hide personal data in screenshots. Do not send identity documents, full account details, passwords, OTP or full private conversations.
This inbox is for website issues, not police reporting or emergency help, and immediate replies are not guaranteed. Refer to official sources when unsure; scam advice: 165, immediate danger: 110.